UK SEO Statistics Updated 29th September 2026
Search in the United Kingdom is entering a period of structural change. Google remains overwhelmingly dominant in conventional search, but the environment surrounding SEO is expanding as AI-generated answers, AI Overviews, conversational assistants and new discovery interfaces alter how information is found, evaluated and consumed.
This CGO Media research brings together 100 quantitative statistics covering the UK search market, internet usage, organic search behaviour, mobile search, local discovery, content and authority, ecommerce, SEO investment, AI search and the changing relationship between traditional rankings and AI-mediated discovery.
The objective is not to assemble a collection of general SEO claims and present them as statistics. Each numbered item in this research must contain a measurable figure, percentage, volume, ratio, change or other quantitative observation supported by an identifiable source or transparently labelled CGO Media calculation.
UK-specific evidence is prioritised wherever credible data is available. Where sufficiently robust UK-only measurements do not exist, international evidence may be included to provide wider context, but it is identified clearly rather than being presented as UK-specific data.
The UK Search Market in 2026
The starting point for understanding UK SEO is the scale of the connected population and the continuing concentration of conventional search activity around Google.
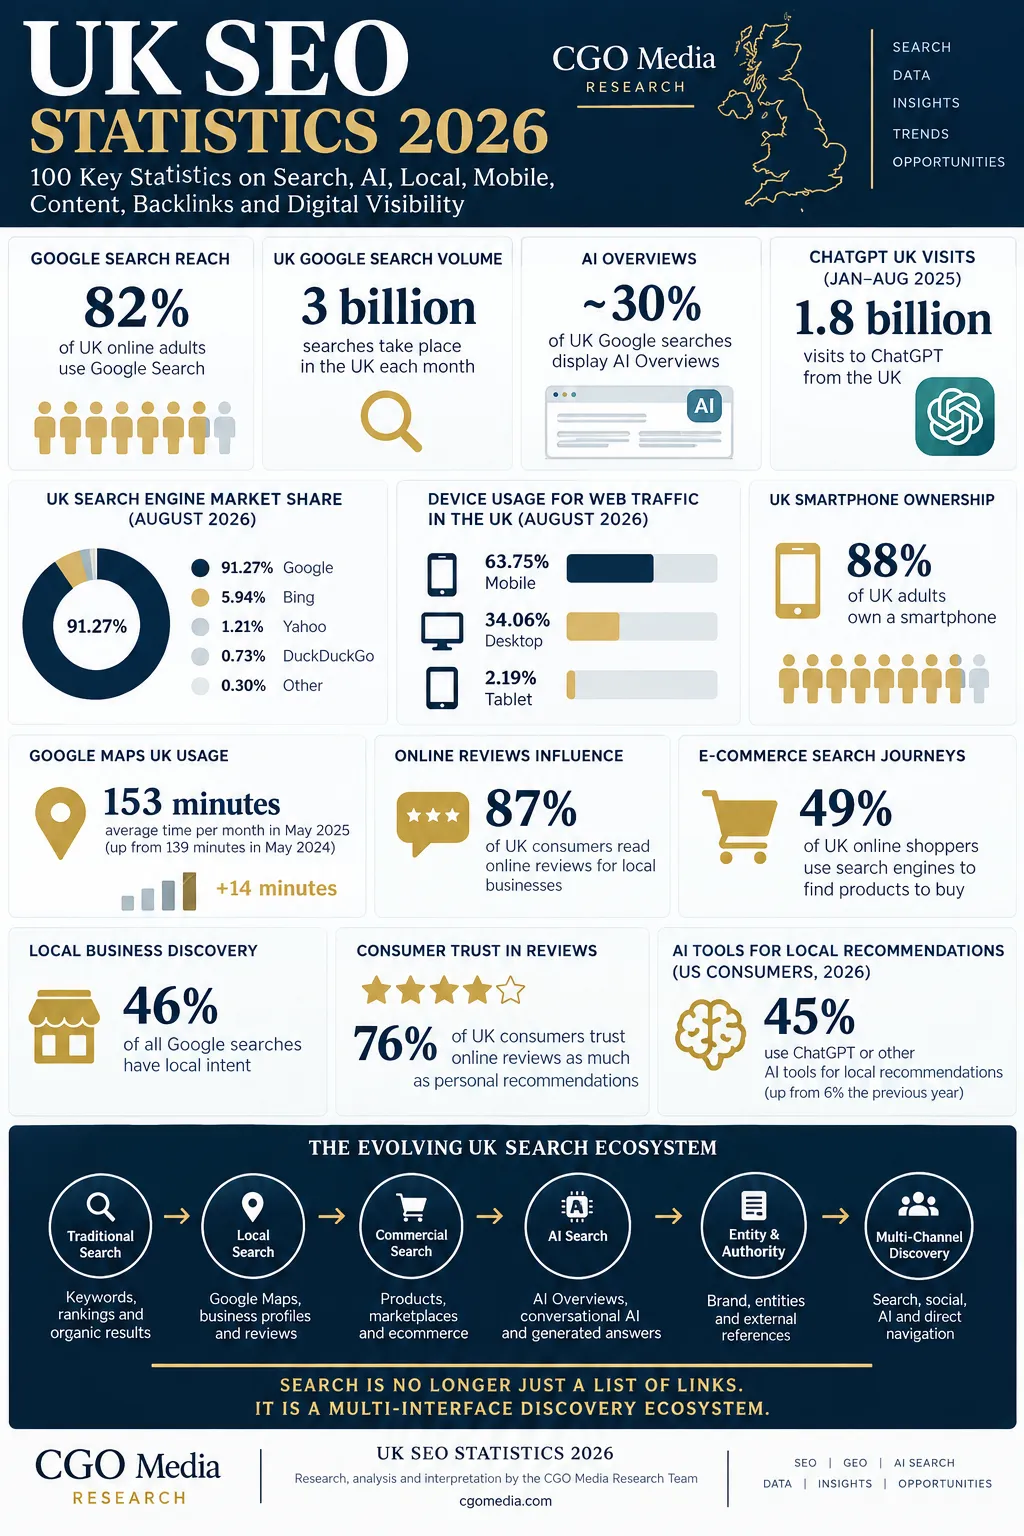
91.75%
Google share of UK search-engine traffic across all platforms, August 2026
82%
of UK adults use Google Search
3 Billion
Google searches per month in the UK according to Ofcom
68.1M
internet users in the United Kingdom at the end of 2025
97.8%
UK internet penetration at the end of 2025
97.62%
Google share of UK mobile search traffic, July 2026
SEO Is Operating Inside a Changing Search Environment
Google’s continuing market dominance does not mean that search behaviour itself is static. Ofcom’s Online Nation 2025 research identified substantial changes in the UK search experience as AI-generated answers became integrated directly into search interfaces.
~30%
Searches Showing AI Overviews
Ofcom reported that approximately 30% of searches were showing AI Overviews in its UK Online Nation research.
53%
Adults Often See AI Summaries
More than half of UK adults told Ofcom that they often encounter AI-generated summaries when using search services.
1.8B
UK ChatGPT Visits
ChatGPT recorded 1.8 billion UK visits during the first eight months of 2025, according to Ofcom.
This does not make traditional SEO obsolete. Instead, it expands the environment in which SEO operates. Organisations increasingly need to consider not only whether a page ranks, but whether their information is visible when search engines generate answers, whether their brand and entities are understood correctly, and whether their content remains discoverable as users move between search engines and AI assistants.
Key Findings
1. Google Remains the Centre of UK Search
With more than 91% of measured UK search-engine traffic across all platforms in August 2026, Google continues to dominate conventional UK search.
2. Mobile Google Search Is Even More Concentrated
Google accounted for 97.62% of UK mobile search-engine traffic in July 2026, demonstrating the particularly high concentration of mobile search.
3. The UK Is Almost Universally Online
The United Kingdom had approximately 68.1 million internet users and 97.8% internet penetration at the end of 2025.
4. Search Remains a Mass-Market Behaviour
Ofcom reports that Google Search alone reaches 82% of UK adults and processes approximately 3 billion UK searches each month.
5. AI Is Becoming Embedded in Search
Around 30% of searches were reported to display AI Overviews, while 53% of UK adults said they often encounter AI-generated summaries.
6. Search Discovery Is Becoming Multi-Platform
ChatGPT’s 1.8 billion UK visits during the first eight months of 2025 illustrate the increasing scale of generative AI services alongside conventional search.
Research Scope
The 100 statistics are organised into ten research areas intended to provide a quantitative view of the UK SEO and search ecosystem rather than treating SEO as a collection of isolated ranking techniques.
| Statistics | Research Area | Primary Focus |
|---|---|---|
| 1–10 | UK Search Market | Google, Bing, alternative engines and market concentration |
| 11–20 | Internet & Search Behaviour | Internet adoption, online activity and search usage |
| 21–30 | Organic Search & Click Behaviour | Organic visibility, rankings, CTR and search-result behaviour |
| 31–40 | Mobile Search & Performance | Mobile search, devices, speed and technical experience |
| 41–50 | Local Search & Reviews | Local discovery, business profiles, maps, reviews and trust |
| 51–60 | Content, Links & Authority | Content performance, backlinks and authority signals |
| 61–70 | Ecommerce & Commercial Search | Product discovery, commercial research and online purchasing |
| 71–80 | SEO Investment & ROI | Marketing investment, acquisition, conversion and commercial performance |
| 81–90 | AI Search & AI Overviews | Generative search, AI summaries and changing click behaviour |
| 91–100 | The 2026 Search Ecosystem | SEO, AI discovery, search diversification and future visibility |
CGO Media Research Standard
A Statistic Must Be Quantitative
This research does not count general SEO principles, recommendations or observations as statistics. Every numbered statistic must contain a measurable quantitative finding.
Measured Data → Source Context → Interpretation → Search Implication
UK-First, Not UK-Only
The research prioritises UK-specific measurements because search-engine usage, internet adoption, device behaviour, consumer activity and market conditions differ between countries.
However, some important SEO questions are measured primarily through international datasets. Ranking click-through studies, large-scale backlink research, web-performance datasets and certain AI-search studies may therefore be included where they provide useful evidence that cannot be replicated reliably using UK-only data.
Where international evidence is used, its geographic scope will be identified. International statistics should provide context for UK organisations rather than being misrepresented as measurements of UK behaviour.
Sources & Measurement Notes
StatCounter Global Stats: UK search-engine market-share measurements. August 2026 all-platform data records Google at 91.75%, Bing at 5.67%, Yahoo at 1.25%, DuckDuckGo at 0.71%, Ecosia at 0.30% and Yandex at 0.28%.
Ofcom Online Nation 2025: UK search-service usage and emerging AI-search behaviour. Ofcom reports Google Search usage among 82% of UK adults, approximately 3 billion Google searches per month, AI Overviews on around 30% of searches, and 53% of adults often seeing AI summaries.
DataReportal Digital 2026: The United Kingdom: 68.1 million UK internet users at the end of 2025 and 97.8% internet penetration. The report notes that internet-user measurements can lag current conditions because of data collection and publication delays.
Measurement caution: Market-share, audience, traffic and search-volume datasets use different methodologies and populations. Figures from different providers should not be treated as directly interchangeable without considering their measurement basis.
Statistics 1–10
UK Search Market & Search Engine Usage
The UK search-engine market remains highly concentrated. Google continues to account for the overwhelming majority of measured search-engine traffic, although Bing, Yahoo, DuckDuckGo, Ecosia and Yandex maintain smaller positions within the market.
The degree of concentration varies by device. Google’s position is particularly strong on mobile, while Bing has a substantially larger presence within desktop search. These differences matter when organisations assess search visibility, audience reach and the platforms that should be included in SEO measurement.
Statistic 1
Google Held 91.75% of the UK Search-Engine Market in August 2026
StatCounter measured Google at 91.75% of UK search-engine market share across all platforms in August 2026. This means more than nine out of every ten measured UK search-engine interactions in the dataset were attributed to Google.
Statistic 2
Bing Held 5.67% of the UK Search-Engine Market
Microsoft Bing was the second-largest measured search engine in the UK in August 2026, accounting for 5.67% of search-engine market share across all platforms.
Statistic 3
Yahoo Accounted for 1.25% of UK Search-Engine Traffic
Yahoo represented 1.25% of measured UK search-engine market share in August 2026, placing it behind Google and Bing but ahead of DuckDuckGo, Ecosia and Yandex.
Statistic 4
DuckDuckGo Held 0.71% of UK Search-Engine Market Share
Privacy-focused search engine DuckDuckGo accounted for 0.71% of UK search-engine traffic measured by StatCounter in August 2026.
Statistic 5
Ecosia Accounted for 0.30% of UK Search-Engine Traffic
Ecosia held 0.30% of measured UK search-engine market share in August 2026. Its market position remains small compared with Google and Bing but measurable within the wider UK search ecosystem.
Statistic 6
Yandex Held 0.28% of the UK Search-Engine Market
Yandex represented 0.28% of UK search-engine market share in StatCounter’s August 2026 all-platform dataset.
Statistic 7
Google Controlled 97.6% of UK Mobile Search in August 2026
Google’s dominance becomes even stronger when the market is restricted to mobile devices. StatCounter measured Google at 97.6% of UK mobile search-engine market share in August 2026.
Statistic 8
Bing Accounted for Just 0.48% of UK Mobile Search
Bing’s share of UK mobile search-engine traffic was only 0.48% in August 2026. This contrasts sharply with its stronger position when desktop activity is included.
Statistic 9
Google Search Reached 82% of UK Online Adults
Ofcom reported that 82% of UK online adults used Google Search in May 2025. Reach had declined slightly from 83% in 2024 and 86% in 2023, but Google Search remained one of the UK’s most widely used online services.
Statistic 10
Google Handles Around 3 Billion Searches Per Month in the UK
Ofcom reports that Google Search handles approximately 3 billion searches per month in the United Kingdom, illustrating the continuing scale of conventional search even as generative AI services gain adoption.
UK Search-Engine Market Share — August 2026
| Search Engine | All Platforms | Mobile |
|---|---|---|
| 91.75% | 97.60% | |
| Bing | 5.67% | 0.48% |
| Yahoo | 1.25% | 0.68% |
| DuckDuckGo | 0.71% | 0.60% |
| Ecosia | 0.30% | 0.30% |
| Yandex | 0.28% | 0.30% |
What the UK Search Market Data Shows
The most important characteristic of the UK search market is concentration. Google’s 91.75% all-platform share means that traditional SEO programmes aimed at UK audiences still need to treat Google visibility as a central acquisition and discovery channel.
However, the device-level data shows why market-share figures should not be interpreted as a single uniform audience. Google’s mobile share reaches 97.6%, while Bing falls to just 0.48%. Bing’s overall 5.67% share therefore reflects a considerably stronger position outside mobile search.
Google’s Mobile Advantage
Google’s UK mobile share was 5.85 percentage points higher than its all-platform share in August 2026.
CGO Media Calculation: 97.60% − 91.75% = 5.85 percentage points.
The Ofcom audience data adds another dimension. Market share measures distribution between search engines, whereas audience reach measures how many people actually use a service. Google Search reached 82% of UK online adults in May 2025 and generated approximately 3 billion UK searches per month.
For SEO strategy, these figures support a dual approach: maintain strong Google-focused organic search foundations while monitoring smaller search engines and emerging AI discovery platforms as the wider search ecosystem diversifies.
Sources & Measurement Notes
StatCounter Global Stats — United Kingdom, August 2026: Used for Statistics 1–8 and the market-share comparison table. StatCounter’s figures represent measured search-engine market share from its web analytics network and should be interpreted as traffic-share measurements rather than population surveys.
Ofcom Online Nation 2025: Used for Statistics 9–10. Google Search reached 82% of UK online adults in May 2025 and Ofcom reports approximately 3 billion Google searches per month in the UK.
Geographic scope: All ten numbered statistics in this section relate specifically to the United Kingdom. Measurement dates are stated because market share and audience behaviour change over time.
Statistics 11–20
UK Internet & Search Behaviour
SEO operates inside one of the world’s most highly connected digital markets. Almost the entire UK population now uses the internet, adults spend several hours online each day, and smartphones account for the majority of personal online time.
These behaviours matter because search does not operate independently from the wider digital environment. Users move between search engines, maps, social platforms, websites, video services and increasingly AI assistants while researching information, organisations, products and services.
Statistic 11
68.1 Million People Used the Internet in the UK
DataReportal’s Digital 2026 UK report estimates that there were 68.1 million internet users in the United Kingdom in October 2025. This provides the population-scale digital environment in which UK organic search operates.
Statistic 12
UK Internet Penetration Reached 97.8%
Internet penetration stood at 97.8% of the UK population at the end of 2025 according to DataReportal. Search visibility therefore operates within a market where internet access is close to universal at population level.
Statistic 13
95% of UK People Aged 16+ Had Internet Access at Home
Ofcom reported that 95% of the UK population aged 16 and over had access to the internet at home in 2025. Conversely, 5% reported having no home internet access.
Statistic 14
UK Adults Spent an Average 4 Hours 30 Minutes Online Per Day
Ofcom measured average personal online use across smartphones, tablets and computers at 4 hours 30 minutes per adult per day in May 2025.
Statistic 15
Daily Online Time Increased by 10 Minutes in One Year
Average daily personal online time among UK adults increased by 10 minutes between 2024 and 2025, according to Ofcom.
Statistic 16
UK Adults Aged 18–24 Spent 6 Hours 20 Minutes Online Each Day
Young adults recorded the highest online use in Ofcom’s age analysis. People aged 18–24 spent an average of 6 hours 20 minutes online per day in May 2025.
Statistic 17
UK Adults Aged 65+ Spent 3 Hours 20 Minutes Online Per Day
Adults aged 65 and over recorded the lowest average among Ofcom’s adult age groups, but still spent 3 hours 20 minutes online per day. Digital discovery is therefore not confined to younger UK consumers.
Statistic 18
Smartphones Accounted for 75% of Men’s Personal Online Time
Ofcom found that smartphones accounted for 75% of men’s personal online time in May 2025, substantially exceeding time spent on computers and tablets.
Statistic 19
Smartphones Accounted for 79% of Women’s Personal Online Time
The smartphone share was even higher among women, accounting for 79% of personal online time. This reinforces the importance of mobile-first search and website experiences for UK audiences.
Statistic 20
51% of UK Online Time Was Spent on Alphabet or Meta Services
Ofcom found that 51% of UK adults’ online time was spent using services owned by Alphabet or Meta. Digital attention is therefore highly concentrated even though individual discovery journeys can span search, video, maps, messaging and social platforms.
UK Online Behaviour at a Glance
| Measurement | UK Figure |
|---|---|
| Internet users | 68.1 million |
| Internet penetration | 97.8% |
| People aged 16+ with home internet access | 95% |
| Average adult personal online time | 4h 30m/day |
| 18–24 online time | 6h 20m/day |
| 65+ online time | 3h 20m/day |
| Men’s online time on smartphones | 75% |
| Women’s online time on smartphones | 79% |
What This Means for UK SEO
The first implication is scale. With 68.1 million internet users and penetration approaching 98%, online discovery is relevant to almost every consumer-facing and business-facing sector in the UK.
The second implication is intensity. An average of four and a half hours of personal online activity per day gives UK consumers repeated opportunities to encounter organisations through search results, maps, websites, video, social platforms and AI-assisted interfaces.
Age Changes the Scale of Online Exposure, Not Its Existence
Adults aged 18–24 spent three hours more online each day than adults aged 65+ in Ofcom’s 2025 measurement.
CGO Media Calculation: 6 hours 20 minutes − 3 hours 20 minutes = 3 hours.
The third implication is mobile dependence. Smartphones account for approximately three-quarters or more of personal online time for both men and women. Mobile technical performance, mobile SERP presentation and mobile conversion experience therefore sit directly inside the wider SEO performance equation.
Finally, the concentration of online attention within Alphabet and Meta services demonstrates why modern SEO increasingly overlaps with a wider discovery ecosystem. Google Search remains central, but search behaviour occurs alongside YouTube, Google Maps and other platforms through which people investigate organisations, locations, products and information.
CGO Media Research Position
SEO Operates Inside a Wider Digital Discovery Journey
UK consumers do not remain inside a single discovery interface. They move between search, maps, websites, video, social platforms and increasingly AI services as they gather information and evaluate choices.
Internet Access → Search → Content Discovery → Evaluation → Cross-Platform Validation → Action
Sources & Measurement Notes
DataReportal — Digital 2026: The United Kingdom: Used for Statistics 11–12. DataReportal reports 68.1 million internet users in the UK in October 2025 and internet penetration of 97.8%.
Ofcom — Online Nation 2025: Used for Statistics 13–20. Ofcom’s adult online-time measurements cover personal use on smartphones, tablets and computers and do not represent all workplace internet activity.
Measurement period: Most Ofcom behaviour measurements in this section relate to May 2025. They are used in this 2026 research because they form part of Ofcom’s latest completed annual Online Nation evidence available for the period.
Geographic scope: All ten numbered statistics in this section are UK-specific.
Statistics 21–30
Organic Search Traffic & Click Behaviour
Ranking remains important in organic search, but a ranking position no longer produces a predictable level of traffic in isolation. Search-result layouts, AI Overviews, query intent, device type, brand demand and other SERP features can substantially alter the proportion of searchers who click an organic result.
The measurements in this section illustrate that change. Because current large-scale UK-only CTR datasets are limited, the statistics below use international search evidence where appropriate. These measurements should be treated as evidence about modern Google click behaviour rather than direct measurements of UK searchers.
Statistic 21
The Average Number-One Google Result Recorded a 20.02% CTR
Advanced Web Ranking measured an average organic click-through rate of 20.02% for the number-one Google result across the SERP types in its July 2026 US desktop dataset.
International evidence: Google US desktop, July 2026.
Statistic 22
Position-One CTR Fell to 9.69% When an AI Overview Appeared
On search-result pages containing a Google AI Overview, Advanced Web Ranking measured average position-one organic CTR at just 9.69%.
International evidence: Google US desktop, July 2026.
Statistic 23
AI Overviews Reduced Position-One CTR by Approximately 52%
The difference between the overall position-one CTR and position-one CTR on AI Overview SERPs represents an approximately 52% relative reduction in Advanced Web Ranking’s July 2026 analysis.
Source measurement: 20.02% versus 9.69%. International evidence.
Statistic 24
AI Overviews Appeared on 43% of Sampled Desktop SERPs
Advanced Web Ranking found AI Overviews on 43% of the sampled Google desktop search-result pages in its July 2026 US dataset.
International evidence: Google US desktop, July 2026.
Statistic 25
74.3% of AI Overview SERPs Produced No Organic Click
Advanced Web Ranking measured a 74.3% zero-organic-click rate on search-result pages containing an AI Overview.
International evidence: Google US desktop, July 2026.
Statistic 26
53.6% of SERPs Without an AI Overview Produced No Organic Click
Even without an AI Overview, Advanced Web Ranking recorded a 53.6% zero-organic-click rate. More than half of the measured search-result pages therefore ended without a recorded organic result click.
International evidence: Google US desktop, July 2026.
Statistic 27
Only 8% of Visits With an AI Summary Led to a Traditional Search-Result Click
In Pew Research Center’s behavioural analysis, users clicked a traditional Google search-result link after only 8% of visits to search pages containing an AI-generated summary.
International evidence: 900 US adults and 68,879 Google searches, March 2025.
Statistic 28
Traditional Result Clicks Rose to 15% When No AI Summary Appeared
When no AI-generated summary appeared, Pew found users clicked a traditional search-result link after 15% of Google search visits — nearly twice the 8% rate measured when an AI summary was present.
International evidence: US behavioural panel, March 2025.
Statistic 29
Only 1% of Visits to AI Summary SERPs Produced a Click on an AI-Cited Source
Pew found that users clicked a source link contained within Google’s AI-generated summary after only 1% of visits to search-result pages displaying such a summary.
International evidence: US behavioural panel, March 2025.
Statistic 30
26% of AI-Summary Search Visits Ended the Browsing Session
Pew found that users ended their browsing session after 26% of Google search visits containing an AI summary, compared with 16% after pages containing traditional search results without an AI summary.
International evidence: US behavioural panel, March 2025.
How AI Answers Are Changing Organic Click Behaviour
| Measurement | AI Summary / Overview | Without AI Summary / Overview |
|---|---|---|
| AWR position-one organic CTR | 9.69% | Higher; 20.02% across all SERP types |
| AWR zero-organic-click rate | 74.3% | 53.6% |
| Pew traditional-result click rate | 8% | 15% |
| Pew session ended after search | 26% | 16% |
| Pew click on AI-cited source | 1% | Not applicable |
Ranking Position and Traffic Are No Longer the Same Measurement
The central implication is that organic ranking position cannot be interpreted independently from the search-result environment surrounding it. A number-one ranking remains valuable, but the number of clicks available to that ranking changes substantially according to what else appears on the SERP.
Advanced Web Ranking’s July 2026 evidence illustrates this directly. Its average number-one organic result recorded a 20.02% CTR across SERP types, but the same position averaged only 9.69% when an AI Overview was present.
The Click Gap Is Substantial
The difference between a 20.02% position-one CTR and a 9.69% position-one CTR is 10.33 percentage points.
CGO Media Calculation: 20.02% − 9.69% = 10.33 percentage points.
Pew’s behavioural research reaches the same directional conclusion using a very different methodology. Rather than estimating CTR by ranking position, Pew tracked what users actually did after performing Google searches. Traditional-result clicks occurred after 15% of visits without an AI summary but only 8% when one appeared.
The precise percentages should not be combined because the methodologies differ. The important finding is that both independent datasets identify materially lower outbound organic clicking when AI-generated search answers are present.
SEO Measurement Needs to Move Beyond Rankings
A reporting model based only on average ranking position can miss substantial changes in actual search performance. Two periods can show the same ranking while generating different impression, click and traffic outcomes because the surrounding SERP has changed.
Rankings
Where pages appear within conventional organic search results.
Impressions
How often searchers have an opportunity to encounter the organisation.
Organic CTR
How efficiently search visibility turns into website visits.
SERP Features
AI Overviews and other search features that can alter click distribution.
AI Visibility
Whether an organisation or its sources appear within generated answers.
Conversions
Whether organic discovery ultimately produces meaningful business outcomes.
CGO Media Research Position
Organic Visibility Is Becoming Larger Than the Organic Click
Traditional SEO measurement assumed that higher rankings created greater visibility and that greater visibility produced more clicks. AI-generated search experiences weaken the certainty of that relationship because information can now be consumed before a website visit occurs.
Ranking → SERP Visibility → Citation / Presentation → Click Opportunity → Website Visit → Conversion
Sources & Measurement Notes
Advanced Web Ranking — Google Organic CTR Study, July 2026: Used for Statistics 21–26. The study tracks more than 1.75 million US Google SERPs per month, including approximately 1 million desktop and 750,000 mobile SERPs. Statistics in this section specifically identify the July 2026 US desktop measurements where applicable.
Pew Research Center — Google Search Behaviour Study, March 2025: Used for Statistics 27–30. Pew analysed browsing behaviour from 900 US adults and 68,879 unique Google searches.
Methodological caution: Advanced Web Ranking and Pew use different methodologies. Their percentages should not be treated as directly equivalent measures. They independently provide evidence that AI-generated search answers are associated with lower outbound organic clicking.
Geographic scope: Statistics 21–30 are international contextual evidence based primarily on US search behaviour. They are included because sufficiently robust, current UK-only position-by-position organic CTR evidence is not available at comparable scale. These figures are not presented as UK-specific measurements.
Mobile, Desktop Search & Website Performance
Device context remains important to SEO performance. Google is even more dominant on mobile, while alternative search engines—particularly Bing—have a materially larger presence on desktop. Website performance also remains a measurable component of the search experience, with Core Web Vitals providing a framework for assessing loading performance, responsiveness and visual stability.
31. Google Held 85.90% of UK Desktop Search Engine Market Share
Google accounted for 85.90% of measured UK desktop search engine market share in August 2026. Although Google remains overwhelmingly dominant on desktop, its desktop share is lower than its share across UK mobile search.
Source: StatCounter Global Stats, United Kingdom,
Desktop Search Engine Market Share, August 2026.
32. Bing Held 10.38% of UK Desktop Search Engine Market Share
Bing represented 10.38% of measured UK desktop search engine market share in August 2026. This is substantially higher than Bing’s share on mobile and demonstrates why desktop search behaviour should not be inferred directly from all-device market-share figures.
Source: StatCounter Global Stats, United Kingdom,
Desktop Search Engine Market Share, August 2026.
33. Yahoo Held 2.20% of UK Desktop Search Engine Market Share
Yahoo accounted for 2.20% of measured UK desktop search engine market share in August 2026, making it the third-largest search
engine within StatCounter’s UK desktop dataset for the month.
Source: StatCounter Global Stats, United Kingdom,
Desktop Search Engine Market Share, August 2026.
34. DuckDuckGo Held 0.85% of UK Desktop Search Engine Market Share
Privacy-focused search engine DuckDuckGo represented 0.85% of measured UK desktop search engine market share in August 2026.
Source: StatCounter Global Stats, United Kingdom,
Desktop Search Engine Market Share, August 2026.
35. Ecosia Held 0.36% of UK Desktop Search Engine Market Share
Ecosia accounted for 0.36% of measured UK desktop search engine market share in August 2026. Although small relative to Google and Bing, the measurement illustrates the wider range of search environments operating within the UK market.
Source: StatCounter Global Stats, United Kingdom,
Desktop Search Engine Market Share, August 2026.
36. 55.7% of Measured Origins Passed All Three Core Web Vitals
In the July 2026 Chrome UX Report dataset, approximately 55.7% of measured origins achieved a good rating across all three Core Web Vitals: Largest Contentful Paint, Interaction to Next Paint and Cumulative Layout Shift.
Source: Google Chrome UX Report, July 2026.
Geography: Global.
37. 68.3% of Measured Origins Achieved Good LCP
Approximately 68.3% of origins in the July 2026 Chrome UX Report achieved a good Largest Contentful Paint rating, providing a broad measure of satisfactory loading performance.
Source: Google Chrome UX Report, July 2026.
Geography: Global.
38. 85.7% of Measured Origins Achieved Good INP
Approximately 85.7% of measured origins achieved a good Interaction to Next Paint rating in the July 2026 Chrome UX Report, indicating that the majority of measured origins met Google’s good responsiveness threshold.
Source: Google Chrome UX Report, July 2026.
Geography: Global.
39. 81.6% of Measured Origins Achieved Good CLS
Approximately 81.6% of measured origins achieved a good Cumulative Layout Shift rating in the July 2026 Chrome UX Report, indicating comparatively strong visual stability across the measured web.
Source: Google Chrome UX Report, July 2026.
Geography: Global.
40. The July 2026 Chrome UX Report Covered More Than 18 Million Origins
The July 2026 Chrome UX Report dataset contained approximately 18.1 million origins, providing large-scale real-user performance data for assessing Core Web Vitals and broader web performance patterns.
Source: Google Chrome UX Report, July 2026.
Geography: Global.
Device Context Changes the UK Search Market
The desktop figures demonstrate why an all-device search market-share
percentage does not tell the complete story. Google remains dominant, but
Bing’s presence is substantially stronger on UK desktop devices than on
mobile.
At the same time, Core Web Vitals data shows that technical user
experience remains measurable at enormous scale. For SEO teams, device
distribution, search-engine distribution and real-user website performance
should therefore be evaluated together rather than as isolated metrics.
Measurement note:
StatCounter market-share figures are based on measured search-engine referrals/page views within its network and should not be interpreted as a literal census of every search query performed in the United Kingdom. Chrome UX Report figures are global real-user performance measurements and are included as international technical-search context rather than UK-specific measurements.
Statistics 41–50
Local Search, Google Maps & Reviews
Local search sits at the intersection of search engines, maps, business information, reputation and consumer decision-making. For UK organisations with physical locations or geographically defined service areas, visibility is no longer limited to conventional organic rankings.
Google Maps reaches a substantial majority of UK online adults, while online reviews influence product and service research and significant levels of consumer spending. Review recency, rating, volume and sentiment also affect how consumers evaluate individual businesses after discovery.
Statistic 41
Google Maps Reached 78% of UK Online Adults
Ofcom reported that 78% of UK online adults used Google Maps in May 2025, making Maps one of Alphabet’s highest-reaching services in the United Kingdom.
Statistic 42
Google Maps Reach Increased by 9 Percentage Points Between 2023 and 2025
Google Maps reached 69% of UK online adults in May 2023, 73% in May 2024 and 78% in May 2025.
CGO Media Calculation: 78% − 69% = 9 percentage points.
Statistic 43
UK Adults Spent an Average 153 Minutes Per Month Using Google Maps
Average time spent per Google Maps user reached 153 minutes during May 2025, according to Ofcom, up from 139 minutes in May 2024.
Statistic 44
89% of Consumers Use Online Reviews When Researching Products or Services
The UK Competition and Markets Authority cites research showing that 89% of consumers use online customer reviews when researching a product or service.
Statistic 45
Online Reviews Potentially Influence £23 Billion of UK Consumer Spending Each Year
The Competition and Markets Authority estimates that as much as £23 billion of UK consumer spending annually is potentially influenced by online reviews across the sectors examined in its research.
Statistic 46
97% of Consumers Read Reviews for Local Businesses
BrightLocal’s 2026 Local Consumer Review Survey found that 97% of consumers read online reviews for local businesses.
International evidence: representative panel of 1,002 US adult consumers.
Statistic 47
41% of Consumers Always Read Reviews When Browsing for Businesses
In BrightLocal’s 2026 survey, 41% of consumers said they always read reviews when browsing for businesses, compared with 29% in the previous year’s survey.
International evidence: US consumer survey.
Statistic 48
47% Would Not Use a Business With Fewer Than 20 Reviews
BrightLocal found that 47% of consumers would not use a business with fewer than 20 reviews, demonstrating that review volume can affect perceived confidence alongside the overall rating.
International evidence: US consumer survey.
Statistic 49
74% of Consumers Focus on Reviews Written Within the Previous Three Months
Review recency has become an important consideration. BrightLocal found that 74% of consumers seek reviews written within the previous three months, while 18% are influenced only by reviews from the previous week.
International evidence: US consumer survey.
Statistic 50
85% Were More Likely to Use a Business After Reading Positive Reviews
BrightLocal’s 2026 survey found that 85% of consumers were more likely to use a business after reading positive reviews. Conversely, 77% said negative reviews made them less likely to choose a business.
International evidence: US consumer survey.
Google Maps Growth in the UK
| Measurement | 2023 | 2024 | 2025 |
|---|---|---|---|
| UK online adult reach | 69% | 73% | 78% |
| Monthly time per person | — | 139 min | 153 min |
Reviews Are Part of the Discovery and Validation Journey
Local discovery does not end when a business appears in search or Maps. Consumers can move from discovery into a validation stage in which reviews, ratings, websites and other independent evidence influence whether the organisation remains under consideration.
89%
Use Reviews
UK evidence cited by the CMA on consumers researching products and services.
£23B
Potential Influence
Annual UK consumer spending potentially influenced by online reviews.
74%
Want Recent Reviews
International evidence showing the importance of reviews from the previous three months.
85%
Positive Review Effect
International evidence on consumers becoming more likely to choose a business.
Review Quality Is Multi-Dimensional
The evidence suggests that review performance cannot be reduced to an average star rating. Consumers also consider whether multiple reviewers report similar experiences, how recently reviews were written, how many reviews exist and whether the business responds to feedback.
BrightLocal’s 2026 international research found that 56% of consumers valued seeing similar sentiment repeated across multiple reviews, 46% considered whether the written review described a positive experience, 44% considered whether the review had been posted within the previous month and 42% considered a high star rating.
Local Reputation Requires Continuous Evidence
If 74% of consumers seek reviews written within the previous three months, a large historical review total does not necessarily provide the same reassurance as an actively maintained stream of recent customer feedback.
International behavioural evidence — BrightLocal Local Consumer Review Survey 2026.
Fake Reviews Are Also a UK Compliance Issue
The commercial importance of reviews is accompanied by increasing regulatory scrutiny. The UK’s Competition and Markets Authority has taken action intended to reduce fake and misleading reviews and has published guidance for businesses and review platforms.
In a compliance review of more than 100 businesses, the CMA identified 54 that it said could be failing to comply with its guidance on fake and incentivised reviews. In March 2026, the CMA also opened five new consumer-protection enforcement investigations concerning online review practices.
For organisations, this means review strategy should focus on generating genuine customer feedback and maintaining accurate reputation signals rather than attempting to manipulate review volume or sentiment.
CGO Media Research Position
Local SEO Is a Discovery, Validation and Trust System
Local visibility does not depend on a single ranking. Organisations need to be discoverable across search and maps, accurately represented through their business information, and supported by sufficient external evidence for consumers to validate the choice.
Local Query → Search / Maps Visibility → Business Information → Reviews & Reputation → Website Validation → Contact / Visit / Purchase
Sources & Measurement Notes
Ofcom — Online Nation 2025: Used for Statistics 41–43. Google Maps reached 78% of UK online adults in May 2025, compared with 73% in 2024 and 69% in 2023. Average monthly time per person increased from 139 minutes in May 2024 to 153 minutes in May 2025.
Competition and Markets Authority: Used for Statistics 44–45 and UK regulatory context. The CMA cites Which? research reporting that 89% of consumers use online customer reviews when researching products or services and CMA research estimating that as much as £23 billion of UK consumer spending annually may be influenced by online reviews.
BrightLocal — Local Consumer Review Survey 2026: Used for Statistics 46–50 and additional review-behaviour context. The research surveyed a representative panel of 1,002 US adult consumers.
Geographic scope: Statistics 41–45 use UK evidence. Statistics 46–50 use US consumer research as international contextual evidence and should not be interpreted as direct measurements of UK consumers.
Statistics 51–60
Content, Backlinks & Search Authority
Publishing content does not automatically create organic search visibility. Large-scale studies of the web consistently show that the distribution of organic traffic is highly uneven, with a relatively small proportion of pages generating measurable search visits.
Search demand, relevance, search intent, competition, internal authority and external links can all affect whether content becomes discoverable. Backlink studies also continue to identify relationships between stronger link profiles and higher-ranking pages, although correlation should not be interpreted as proof that any individual metric directly causes a ranking.
Statistic 51
96.55% of Pages Received No Estimated Organic Traffic From Google
Ahrefs analysed approximately 14 billion pages in its Content Explorer database and found that 96.55% received no estimated organic search traffic from Google.
Global dataset — not UK-specific.
Statistic 52
Only 3.45% of Pages Received Any Estimated Google Search Traffic
If 96.55% of pages receive no estimated Google search traffic, only 3.45% of pages in the analysed dataset receive one or more estimated organic visits.
CGO Media Calculation: 100% − 96.55% = 3.45%. Global evidence.
Statistic 53
1.94% of Pages Received Between One and Ten Monthly Google Visits
Ahrefs found that 1.94% of pages in its approximately 14-billion-page study received between one and ten estimated organic visits from Google per month.
Global dataset — estimated organic traffic.
Statistic 54
Ahrefs’ Content Study Analysed Approximately 14 Billion Pages
The organic traffic findings were derived from an analysis of approximately 14 billion pages contained within Ahrefs’ Content Explorer database.
Global dataset.
Statistic 55
Only 2,997 Backlink-Free Pages Exceeded 1,000 Estimated Monthly Search Visits
Ahrefs identified approximately 20 million pages with no referring domains. Of those pages, only 2,997 received more than 1,000 estimated organic search visits per month.
Global dataset — estimated search traffic.
Statistic 56
Roughly 1 in 6,671 Pages Without Referring Domains Exceeded 1,000 Monthly Search Visits
Based on the approximately 20 million backlink-free pages examined by Ahrefs, only around one in every 6,671 pages generated more than 1,000 estimated monthly organic search visits.
Ahrefs calculation based on its Content Explorer dataset. Global evidence.
Statistic 57
The Number-One Google Result Had 3.8× More Backlinks Than Positions 2–10
A Backlinko analysis conducted with Ahrefs found that the number-one Google result had an average of 3.8 times more backlinks than pages ranking in positions two through ten.
International Google ranking study — correlation does not establish causation.
Statistic 58
The Ranking Study Analysed 11.8 Million Google Search Results
The Backlinko ranking study examined 11.8 million Google search results, analysing relationships between rankings and factors including backlinks, referring domains, domain authority, content and page performance.
International Google search dataset.
Statistic 59
Ahrefs’ Link-Traffic Study Examined 44,589 Non-Branded Keywords
In separate research into the relationship between backlinks and rankings, Ahrefs analysed the top ten results for 44,589 non-branded keywords with monthly search volumes between 2,000 and 5,000.
International ranking-correlation study.
Statistic 60
Organic Search Accounted for 16.04% of Traffic in Semrush’s 2025 Channel-Mix Dataset
Semrush’s large-scale web traffic analysis reported that organic search represented 16.04% of measured traffic in its 2025 channel-mix dataset, while organic search traffic increased by 2.38% during the year.
Global traffic dataset — not UK-specific.
The Distribution of Organic Search Traffic
| Measurement | Finding |
|---|---|
| Pages receiving zero estimated Google traffic | 96.55% |
| Pages receiving any estimated Google traffic | 3.45% |
| Pages receiving 1–10 monthly visits | 1.94% |
| Approximate pages analysed | 14 billion |
| Pages with no referring domains examined | ~20 million |
| Backlink-free pages exceeding 1,000 monthly visits | 2,997 |
Publishing More Content Does Not Guarantee More Search Visibility
The scale of content production across the web can create a misleading assumption that publishing additional pages will automatically expand organic visibility. Ahrefs’ evidence shows the opposite: most pages in its enormous index generated no estimated Google search traffic.
There are several possible reasons. A page may target a subject with little search demand, fail to match search intent, compete against substantially stronger pages, lack sufficient internal or external authority, or simply provide no compelling reason for search systems to surface it ahead of existing alternatives.
Only 3.45% of the Analysed Pages Generated Any Estimated Google Traffic
The inverse of Ahrefs’ 96.55% zero-traffic measurement leaves just 3.45% of pages with some estimated Google organic traffic.
CGO Media Calculation: 100% − 96.55% = 3.45%.
Backlinks Matter, but Link Counts Are Not a Ranking Formula
The backlink evidence also requires careful interpretation. Higher-ranking pages frequently have stronger backlink profiles, but this does not mean that acquiring a predetermined number of links will produce a predetermined ranking.
Backlinko’s 11.8-million-result study found the number-one result had 3.8 times more backlinks on average than positions two through ten. It also found that referring-domain diversity was associated with stronger rankings.
Ahrefs’ separate analysis of 44,589 non-branded queries similarly found correlations between backlink-related metrics and ranking position. The researchers explicitly cautioned that correlation does not establish causation.
For organisations, the practical distinction is important. Links should be understood as external evidence of relevance, prominence and authority rather than as a simple numerical target.
Search Authority Is Built From Multiple Layers
Search Demand
Content needs an identifiable audience or information need if it is expected to generate search traffic.
Intent Alignment
The format and substance of the page need to satisfy what searchers are attempting to accomplish.
Content Depth
Useful coverage can improve the ability of a page to answer the subject comprehensively.
Internal Authority
Site architecture and internal links connect pages to broader organisational knowledge and authority.
External Authority
Relevant external links and citations can provide independent evidence that a resource is recognised elsewhere.
Search Performance
Impressions, rankings, clicks and conversions show whether content is actually producing measurable discovery.
Content Authority Is Expanding Beyond Google Rankings
The emergence of AI-mediated discovery adds another dimension to content authority. Search visibility still matters, but organisations increasingly need content that can also be retrieved, interpreted, attributed and potentially cited by generative systems.
This makes original research, clearly attributable evidence, expert authorship, strong entity relationships and independent corroboration potentially valuable beyond the conventional ranking environment.
The objective is therefore moving from producing pages solely to capture keywords toward building resources that strengthen an organisation’s wider body of searchable and machine-readable knowledge.
CGO Media Research Position
Content Volume Is Not Content Authority
The web already contains billions of pages that receive little or no measurable organic search traffic. Competitive advantage therefore comes less from publishing volume alone and more from producing resources that satisfy genuine demand, provide distinctive value and accumulate internal and external evidence of authority.
Demand → Relevance → Evidence → Content Quality → Internal Authority → External Authority → Search & AI Discovery
Sources & Measurement Notes
Ahrefs — Search Traffic Study: Used for Statistics 51–56. Ahrefs analysed approximately 14 billion pages and found that 96.55% received no estimated organic traffic from Google. The company notes that its traffic figures are estimates and that its Content Explorer database does not represent the entire web.
Backlinko / Ahrefs — Google Ranking Study: Used for Statistics 57–58. The study analysed 11.8 million Google search results and found that the number-one result had 3.8 times more backlinks on average than positions two through ten.
Ahrefs — Links With Traffic Study: Used for Statistic 59. The research analysed 44,589 non-branded keywords with monthly search volumes between 2,000 and 5,000 and examined the top ten ranking pages for each query.
Semrush — Traffic Channel Mix Study: Used for Statistic 60. Semrush’s global dataset reported organic search representing 16.04% of measured traffic during 2025 and increasing 2.38% during the year.
Correlation warning: Relationships between backlinks, authority metrics and ranking positions should not be interpreted as proof that an individual backlink metric directly causes higher rankings. Search performance is influenced by multiple interacting systems.
Geographic scope: Statistics 51–60 use international or global evidence because equivalent large-scale UK-only content and backlink datasets are not available. None of these measurements is presented as a UK-specific statistic.
Statistics 61–70
Ecommerce, Product Discovery & Commercial Search
Ecommerce is deeply embedded in UK consumer behaviour. More than one-quarter of Great Britain retail sales are now completed online, while major retail platforms reach tens of millions of UK adults every month.
Commercial discovery is therefore distributed across Google Search, Google Shopping, retailer websites, marketplaces, social platforms and increasingly AI-mediated recommendation environments. For ecommerce SEO, visibility increasingly depends on both traditional webpage optimisation and the quality, structure and authority of product information.
Statistic 61
27.5% of Great Britain Retail Sales Were Online in 2025
Office for National Statistics data shows that internet sales accounted for 27.5% of total retail sales in Great Britain during 2025.
Statistic 62
Online Retail Share Reached 29.5% in December 2025
The ONS annual time series shows that internet sales represented 29.5% of Great Britain retail sales in December 2025, illustrating the continuing importance of online purchasing during the peak retail period.
Statistic 63
27.3% of Great Britain Retail Sales Were Still Online in August 2026
The latest ONS series available for this research records internet sales at 27.3% of Great Britain retail sales in August 2026.
Statistic 64
Online Retail Share Has Increased More Than Eightfold Since 2007
Internet sales accounted for only 3.4% of Great Britain retail sales in 2007, compared with 27.5% in 2025.
CGO Media Calculation: 27.5 ÷ 3.4 = approximately 8.1 times the 2007 share.
Statistic 65
50.5% of UK Card Spending Was Online in September 2025
ONS analysis of aggregated UK card-payment data found that online transactions accounted for 50.5% of total card spending in September 2025.
Statistic 66
Online Card Spending Increased From 43.7% in 2019 to 50.5% in 2025
The online share of UK card spending increased from 43.7% in September 2019 to 50.5% in September 2025.
Increase: 6.8 percentage points.
Statistic 67
Amazon Reached 43.2 Million UK Online Adults
Ofcom measured Amazon’s UK adult audience at 43.2 million people in May 2025, equivalent to 88% of UK online adults. Visitors spent an average of two hours and 15 minutes using Amazon during the month.
Statistic 68
eBay Reached 30.7 Million UK Online Adults
eBay reached 30.7 million UK online adults in May 2025, representing 63% of the UK online adult population measured by Ofcom.
Statistic 69
Temu Reached 28.4 Million UK Adults — Up 8.3 Million in One Year
Temu’s UK online adult audience increased from 20.1 million in May 2024 to 28.4 million in May 2025, a year-on-year increase of 8.3 million people. Its reach stood at 58%.
Statistic 70
Vinted Reached 14.3 Million UK Adults and Averaged 2 Hours 42 Minutes Per Visitor
Vinted reached 14.3 million UK online adults in May 2025, equivalent to 29% reach. Ofcom measured average monthly usage at 2 hours 42 minutes per visitor, the highest average time among its ten leading retail services.
Leading UK Online Retail Services
| Retail Service | May 2025 Audience | UK Adult Reach | Avg. Monthly Time |
|---|---|---|---|
| Amazon | 43.2m | 88% | 2h 15m |
| eBay | 30.7m | 63% | 1h 18m |
| Temu | 28.4m | 58% | 1h 10m |
| Apple | 22.7m | 46% | 18m |
| Tesco | 19.4m | 39% | 22m |
| Argos | 18.0m | 37% | 10m |
| Vinted | 14.3m | 29% | 2h 42m |
| Shein | 13.9m | 28% | 1h 50m |
How Online Retail Has Changed
| Year | Internet Share of Great Britain Retail Sales |
|---|---|
| 2007 | 3.4% |
| 2010 | 7.3% |
| 2015 | 12.5% |
| 2019 | 19.2% |
| 2020 | 28.1% |
| 2021 | 30.7% |
| 2025 | 27.5% |
Online Retail Has Become Structural Rather Than Exceptional
The long-term ONS series demonstrates the scale of the structural change. Online sales represented just 3.4% of Great Britain retail sales in 2007. By 2019, before the pandemic, the proportion had already reached 19.2%.
The share then increased sharply to 28.1% in 2020 and peaked at 30.7% in 2021. Although the proportion subsequently declined from the exceptional pandemic period, it stabilised at 26.6% in 2022, 26.7% in 2023, 27.1% in 2024 and 27.5% in 2025.
Online Retail Share Is 8.1 Times Its 2007 Level
Great Britain’s annual online retail share increased from 3.4% in 2007 to 27.5% in 2025.
CGO Media Calculation: 27.5 ÷ 3.4 = approximately 8.1.
Product Discovery Is a Multi-Platform Search Problem
The Ofcom audience data shows why ecommerce visibility cannot be understood solely through Google rankings. Amazon alone reached 43.2 million UK online adults in May 2025, while eBay reached 30.7 million and Temu 28.4 million.
These platforms function as major commercial discovery environments in their own right. A consumer may discover a product through Google, compare it on Amazon, validate price elsewhere, read reviews, return through a branded search and eventually transact through another channel.
The implication for ecommerce SEO is that product discoverability increasingly depends on consistent product entities, accurate attributes, strong category architecture, reviews, merchant information and machine-readable data across multiple surfaces.
Commercial Search Depends on Product Information Quality
Product Identity
Clear names, brands, identifiers and variants help search systems understand individual products.
Attributes
Structured characteristics support matching between products and increasingly specific commercial queries.
Availability
Current stock and availability information affects whether a product remains commercially useful.
Price
Accurate pricing helps search and shopping environments compare commercial options.
Reviews
Customer evidence contributes to product and retailer validation during consideration.
Merchant Trust
Delivery, returns, reputation and merchant identity can influence the final retailer choice.
UK Ecommerce Also Operates Across Borders
ONS card-payment research shows that online commerce is not limited to domestic merchants. During the first nine months of 2025, an average of 3.8% of total UK household card spending was both online and with an international merchant.
The broader international spending ratio was 6.9% during the same period. This means that more than half of the measured international household card spend was occurring online.
For ecommerce organisations, search competition is therefore not necessarily confined to retailers headquartered in the UK. Search engines, marketplaces and recommendation systems can expose consumers to merchants operating across international borders.
CGO Media Research Position
Ecommerce SEO Is Becoming Product Discovery Optimisation
Commercial discovery increasingly occurs across search engines, shopping interfaces, marketplaces and AI-mediated recommendation environments. Retailers therefore need products that can be accurately understood, compared, validated and selected across multiple discovery systems.
Product Entity → Attribute Clarity → Search Eligibility → Comparison → Trust Evidence → Retailer Selection → Purchase
Sources & Measurement Notes
Office for National Statistics — Retail Sales Index Internet Sales: Used for Statistics 61–64. The ONS time series records internet sales as a percentage of total retail sales in Great Britain. Annual online share increased from 3.4% in 2007 to 27.5% in 2025 and stood at 27.3% in August 2026.
Office for National Statistics — Consumer Card Spending, E-commerce and Digital Trade Insights: Used for Statistics 65–66 and cross-border ecommerce context. Online spending represented 50.5% of total card spending in September 2025, compared with 43.7% in September 2019.
Ofcom — Online Nation 2025: Used for Statistics 67–70 and the retail-platform comparison table. Ofcom’s retail audience figures are based on Ipsos iris measurements of UK internet users aged 18 and over in May 2025.
Geographic distinction: ONS retail-sales statistics relate to Great Britain rather than the entire United Kingdom because the Retail Sales Index covers England, Scotland and Wales. Ofcom’s audience measurements relate to UK online adults.
Measurement distinction: Retail sales, card spending and online audience reach measure different behaviours and should not be combined as though they represent the same ecommerce metric. Together they illustrate the scale of online retail purchasing and commercial digital discovery.
Statistics 71–80
SEO Investment, ROI & Business Performance
SEO performance ultimately needs to connect search visibility with measurable organisational outcomes. Rankings, impressions and traffic can indicate whether visibility is increasing, but businesses invest in search because they expect that visibility to contribute to awareness, enquiries, leads, sales, customer acquisition or other commercial objectives.
Reliable SEO ROI benchmarking is difficult because organisations calculate return differently and attribution models vary substantially. The statistics below therefore focus on recent marketer-reported investment, ROI and business objectives rather than presenting unsupported universal claims about the monetary return generated by SEO.
Statistic 71
Website, Blog & SEO Was the Number-One ROI-Generating Marketing Channel
HubSpot’s 2026 marketing research identified website, blog and SEO as the number-one ROI-generating marketing channel reported by marketers.
International marketer survey evidence — not UK-specific.
Statistic 72
22.26% of Marketers Ranked Blog Posts Among Their Five Highest-ROI Content Formats
HubSpot’s State of Marketing research reported that 22.26% of marketers placed blog posts among the five content formats generating the highest ROI in 2025.
International marketer survey evidence.
Statistic 73
Small Businesses Were 23% More Likely Than Average to Report ROI From Blog Posts
HubSpot’s 2026 marketing statistics report that small businesses were 23% more likely than the survey average to report ROI from blog posts.
International marketer survey evidence.
Statistic 74
50% of Marketers With Blogs Reported Higher Blogging ROI Year on Year
HubSpot’s State of Blogging survey found that 50% of marketers working for businesses with blogs reported higher blogging ROI in 2024 than in 2023.
Survey of more than 500 marketers — international evidence.
Statistic 75
31% Reported Blogging ROI Was Approximately Unchanged
A further 31% of marketers in HubSpot’s survey reported that the ROI generated by blogging remained approximately the same between 2023 and 2024.
International marketer survey evidence.
Statistic 76
15% of Marketers Reported Lower Blogging ROI
Not every organisation reported improving returns. HubSpot found that 15% of marketers from businesses maintaining blogs experienced lower blogging ROI in 2024 compared with 2023.
International marketer survey evidence.
Statistic 77
45% Planned to Increase Their Blogging Budget
HubSpot found that 45% of marketers working for blog-maintaining businesses planned to increase their blogging budget in 2025 compared with 2024.
International marketer survey evidence.
Statistic 78
40% Planned to Maintain Their Existing Blogging Investment
Another 40% of surveyed marketers said their businesses intended to maintain blogging investment at approximately the same level year on year.
International marketer survey evidence.
Statistic 79
49% of Blog-Maintaining Businesses Used Content for Lead Generation
HubSpot found that 49% of businesses maintaining blogs identified lead generation as one of the reasons they publish content, connecting organic content investment directly with potential commercial acquisition.
International marketer survey evidence.
Statistic 80
46% Used Conversion Rate to Measure Blog Performance
HubSpot found that 46% of businesses maintaining blogs used conversion rate as a measure of blog success. This provides an important distinction between measuring content exposure and measuring whether that exposure contributes to action.
International marketer survey evidence.
How Marketers Reported Blogging ROI
| ROI Change | Marketers Reporting It |
|---|---|
| Higher ROI | 50% |
| Approximately the same | 31% |
| Lower ROI | 15% |
Planned Investment in Blogging
| Investment Direction | Share of Marketers |
|---|---|
| Increase investment | 45% |
| Maintain investment | 40% |
| Reduce investment | 13% |
Content Represents a Material Share of Marketing Investment
HubSpot’s research also demonstrates that blogging is not necessarily a marginal marketing expense. Among businesses maintaining blogs, 24% of marketers said less than 10% of the marketing budget was allocated to blogging.
A further 31% allocated between 11% and 20%, 25% allocated between 21% and 30%, and 18% reported allocating more than 30% of their marketing budget to blogging.
43% Allocated More Than One-Fifth of Marketing Budget to Blogging
Combining the two highest budget bands shows that 43% of surveyed marketers at blog-producing businesses allocated more than 20% of marketing budget to blogging.
CGO Media Calculation: 25% allocating 21–30% + 18% allocating more than 30% = 43%.
SEO ROI Should Be Measured Against Business Outcomes
SEO reporting frequently concentrates on rankings because rankings are relatively easy to monitor. However, a higher ranking is an intermediate outcome rather than a financial return.
The same applies to impressions and organic traffic. Both are useful indicators of discovery, but neither establishes whether SEO is generating commercially valuable activity.
For organisations measuring return, organic visibility should therefore be connected to enquiries, qualified leads, ecommerce revenue, customer acquisition, pipeline value or another outcome appropriate to the organisation.
From Search Visibility to Business Value
Visibility
Rankings, impressions, AI mentions and search-result exposure indicate discoverability.
Traffic
Organic sessions show how much visible demand is converted into website visits.
Engagement
On-site behaviour helps indicate whether the audience and content are appropriately aligned.
Conversion
Enquiries, registrations, purchases and other actions connect discovery with outcomes.
Revenue
Attributed revenue or pipeline provides a stronger commercial measurement than traffic alone.
Return
Revenue or value can then be compared with SEO investment to estimate financial return.
A Simple SEO ROI Framework
Where sufficiently reliable attribution is available, a simplified return calculation can be expressed as:
SEO ROI = ((Value Attributed to SEO − SEO Cost) ÷ SEO Cost) × 100
The difficult component is normally not the formula but attribution. Organic search can contribute earlier in a customer journey even when another channel receives the final conversion credit.
AI Search Makes Attribution More Complex
The measurement problem becomes more complex as search moves toward AI-generated answers. A user may encounter a brand inside a Google AI Overview, ChatGPT, Gemini or another AI interface without immediately visiting the organisation’s website.
That exposure can still influence later behaviour. The same person may subsequently conduct a branded search, visit directly, request information through another channel or purchase after further research.
SEO measurement in 2026 therefore increasingly requires organisations to distinguish website traffic from wider search visibility and to consider whether conventional last-click analytics capture the complete discovery journey.
CGO Media Research Position
SEO ROI Should Measure Business Value, Not Rankings in Isolation
Rankings are an input into visibility. Visibility can create traffic, citations, brand exposure and commercial opportunity. The meaningful return occurs when those outcomes contribute measurable value to the organisation.
Investment → Search Visibility → Qualified Discovery → Engagement → Conversion → Revenue / Value → ROI
Sources & Measurement Notes
HubSpot — Marketing Statistics & State of Marketing 2026: Used for Statistics 71–73. HubSpot reports website/blog/SEO as the number-one ROI-generating marketing channel according to marketers, with blog posts among the five highest-ROI content formats.
HubSpot — State of Blogging 2025: Used for Statistics 74–80 and the investment analysis. HubSpot surveyed more than 500 marketers across industries and company sizes.
ROI caution: These are marketer-reported survey results. They do not establish a universal monetary ROI for SEO or content marketing. Individual business performance varies according to sector, competition, investment level, attribution method, conversion performance and customer economics.
SEO versus blogging: Several statistics in this section measure blogging or website/blog/SEO collectively rather than SEO as an isolated activity. They are included because organic content is a major component of many SEO programmes, but the terms should not be treated as interchangeable.
Geographic scope: Statistics 71–80 use international marketer survey evidence. Comparable current UK-only SEO ROI datasets with transparent methodology were not identified at sufficient scale, so these measurements are not presented as UK-specific figures.
Statistics 81–90
AI Search, Google AI Overviews & Changing Search Behaviour
Artificial intelligence is changing both the interface and behaviour of online search. Traditional search remains dominant in the UK, but users are increasingly encountering generated answers directly inside search results while also adopting conversational AI services such as ChatGPT.
The result is not simply a new search engine competing with an old one. Search itself is becoming more generative, conversational and answer-oriented. This changes how organisations need to think about visibility, citations, website traffic and the measurement of search performance.
Statistic 81
Around 30% of UK Searches Now Show AI Overviews
Ofcom reported that approximately 30% of searches in the UK now display AI Overviews, demonstrating that generated answers have moved from an experimental search feature into a significant part of mainstream search behaviour.
Statistic 82
53% of UK Adults Say They Often See AI Search Summaries
More than half of UK adults — 53% — told Ofcom that they often encounter AI-generated summaries when using search services.
Statistic 83
ChatGPT Received 1.8 Billion UK Visits in Eight Months
Ofcom reported that ChatGPT generated 1.8 billion UK visits during the first eight months of 2025, demonstrating the scale at which conversational AI had already entered UK online behaviour.
Statistic 84
ChatGPT UK Visits Increased From 368 Million to 1.8 Billion
ChatGPT recorded 368 million UK visits during the first eight months of 2024 compared with 1.8 billion during the same period of 2025.
Ofcom measurement period: January–August 2024 versus January–August 2025.
Statistic 85
ChatGPT UK Visits Increased by Approximately 389%
The increase from 368 million to 1.8 billion visits represents approximately 389% year-on-year growth across the equivalent eight-month periods.
CGO Media Calculation: ((1.8bn − 368m) ÷ 368m) × 100 ≈ 389%.
Statistic 86
Google AI Overviews Reached More Than 2 Billion Monthly Users
Alphabet reported in July 2025 that Google AI Overviews had grown to more than 2 billion monthly users worldwide.
Global Google measurement — not UK-specific.
Statistic 87
AI Overviews Expanded to More Than 200 Countries and Territories
Google expanded AI Overviews to more than 200 countries and territories, turning generative search summaries into a global component of the Google Search experience.
Global Google product availability.
Statistic 88
AI Overviews Support More Than 40 Languages
Google reported that AI Overviews were available in more than 40 languages, extending generated search experiences across a broad international user base.
Global Google product availability.
Statistic 89
AI Mode Queries Are Nearly Three Times Longer Than Traditional Searches
Google reported in October 2025 that people using AI Mode were asking questions nearly three times longer than traditional search queries, indicating a shift towards more detailed and conversational search behaviour.
Google product usage evidence — global AI Mode context.
Statistic 90
Google Reported More Than 10% Usage Growth for Query Types Showing AI Overviews
Google reported that in major markets including the United States and India, AI Overviews were driving more than 10% growth in Google usage for the types of queries that display them.
Google-reported international evidence. This measurement is not UK-specific.
The Scale of AI Search in the UK
| Measurement | Finding |
|---|---|
| Searches showing AI Overviews | ~30% |
| Adults often seeing AI summaries | 53% |
| ChatGPT UK visits, Jan–Aug 2024 | 368m |
| ChatGPT UK visits, Jan–Aug 2025 | 1.8bn |
| Approximate year-on-year growth | 389% |
AI Search Is Already Part of Mainstream UK Search
The UK evidence indicates that AI-mediated search should no longer be treated as a future scenario. If approximately 30% of searches show AI Overviews and 53% of adults report encountering AI summaries often, generated answers are already part of routine search exposure.
The growth of ChatGPT adds a second dimension. Users are not only receiving AI-generated answers inside conventional search engines; they are also actively visiting dedicated conversational AI platforms.
ChatGPT UK Visits Grew Almost Fivefold
ChatGPT visits increased from 368 million to 1.8 billion across the first eight months of 2024 and 2025 respectively.
CGO Media Calculation: 1.8bn ÷ 368m ≈ 4.89 times the previous year’s volume.
Search Queries Are Becoming Longer and More Conversational
Generative search interfaces allow users to express information needs differently. Rather than compressing intent into a short sequence of keywords, users can ask complete questions, provide context, request comparisons and continue the interaction through follow-up queries.
Google’s AI Mode data illustrates the change. By October 2025, Google reported that AI Mode questions were nearly three times longer than traditional searches.
This has implications for SEO research. Keyword volumes remain useful, but they may represent a progressively smaller part of the full language people use when asking search and AI systems for information, comparisons and recommendations.
AI Answers Can Change What Happens After the Search
International behavioural research also indicates that generated answers can materially alter outbound clicking. Pew Research Center analysed 68,879 Google searches made by 900 US adults during March 2025.
| Behaviour | AI Summary Present | No AI Summary |
|---|---|---|
| Traditional search-result click | 8% | 15% |
| Session ended after search | 26% | 16% |
| AI-summary source click | 1% | Not applicable |
The Pew research is US-based and should not be interpreted as a direct measurement of UK behaviour. It does, however, provide evidence that the appearance of generated answers can change the relationship between search visibility and website traffic.
Complex Queries Are Particularly Important
Pew’s research also found substantial differences in AI-summary prevalence according to query structure. Only 8% of one- or two-word Google searches in its dataset produced an AI summary.
For searches containing ten words or more, the proportion increased to 53%. Searches beginning with question words such as who, what, when or why generated an AI summary 60% of the time.
This matters because many high-value research and commercial journeys involve precisely these kinds of detailed questions: comparisons, explanations, recommendations, suitability questions and multi-factor decisions.
Search Visibility Is Expanding Beyond the Ranked Link
Traditional Ranking
A webpage appears as a conventional ranked search result.
AI Overview
Information can be synthesised directly into Google’s generated search response.
AI Citation
A source can be referenced as supporting evidence within a generated answer.
Entity Mention
An organisation can be named or described without necessarily receiving a direct click.
Comparison
AI systems can compare organisations, products, services or approaches within a generated response.
Recommendation
Search systems can move beyond retrieval towards recommending options that fit the user’s scenario.
CGO Media Research Position
SEO Is Expanding From Ranking Optimisation to Search Ecosystem Visibility
Traditional rankings remain important, but they now exist alongside generated answers, AI citations, entity mentions, comparisons and recommendations. Organisations therefore need to understand not only whether they rank, but whether search and AI systems can retrieve, understand, trust and use their information.
Search Visibility → Retrieval → Understanding → Citation → Comparison → Recommendation → Qualified Discovery
Sources & Measurement Notes
Ofcom — Online Nation 2025: Used for Statistics 81–85. Ofcom reports that around 30% of UK searches show AI Overviews, 53% of adults often see AI-generated summaries and ChatGPT received 1.8 billion UK visits during the first eight months of 2025 compared with 368 million during the equivalent period of 2024.
Google / Alphabet: Used for Statistics 86–90. Alphabet reported more than 2 billion monthly AI Overview users in July 2025. Google has also reported availability across more than 200 countries and territories and more than 40 languages, substantially longer AI Mode queries and increased search usage for query categories displaying AI Overviews.
Pew Research Center: Used for additional click-behaviour and query-complexity analysis. Pew analysed 68,879 Google searches from 900 US adults. The research found lower traditional-result clicking when an AI summary appeared and higher AI-summary prevalence for longer and question-based searches.
Geographic scope: Statistics 81–85 are UK-specific. Statistics 86–90 use Google-reported global or international evidence and are labelled accordingly. Pew’s click-behaviour research is US-based and is used only as international contextual evidence.
Measurement caution: Search visits, monthly users, AI Overview prevalence and survey-reported exposure measure different aspects of AI-search adoption. They should not be combined as though they represent a single market-share metric.
SEO, AI Discovery & the 2026 Search Ecosystem
The final ten statistics illustrate how search discovery is expanding beyond conventional rankings and website clicks. Consumers are increasingly using AI systems for recommendations, while Google is integrating generative answers, conversational interaction, longer queries and multimodal search directly into the search experience.
91. 71% of Consumers Used Google for Local Business Reviews and Recommendations
71% of consumers surveyed by BrightLocal said they used Google when researching local businesses through reviews and recommendations. Google remained the leading individual platform in the survey, although its reported usage declined from 83% in the previous year’s study.
Source: BrightLocal, Local Consumer Review Survey 2026.
Geography: United States.
Sample: 1,002 US adults.
92. 45% of Consumers Used Generative AI Tools for Local Business Recommendations
45% of consumers surveyed reported using ChatGPT or other generative AI tools for local business recommendations, compared with 6% in the previous year’s research. Generative AI became the third most-used source for local business recommendations in the study.
Source: BrightLocal, Local Consumer Review Survey 2026.
Geography: United States.
Sample: 1,002 US adults.
93. 18% of Google Searches in a Pew Study Produced an AI Summary
Pew Research Center found that 18% of the Google searches examined in its study generated an AI summary alongside conventional search results. The analysis covered 68,879 unique Google searches, of which 12,593 produced an AI-generated summary.
Source: Pew Research Center.
Geography: United States.
Measurement period: March 2025 browsing data.
94. 88% of Google AI Summaries Cited Three or More Sources
88% of the Google AI summaries analysed by Pew Research Center cited at least three sources. Only 1% cited a single source.
Source: Pew Research Center.
Geography: United States.
95. The Median Google AI Summary Contained 67 Words
The median AI-generated Google summary in Pew’s study contained 67 words. The shortest observed summary contained seven words, while the longest contained 369 words.
Source: Pew Research Center.
Geography: United States.
96. 60% of Question-Led Searches Produced an AI Summary
Searches beginning with question words such as who, what, when or why produced an AI summary in 60% of the searches examined by Pew Research Center.
Source: Pew Research Center.
Geography: United States.
97. 53% of Searches With 10 or More Words Produced an AI Summary
53% of Google searches containing ten words or more generated an AI summary in Pew’s research. By comparison, only 8% of searches containing one or two words generated an AI summary.
Source: Pew Research Center.
Geography: United States.
98. AI Mode Queries Are Around Three Times Longer Than Traditional Searches
Alphabet reported that queries made through Google’s AI Mode were approximately three times longer than traditional search
queries, reflecting the more conversational and complex nature of AI-assisted search behaviour.
Source: Alphabet / Google Search reporting.
Geography: Platform-level reporting.
99. Nearly One in Six Google AI Mode Queries Used Voice or Images
Alphabet reported that nearly one in six AI Mode queries were non-text searches using voice or images. The measurement demonstrates how search input is expanding beyond the conventional typed keyword query.
Source: Alphabet, Q4 2025 Earnings Call, reported 2026.
Geography: Platform-level reporting.
100. Google Shipped More Than 250 AI Mode and AI Overview Product Launches in One Quarter
Alphabet reported that Google shipped more than 250 product launches across AI Mode and AI Overviews during the fourth
quarter of 2025 alone. The volume illustrates the speed at which AI-mediated search functionality is being developed and deployed.
Source: Alphabet, Q4 2025 Earnings Call, reported 2026.
Geography: Platform-level reporting.
Search Visibility Is Expanding Beyond Rankings
These measurements demonstrate that search discovery is increasingly distributed across conventional search results, AI-generated summaries, conversational search experiences, local recommendations and multimodal interfaces.
For organisations, this expands the definition of SEO performance. Visibility can increasingly occur when an organisation is retrieved, cited, compared or recommended by a search or AI system—even when the interaction does not immediately generate a conventional organic click.
Search Visibility → Retrieval → Understanding → Citation → Comparison →
Recommendation → Qualified Discovery
Research note:
Statistics 91–92 are drawn from a representative panel of 1,002 US adults and are included as international evidence of changing local discovery
behaviour. Statistics 93–97 are based on US Google search behaviour analysed by Pew Research Center. Statistics 98–100 use Google and Alphabet
platform reporting. These measurements should not be interpreted as UK-specific behaviour unless explicitly stated.
CGO Media Analysis
What the UK SEO Statistics Tell Us About Search in 2026
The 100 statistics assembled in this research point towards a search market undergoing structural change rather than simple decline or replacement. Traditional search remains deeply embedded in UK digital behaviour, Google continues to dominate search-engine usage, mobile devices remain central to online activity and organic visibility continues to connect organisations with significant levels of consumer and commercial demand.
At the same time, the mechanisms through which people discover and evaluate information are becoming more diverse. Google AI Overviews, conversational AI platforms, Maps, marketplaces, reviews and multimodal interfaces increasingly sit alongside conventional organic search results.
The strategic implication is not that organisations should abandon SEO. It is that the definition of SEO increasingly needs to expand beyond rankings and website clicks towards a broader model of search visibility, machine understanding, authority, citation and recommendation.
Key Finding 1
Google Remains the Central Search Platform in the UK
The clearest finding from the market data is that Google continues to dominate UK search. StatCounter measured Google’s all-platform UK search-engine share at 91.75% in August 2026, while its mobile share reached approximately 97.6%.
Ofcom separately reports that Google Search reaches 82% of UK online adults and handles approximately three billion UK searches every month.
AI search therefore needs to be understood alongside Google rather than simply as a replacement for it. One of the largest AI-search changes is occurring inside Google itself through AI Overviews and AI Mode.
Key Finding 2
Mobile Is the Primary Search and Discovery Environment
UK internet behaviour is strongly mobile. Ofcom found that smartphones accounted for 75% of men’s personal online time and 79% of women’s personal online time.
Google’s dominance becomes even greater within mobile search, where its UK share approaches 98%. Google Maps also reached 78% of UK online adults in May 2025.
For SEO, mobile performance should consequently be treated as the primary search experience rather than a secondary adaptation of a desktop website.
Key Finding 3
A Ranking No Longer Guarantees the Same Click Opportunity
International click-behaviour evidence indicates that generated search answers can alter the relationship between ranking and website traffic.
Advanced Web Ranking measured a position-one CTR of 20.02% across its analysed US desktop searches in July 2026, compared with 9.69% when an AI Overview was present.
Pew Research Center similarly found that users clicked a traditional Google result on 8% of visits when an AI summary appeared compared with 15% when one did not.
The implication is that ranking performance and traffic performance can increasingly diverge. Visibility can remain high even while the probability of an outbound click changes.
Key Finding 4
Most Published Pages Generate Little or No Search Traffic
Ahrefs’ analysis of approximately 14 billion pages found that 96.55% received no estimated organic traffic from Google.
The inverse of that measurement means only 3.45% of pages in the analysed dataset generated any estimated Google traffic.
This challenges content strategies based primarily on publishing volume. The ability to produce more pages does not by itself create search visibility. Demand, relevance, differentiation, authority, technical accessibility and competitive strength remain important.
Key Finding 5
Authority Remains Important, but It Cannot Be Reduced to a Single Metric
Large-scale ranking studies continue to find relationships between backlinks, referring domains and stronger-ranking pages. Backlinko’s analysis of 11.8 million Google results found that the number-one result had 3.8 times more backlinks on average than positions two through ten.
These findings should not be interpreted as a formula in which a predetermined number of links produces a predetermined ranking. Correlation does not establish causation, and modern search authority involves considerably more than backlink counts.
Authority increasingly includes content quality, expertise, entity clarity, independent corroboration, reputation, topical relationships and the ability of search systems to connect an organisation with the subject being researched.
Key Finding 6
Local Search Is a Trust and Validation Environment
Google Maps reached 78% of UK online adults in May 2025, compared with 69% two years earlier. Average monthly use also increased from 139 minutes in May 2024 to 153 minutes in May 2025.
Reviews add another layer to local discovery. UK Competition and Markets Authority evidence indicates that reviews influence substantial levels of consumer research and spending.
Local SEO should therefore connect discoverability with accurate business information, reputation, review evidence and the information consumers need to validate a business before contacting, visiting or purchasing.
Key Finding 7
Commercial Discovery Extends Far Beyond a Conventional Google Result
Online retail accounted for 27.5% of Great Britain retail sales during 2025, compared with just 3.4% in 2007.
Ofcom also measured enormous audiences for dedicated retail platforms. Amazon reached 43.2 million UK online adults in May 2025, eBay reached 30.7 million and Temu reached 28.4 million.
Retail discovery is consequently distributed across search engines, marketplaces, retailer sites, reviews, shopping interfaces, social platforms and AI systems. Ecommerce SEO increasingly needs to optimise the product entity and its supporting information, not merely the webpage containing it.
Key Finding 8
AI Search Is Already a Material Part of UK Discovery
Ofcom reports that approximately 30% of UK searches show AI Overviews and that 53% of adults say they often encounter AI-generated summaries.
ChatGPT provides evidence of the parallel growth of dedicated AI services. UK visits increased from 368 million during the first eight months of 2024 to 1.8 billion during the equivalent period of 2025.
AI search should therefore no longer be treated solely as an emerging technology question. It is becoming part of the current discovery environment that organisations need to measure.
Key Finding 9
Complex Queries Are Becoming More Important
AI interfaces allow people to express considerably more context than conventional short keyword searches. Google has reported that AI Mode queries are nearly three times longer than traditional search queries.
Pew’s US behavioural study found that 53% of searches containing ten words or more generated an AI summary, compared with only 8% of searches containing one or two words.
Keyword research therefore remains useful, but organisations increasingly need to understand questions, scenarios, comparisons, constraints and decision criteria that cannot always be represented by a short keyword phrase.
Key Finding 10
Citation Is Emerging as a Distinct Search Visibility Metric
Pew found that 88% of the Google AI summaries in its study cited three or more sources. This creates a visibility layer that is different from conventional ranking.
An organisation can potentially contribute evidence to a generated response even when the user’s experience is centred on the answer rather than the underlying webpage.
Citation visibility should not replace ranking, traffic or conversion measurement. It should be considered an additional dimension of search performance as generated answers become more common.
Ten Findings From the 100 Statistics
| # | Finding | SEO Implication |
|---|---|---|
| 1 | Google remains dominant | Google SEO remains fundamental. |
| 2 | Mobile dominates online behaviour | Mobile performance must be treated as primary. |
| 3 | AI answers can reduce outbound clicking | Rankings and clicks should be measured separately. |
| 4 | Most published pages receive little search traffic | Prioritise useful, differentiated content over volume. |
| 5 | Authority remains important | Build external and internal evidence of expertise. |
| 6 | Local discovery depends on trust | Maps, reviews and business information matter alongside rankings. |
| 7 | Commercial discovery is multi-platform | Optimise product information across discovery environments. |
| 8 | AI search is already mainstream enough to measure | Add AI visibility to search reporting. |
| 9 | Queries are becoming more complex | Research scenarios and questions, not only keywords. |
| 10 | Citation is becoming another visibility layer | Measure source inclusion alongside rankings and traffic. |
From Ranking SEO to Search Ecosystem Visibility
The evidence can be understood as an expansion of the SEO measurement model. Each stage remains relevant, but the number of ways an organisation can become visible is increasing.
Traditional SEO
Ranking & Traffic
Crawlability, indexing, rankings, impressions, CTR, organic sessions and conversions remain essential measurements.
Expanded Search
SERP & Platform Visibility
Maps, shopping, marketplaces, rich results and other search surfaces extend discovery beyond conventional organic listings.
AI-Mediated Search
Citation & Recommendation
Generated answers introduce retrieval, source selection, citation, comparison and recommendation as additional visibility outcomes.
What Organisations Should Measure in 2026
A modern search-performance framework should therefore combine conventional SEO metrics with emerging discovery indicators rather than replacing one measurement system with another.
| Measurement Layer | Example Metrics | What It Measures |
|---|---|---|
| Technical Visibility | Indexation, crawlability, Core Web Vitals | Whether content can be accessed and processed. |
| Organic Visibility | Rankings, impressions, SERP visibility | Whether the organisation appears for relevant demand. |
| Traffic | Clicks, organic sessions, landing-page visits | Whether visibility produces website visits. |
| Local Visibility | Maps visibility, reviews, local actions | Local discovery and validation. |
| Commercial Visibility | Product visibility, category reach, merchant exposure | Commercial and product discovery. |
| AI Visibility | Mentions, citations, source inclusion | Whether AI systems retrieve or reference the organisation. |
| Recommendation Visibility | Comparison inclusion, recommendation frequency | Whether the organisation enters AI-assisted consideration. |
| Business Performance | Leads, revenue, pipeline, acquisition, ROI | Whether discovery creates organisational value. |
Important Research Distinction
AI Visibility Does Not Make Traditional SEO Obsolete
The evidence in this research does not support the conclusion that Google Search, organic rankings or website traffic have ceased to matter. Google remains overwhelmingly dominant in UK search and continues to process billions of searches.
What is changing is the number of possible discovery outcomes. A search can now result in a conventional click, a Maps interaction, an ecommerce comparison, an AI-generated answer, a citation, a brand mention or a recommendation. SEO therefore needs to account for more outcomes rather than fewer.
CGO Media 2026 Search Visibility Model
From Being Indexed to Being Selected
Traditional SEO concentrated heavily on whether a page could be crawled, indexed and ranked. Those requirements remain fundamental, but AI-mediated discovery adds further stages. Search systems increasingly need to understand the organisation, identify relevant evidence, assess authority and decide whether that evidence should be surfaced, cited or used in a recommendation.
Accessible → Understood → Relevant → Authoritative → Retrieved → Ranked → Cited → Compared → Recommended
For organisations operating in competitive UK markets, the objective is therefore increasingly to build sufficient technical, informational and external authority to remain visible throughout this entire discovery chain.
Research Methodology
How the UK SEO Statistics 2026 Research Was Compiled
This research was compiled by the CGO Media Research Team to provide a structured quantitative view of the UK search environment in 2026. The dataset brings together 100 statistics covering search-engine usage, internet behaviour, organic search, mobile performance, local discovery, content and authority, ecommerce, marketing performance and AI-mediated search.
The research follows a UK-first approach. Where sufficiently current and methodologically transparent UK evidence was available, it was prioritised. International evidence was included where it provided relevant measurement of search behaviour or technology for which an equivalent current UK dataset was not identified.
International measurements are identified as such and should not be interpreted as direct estimates of UK behaviour.
Research Principles
Quantitative Evidence
Each numbered statistic is intended to contain a measurable percentage, volume, ratio, change, time measurement or other quantitative finding.
UK-First Evidence
UK-specific evidence is prioritised where credible, current and sufficiently transparent data is available.
Source Transparency
Statistics are attributed to the organisation, dataset or research publisher from which the measurement was obtained.
Geographic Labelling
International or US-specific evidence is identified so that it is not presented as though it directly measures UK users.
Measurement Context
Where relevant, measurement periods, sample sizes, platforms and methodological differences are included alongside the statistic.
Calculation Disclosure
Figures calculated by CGO Media from published source measurements are identified separately from directly reported statistics.
Source Selection
Sources were selected according to relevance, methodological transparency, recency and the degree to which they provided direct quantitative evidence for the subject being measured.
| Source Type | Examples Used | Primary Purpose |
|---|---|---|
| UK Regulators & Official Data | Ofcom, ONS, Competition and Markets Authority | UK internet behaviour, search usage, retail and consumer evidence. |
| Platform Data | Google, Alphabet | AI Overview reach, AI Mode behaviour and search-product development. |
| Market Measurement | StatCounter, DataReportal | Search-engine market share and UK internet adoption. |
| Independent Research | Pew Research Center | Observed search behaviour and AI-summary interaction. |
| Search Industry Datasets | Ahrefs, Advanced Web Ranking and other cited datasets | Organic traffic, CTR, backlinks and search-performance measurements. |
| Marketing Research | HubSpot and other identified surveys | Marketing investment, content performance and reported ROI. |
What Counts as a Statistic in This Research?
For the purposes of this study, a numbered statistic must contain a quantitative measurement. General SEO principles, recommendations and observations are not counted as statistics unless they are supported by a measurable dataset.
Included
Quantitative Measurements
Market shares, percentages, audience reach, search volumes, CTR measurements, traffic volumes, ratios, growth rates, sample measurements, performance metrics and calculated differences based on published data.
Not Counted as Statistics
Qualitative SEO Statements
Statements such as “technical SEO is important”, “backlinks can support authority”, “XML sitemaps aid discovery” or “SEO is a long-term marketing channel” are observations or guidance, not statistics.
CGO Media Calculations
A small number of measurements in the research are calculations derived from source data rather than figures directly published by the source organisation.
These calculations are explicitly labelled as CGO Media calculations so that readers can distinguish the underlying source measurement from the interpretation or arithmetic applied to it.
Example: Indicative UK AI Overview Search Volume
Ofcom reports approximately 3 billion monthly UK Google searches and states that around 30% of searches show AI Overviews.
3 billion × 30% ≈ 900 million
The resulting 900-million figure is an indicative CGO Media calculation. It is not presented as a directly measured Ofcom statistic because the underlying inputs are rounded and may have different measurement bases.
Research Limitations
How the Statistics Should Be Interpreted
No single dataset provides a complete measurement of the UK SEO and AI-search ecosystem. The statistics in this research originate from multiple sources using different methodologies, populations, technologies and measurement periods. The findings should therefore be interpreted within the context in which each measurement was produced.
1. Not Every Statistic Is UK-Specific
UK evidence was prioritised, but several areas — particularly AI click behaviour, ranking datasets, backlink analysis and some marketing-performance measurements — required international or US evidence because equivalent current UK datasets were not available with sufficient scale or methodological detail.
2. Search Data Changes Rapidly
Search-engine market share, AI Overview prevalence, AI-platform usage and search-interface behaviour can change materially over relatively short periods. Statistics represent the measurement period stated by the source rather than a permanent characteristic of search.
3. Different Sources Measure Different Things
Market share, audience reach, website visits, search volume, survey responses and clickstream behaviour are distinct measurements. A platform can have high audience reach without holding the same percentage of search activity, while visit counts should not be interpreted as equivalent to unique users.
4. Correlation Does Not Establish Causation
Ranking studies can identify relationships between characteristics such as backlinks and ranking positions. They do not prove that changing one characteristic in isolation will cause a particular ranking outcome.
5. SEO ROI Is Not Universal
The financial return generated by SEO depends on sector, margins, competition, conversion rates, customer value, implementation cost and attribution methodology. Survey-reported marketing ROI should not be converted into a universal expected return for an individual organisation.
6. AI Search Measurement Is Still Developing
AI-search measurement does not yet have a universally accepted equivalent of traditional ranking, impression and click reporting. Different studies may measure AI Overviews, AI citations, platform visits, generated answers or AI referrals differently.
7. AI Citations and AI Referrals Are Different Measurements
A website can be cited or used as a source within an AI-generated answer without receiving a website visit. Citation visibility, referral traffic and recommendation visibility should therefore be measured separately.
8. Search Results Are Query-Dependent
CTR, AI Overview appearance, SERP features and user behaviour can vary substantially according to query type, device, geography, intent and search-result composition. Aggregate measurements should not be assumed to apply equally to every keyword or sector.
9. Survey Evidence Reflects Reported Behaviour
Survey responses measure what participants report, which is not always identical to directly observed behaviour. Where possible, this research distinguishes survey evidence from behavioural, clickstream or platform measurements.
10. 2026 Does Not Mean Every Measurement Was Collected in 2026
The title refers to the 2026 research edition. Some of the most recent credible datasets available were collected or published during 2025. The relevant measurement period should therefore be considered when interpreting each statistic.
How CGO Media Interprets Statistical Evidence
A statistic becomes useful when the measurement is considered alongside its source, methodology and context. CGO Media therefore uses the following research sequence:
Measurement → Source → Methodology → Geography → Time Period → Context → Interpretation → Search Implication
Research Updates
The search environment changes continuously. CGO Media may update this research when new official datasets, platform measurements, market-share figures or sufficiently robust independent studies become available.
Where an updated measurement supersedes an older figure, the newer research edition may replace or revise the relevant statistic rather than preserving outdated data simply to maintain historical continuity.
CGO Media Research Methodology
Further information about CGO Media’s approach to research, evidence selection, interpretation and publication is available in the Research Methodology.
CGO Media Research Standard
Statistics Require Context
Large numbers can appear authoritative while still being misleading if their geography, methodology, age or measurement basis is unclear. The purpose of this research is therefore not simply to collect SEO statistics, but to place quantitative evidence within sufficient context for readers to understand what each measurement can — and cannot — demonstrate.
Measured Data → Source Context → Methodological Limits → Interpretation → Search Implication
References & Sources
Sources Used in UK SEO Statistics 2026
The UK SEO Statistics 2026 research draws on official UK datasets, regulatory research, platform reporting, independent behavioural studies and large-scale search-industry datasets.
Sources are listed below by research area. Readers should refer to the original publisher for the complete methodology, sample definition, measurement period and subsequent revisions to individual datasets.
Ofcom — Online Nation 2025
Ofcom’s Online Nation research provides some of the most important UK-specific evidence used in this study, including internet behaviour, Google Search reach, Google Maps usage, retail-platform audiences and the adoption of AI-mediated search.
Measurements used from Ofcom include Google Search usage among UK online adults, approximately three billion monthly UK Google searches, AI Overview exposure, ChatGPT UK visits and online audience measurements for major retail services.
Office for National Statistics — Retail Sales
ONS Retail Sales Index data was used to measure the long-term growth of online retail in Great Britain, including internet sales as a percentage of total retail sales.
The series provides historical context extending back to 2007 and enables comparison between pre-pandemic, pandemic and post-pandemic ecommerce behaviour.
Office for National Statistics — Consumer Card Spending
ONS analysis of aggregated card-payment data was used to examine online spending behaviour, including the proportion of UK card expenditure taking place online and changes compared with pre-pandemic spending.
Office for National Statistics — Economic Activity & Spending Indicators
StatCounter Global Stats
StatCounter was used for UK search-engine market-share measurements across all platforms and mobile devices.
These measurements provide the basis for comparing Google, Bing, Yahoo, DuckDuckGo, Ecosia and other search engines within the UK market.
DataReportal — Digital 2026: United Kingdom
DataReportal was used for current UK internet adoption measurements, including total internet users and internet penetration.
Google Chrome UX Report
Chrome UX Report data was used for Core Web Vitals measurements, including the proportion of measured origins achieving good Largest Contentful Paint, Interaction to Next Paint and Cumulative Layout Shift performance.
Competition and Markets Authority
UK Competition and Markets Authority evidence was used for the role of online reviews in consumer decision-making and the economic significance of review-influenced spending.
CMA material also provides regulatory context around fake reviews and business responsibilities under UK consumer-protection rules.
BrightLocal — Local Consumer Review Survey
BrightLocal’s consumer research was used as international contextual evidence for review-reading behaviour, review recency, review volume and the effect of positive and negative reviews on business consideration.
The cited consumer survey is US-based and is not presented as a direct measurement of UK consumer behaviour.
Ahrefs — Search Traffic & Backlink Research
Ahrefs datasets were used to examine the distribution of organic search traffic across webpages and the relationship between referring domains, backlinks and search visibility.
These datasets provide large-scale international search evidence and should not be interpreted as UK-only measurements.
Advanced Web Ranking — Google CTR Research
Advanced Web Ranking data was used for click-through-rate measurements and analysis of the difference in organic click behaviour when AI Overviews are present.
The referenced measurements use US Google search-result data and are included as international behavioural context.
Pew Research Center — Google AI Summary Behaviour
Pew Research Center’s behavioural study was used to examine how Google users interact with search results when an AI-generated summary appears.
The study analysed 68,879 Google searches associated with 900 US adults during March 2025 and provides measurements covering traditional-result clicks, AI-summary source clicks, session endings, query length and source citation.
Google & Alphabet — AI Search Reporting
Google and Alphabet reporting was used for the scale and development of AI Overviews and AI Mode, including monthly user reach, international availability, query behaviour, multimodal search and product development.
Platform-reported measurements are identified separately from independent behavioural research because the measurement methodology and underlying proprietary data are controlled by the platform.
Backlinko — Google Search Ranking Study
Backlinko’s analysis, using Ahrefs data, was used for large-scale measurements concerning backlinks and Google ranking positions. The study analysed 11.8 million Google search results.
The findings represent correlation within the analysed dataset and should not be interpreted as proof that backlink quantity independently causes rankings.
HubSpot — State of Marketing & Blogging Research
HubSpot research was used for marketer-reported measurements concerning website, SEO and blogging ROI, content investment, lead-generation objectives and performance measurement.
These figures represent survey responses and are not presented as a universal financial return that individual organisations should expect from SEO.
Semrush — Digital Traffic Research
Semrush research was used as supporting international evidence concerning the contribution of organic search to measured website traffic and changes in channel distribution.
Source Classification
| Source | Type | Primary Geography |
|---|---|---|
| Ofcom | UK regulator / research | UK |
| Office for National Statistics | Official statistics | UK / Great Britain |
| Competition and Markets Authority | UK regulator | UK |
| StatCounter | Market measurement | UK dataset used |
| DataReportal | Digital market research | UK dataset used |
| Google / Alphabet | Platform data | Global / international |
| Pew Research Center | Independent research | US |
| BrightLocal | Consumer survey | US |
| Ahrefs / Backlinko | Search dataset | International |
| Advanced Web Ranking | Search CTR dataset | US dataset used |
| HubSpot | Marketing survey | International |
Using This Research
Citation & Attribution
Journalists, researchers, businesses and other publishers may reference findings from this research. Where a statistic originates from an external dataset, the original source should remain identifiable.
Analysis, calculations and interpretation produced specifically for this page should be attributed to the CGO Media Research Team and linked to the original UK SEO Statistics 2026 research page.
Research Note
Primary Evidence Takes Priority
Where an original regulator, government dataset, platform report or research study is available, readers should consult that primary material rather than relying solely on secondary articles reproducing the statistic.
Original Dataset → Methodology → Measurement → Context → Interpretation
Conclusion
What UK SEO Looks Like in 2026
The 100 statistics examined in this research show that search remains one of the most important mechanisms through which people in the UK discover information, organisations, products, services and places. What is changing is not the underlying need for discovery, but the systems and interfaces through which that discovery takes place.
Google remains at the centre of the UK search market. Its search-engine share remains above 90%, Google Search reaches a large majority of UK online adults and billions of searches continue to take place every month. Mobile devices dominate much of the online experience, while Google Maps, ecommerce platforms and reviews play substantial roles in local and commercial discovery.
At the same time, AI is changing the presentation of search results. AI Overviews can answer questions directly within Google, conversational systems allow users to express longer and more complex requirements, and generated answers can synthesise information from multiple sources before a user decides whether to visit a website.
The resulting search environment is therefore broader than the traditional model of keyword, ranking and click. Those measurements remain important, but they increasingly sit alongside entity understanding, source retrieval, citation visibility, comparison visibility and AI-assisted recommendation.
Central Finding
SEO Is Expanding, Not Disappearing
The evidence does not support a simple conclusion that AI search is replacing SEO. Search engines continue to operate at enormous scale, while many AI-search experiences are being introduced directly into existing search environments.
The more significant change is that organisations now need to optimise for a larger number of discovery outcomes.
Traditional SEO Foundations Still Matter
The emergence of AI search does not remove the technical and informational foundations on which digital discovery depends. Websites still need to be accessible, crawlable, indexable, understandable and useful.
Content still needs to address genuine demand. Internal architecture still needs to establish relationships between information. External references and reputation still contribute evidence of authority. Mobile performance still shapes user experience. Local organisations still need accurate business information and credible reviews.
These are not legacy SEO activities. They form part of the information infrastructure through which both conventional search engines and emerging AI systems can discover and interpret organisations.
What Is Changing
Search Queries
Users can express longer questions, scenarios, comparisons and constraints rather than relying entirely on short keyword phrases.
Search Results
Generated answers can appear before or alongside conventional organic listings and may resolve part of the user’s information need directly.
Source Selection
Search and AI systems can retrieve and synthesise information from multiple sources to construct a response.
User Interaction
Discovery can continue conversationally without requiring the user to begin a completely new search.
Search Inputs
Voice, images and other multimodal inputs are expanding the ways in which users communicate search intent.
Visibility Measurement
Rankings and traffic increasingly need to be considered alongside citations, mentions, source inclusion and recommendation visibility.
The Implication for UK Organisations
For UK organisations, the strategic objective should not be to choose between traditional SEO and AI-search optimisation. The underlying challenge is to build sufficient digital authority to remain visible across both.
An organisation may need to rank in Google, appear in Maps, surface within shopping or marketplace environments, be understood as an entity, provide evidence that can be retrieved for generated answers and establish enough external corroboration to be considered credible during comparison or recommendation.
These outcomes are interconnected. Strong technical architecture improves accessibility. Clear entities improve machine understanding. High-quality content provides evidence. Independent references strengthen authority. Consistent brand and organisational signals help search systems connect information from different sources.
From Search Rankings to Search Ecosystem Visibility
| Traditional Measurement | Expanded 2026 Measurement |
|---|---|
| Keyword rankings | Search visibility across queries, topics and scenarios |
| Organic impressions | Search, Maps, product and AI visibility |
| Organic CTR | Click opportunity across changing SERP formats |
| Website traffic | Traffic plus zero-click and AI-mediated visibility |
| Backlinks | Broader authority, corroboration and source evidence |
| Brand searches | Brand and entity recognition across discovery systems |
| Ranking position | Ranking + retrieval + citation + recommendation |
| Organic conversions | Business outcomes influenced by the wider discovery journey |
The Next Stage of Search
The direction of search suggests that organisations will increasingly compete not only for positions in a list of webpages, but for inclusion within machine-generated research and decision environments.
This does not mean every search will become conversational or every decision will be made by an AI assistant. Different discovery behaviours are likely to coexist. Conventional search, local search, ecommerce platforms, social discovery, AI-generated answers and direct website navigation can all contribute to the same customer or research journey.
The organisations best positioned for this environment will be those whose information can remain accessible, understandable, authoritative and useful regardless of which discovery interface sits between the organisation and the user.
CGO Media Search Ecosystem Model
The Search Journey Is Becoming a Machine-Mediated Discovery Journey
Access
→
Understanding
→
Relevance
→
Authority
→
Retrieval
→
Visibility
→
Citation
→
Comparison
→
Recommendation
SEO increasingly influences multiple stages of this journey. The objective is not simply to rank a webpage, but to make an organisation sufficiently accessible, understandable and authoritative to remain eligible for discovery wherever search takes place.
Final Takeaway
The Objective Is No Longer Just to Be Found
Being indexed creates eligibility. Ranking creates visibility. Traffic creates an opportunity for direct interaction.
The emerging search environment adds further requirements: being understood, being trusted, being retrieved as evidence, being cited and being considered when a search or AI system helps a user compare possible answers, organisations, products or services.
UK SEO Statistics 2026
Research, analysis and interpretation by the CGO Media Research Team
CGO Media · SEO, GEO & AI Search Research · cgomedia.com