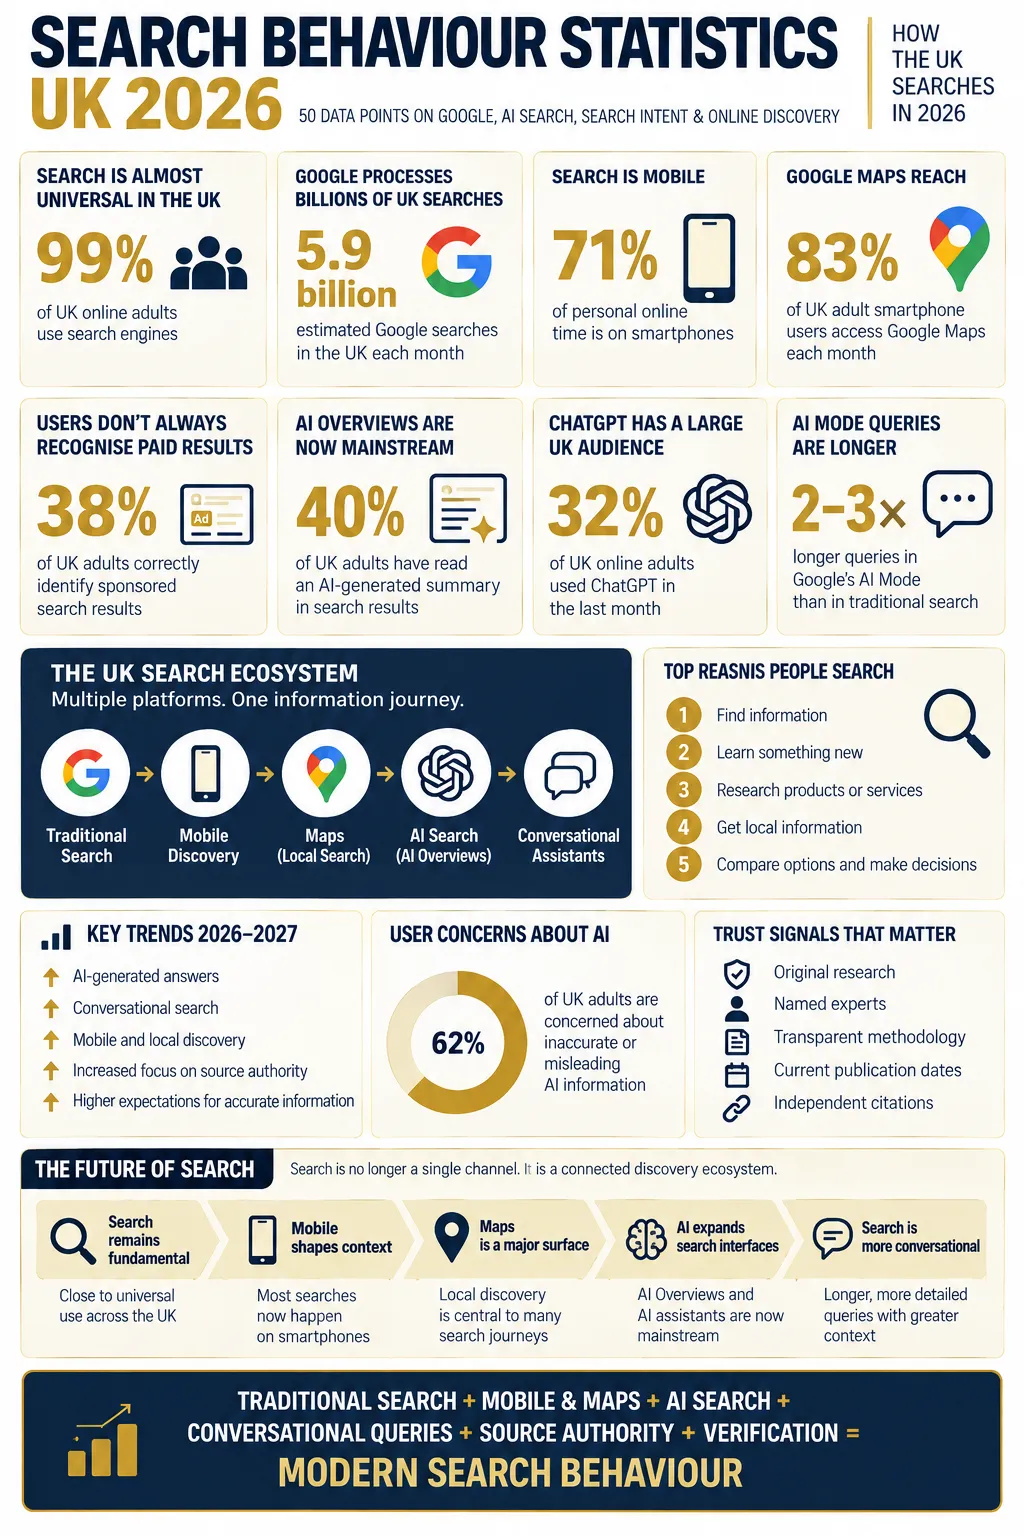
Search behaviour in the UK is undergoing one of its most significant changes since mainstream search engines became the dominant gateway to information.
Traditional search remains deeply embedded in everyday internet use, but the way people discover information is becoming more varied.
Consumers can now move between Google Search, AI-generated summaries, ChatGPT and other AI assistants, social platforms, video services, marketplaces, maps and specialist websites during the same research journey.
The result is not the disappearance of search.
It is the expansion of search behaviour across a wider range of interfaces, formats and discovery systems.
Central Research Finding
Search remains near-universal among UK internet users, but search journeys are becoming increasingly distributed across conventional search engines, AI-generated answers, conversational assistants, social platforms, video and other digital discovery environments.
Executive Summary
The evidence reviewed for this report shows the scale of search within everyday UK online behaviour:
- 95% of UK adults used the internet within the previous three months.
- 86% of UK adults use the internet every day.
- 96% of UK online adults report using search engines within the previous year.
- UK adults generated nearly 9 billion Google search page views in October 2025 alone.
- Google Search reached 82% of UK online adults in May 2025.
- Ofcom estimates around 3 billion Google searches take place in the UK each month.
- 95% of online children aged 8–14 used Google Search in Ofcom’s measured audience research.
- Only 52% of search-engine users correctly identified sponsored Google results as paid placements in an Ofcom test.
- Only 17% of adults believed that appearing in search results means a website will contain accurate and unbiased information.
These figures establish an important starting point for understanding UK search behaviour in 2026.
Search engines remain enormously important, but consumers do not necessarily interpret every result in the same way, trust every result automatically or understand the commercial mechanisms shaping what they see.
The UK Search Behaviour Shift
↓
Search Results & Paid Listings
↓
AI-Generated Summaries
↓
Conversational Follow-Up Questions
↓
Social, Video & Marketplace Discovery
↓
Multi-Platform Search Behaviour
Research Structure: 50 UK Search Behaviour Statistics
| Statistics | Research Area | Primary Focus |
|---|---|---|
| 1–10 | UK Search Usage & Online Behaviour | Internet penetration, search-engine usage, Google reach and search literacy |
| 11–20 | Devices, Mobile & Search Access | Smartphones, mobile access, apps, maps and device-led search |
| 21–30 | Search Intent & Decision Behaviour | Research, verification, comparison, commercial intent and result selection |
| 31–40 | AI Search, ChatGPT & Conversational Discovery | AI Overviews, AI assistants, ChatGPT and conversational search |
| 41–50 | Changing Search Journeys & Emerging Behaviour | Cross-platform discovery, trust, AI verification and future search behaviour |
Statistics 1–10 — UK Search Usage & Online Behaviour
Before examining AI search, mobile discovery or changing search intent, it is important to establish how deeply conventional internet and search behaviour remain embedded in the UK.
1. 95% of UK adults used the internet within the previous three months
95% of UK adults reported using the internet during the previous three months in the DSIT Public Engagement Survey 2025/2026.
This establishes the scale of the addressable online population within the UK.
Search behaviour should therefore be understood within an environment in which internet access is close to universal for most adult age groups.
Usage declines materially only among the oldest age groups measured.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026.
2. 86% of UK adults use the internet every day
86% of UK adults reported using the internet every day.
A further 7% said they used it on most days.
Search and online discovery therefore take place within a highly habitual digital environment rather than through occasional internet use.
Search implication: For most UK consumers, online information discovery is part of everyday behaviour.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026.
3. 98% of UK internet users access the internet at home
98% of adults who used the internet reported using it at home.
This reinforces how deeply online access is integrated into normal domestic life.
Information searches, purchasing research, comparison activity and AI-assisted discovery can therefore take place throughout the day rather than being confined to workplace or desktop usage.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026.
4. 96% of UK online adults used a search engine during the previous year
Almost all UK online adults — 96% — reported using a search engine during the previous 12 months.
This is one of the clearest measures of the continued importance of traditional search.
Even while social platforms, marketplaces and generative-AI systems expand as discovery environments, conventional search engines remain used by almost the entire UK online adult population.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
5. UK adults generated nearly 9 billion Google search page views in October 2025
Ipsos iris measured nearly 9 billion Google Search page views among UK adults during October 2025.
Page views and individual searches are not identical measures, so this figure should not be interpreted as nine billion separate search queries.
Nevertheless, it illustrates the extraordinary volume of interaction taking place within Google Search.
Source: Ofcom Adults’ Media Use and Attitudes 2026, citing Ipsos iris Online Audience Measurement.
6. Google Search reached 82% of UK online adults
82% of UK online adults used Google Search in May 2025.
Google Search therefore continued to reach approximately four in five UK online adults during the measured month.
Its reach was 83% in May 2024 and 86% in May 2023.
The modest decline should not be interpreted as evidence that search has become marginal.
Google Search still operates at extremely large population scale.
Source: Ofcom, Online Nation 2025, citing Ipsos iris.
7. Around 3 billion Google searches take place in the UK each month
Ofcom reports approximately 3 billion Google searches per month in the UK.
This figure demonstrates why conventional search continues to matter even as AI-assisted search expands.
The market is not moving cleanly from “search engines” to “AI”.
Instead, AI functionality is increasingly being introduced into an already enormous search environment.
Source: Ofcom, From Apps to AI Search: How the UK Goes Online in 2025.
8. 95% of online children aged 8–14 used Google Search
Google Search reached 95% of online children aged 8–14 in Ofcom’s passive audience measurement.
YouTube reached an even slightly higher 96% of the same age group.
The data is significant because younger consumers are often associated primarily with social or video-led discovery.
Those behaviours matter, but conventional search remains extremely widely used among children as well.
Source: Ofcom, Online Nation 2025.
9. Only 52% of search-engine users correctly identified sponsored Google results as advertising
Just over half — 52% — of search-engine users correctly recognised that the sponsored results shown in Ofcom’s Google Search test appeared because advertisers had paid for the placement.
Other respondents associated the positions with relevance or popularity instead of, or in addition to, recognising the advertising relationship.
This demonstrates that search behaviour is shaped not only by what appears in the results but also by how users interpret why those results appear.
Search literacy implication: Paid and organic visibility may not always be distinguished as clearly by users as marketers assume.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
10. Only 17% of adults believe appearing in search results means a website will contain accurate and unbiased information
Only 17% of adults said they believed that if a website appears in search results it will contain accurate and unbiased information.
This had fallen from 27% in the previous year’s research.
A much larger 63% said that some websites appearing in search results would be accurate or unbiased while others would not.
This suggests that many users approach search results with a degree of scepticism rather than assuming ranking itself guarantees reliability.
Trust implication: Visibility creates an opportunity to be considered, but it does not automatically create trust.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
What Statistics 1–10 Tell Us
The first ten statistics establish that traditional search remains deeply embedded within UK digital behaviour.
Internet use is near-universal, search-engine use reaches almost the entire online adult population, and Google continues to generate billions of UK searches and search-page interactions.
However, the evidence also reveals something more subtle.
Users do not necessarily interpret search results exactly as marketers expect.
Only around half correctly identified paid search placement in Ofcom’s test, while relatively few users assume that appearing in search results automatically means a website is accurate and unbiased.
The search journey can therefore be represented as:
↓
Query
↓
Search Results
↓
Result Interpretation
↓
Trust Assessment
↓
Click, Continue Searching or Choose Another Source
The principal findings from Statistics 1–10 are:
- Internet use is near-universal among UK adults.
- Daily online behaviour is the norm.
- Search-engine use remains almost universal among online adults.
- Google continues to operate at enormous UK scale.
- Traditional search is also widely used among children.
- Users do not always correctly identify paid search placements.
- Ranking alone does not guarantee user trust.
This provides the foundation for the next part of the research: how devices, mobile behaviour, maps and platform access are changing where and how UK consumers search.
Statistics 11–20 — Devices, Mobile & Search Access
Search behaviour is influenced not only by what people want to find but also by the device, application and connection they use to access information.
The smartphone has become particularly important because it allows search and discovery to take place continuously across websites, apps, maps, social platforms, video services and AI assistants.
This creates a search environment that is increasingly mobile, location-aware and app-based.
Research context: Device ownership, time spent online and app usage do not directly measure search queries. They describe the digital environments through which search, navigation, product discovery and information retrieval increasingly occur.
11. 93% of UK adults have access to a smartphone for personal use
93% of UK adults reported having a smartphone available for personal use in 2025/2026.
Smartphones were substantially more widely available than laptops, tablets or desktop computers.
This gives most UK adults continuous access to search engines, maps, ecommerce platforms, social networks and AI assistants throughout the day.
Search implication: Mobile accessibility is now a baseline requirement for organisations seeking visibility within everyday search journeys.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026.
12. Smartphone access reaches 98% among UK adults aged 16–64
98% of UK adults aged 16–64 had access to a smartphone for personal use.
Among adults aged 65 and over, smartphone access remained high but fell to 80%.
The difference demonstrates that device-led search behaviour varies significantly by age even when internet use overall is widespread.
Audience implication: Mobile-first search experiences are particularly important for working-age consumers, while older audiences may retain a stronger mix of smartphone, tablet and computer use.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026.
13. UK online adults spend an average of 4 hours and 30 minutes online each day
UK online adults spent an average of 4 hours and 30 minutes per day online in May 2025.
That was ten minutes more per day than in May 2024.
The measure covers personal use on smartphones, tablets and computers rather than workplace activity.
This level of daily internet use creates repeated opportunities for information search, product research, navigation and digital discovery.
Source: Ofcom, Online Nation 2025, citing Ipsos iris.
14. Smartphones account for around three quarters of measured online time
Smartphones accounted for 75% of men’s measured online time and 79% of women’s measured online time in May 2025.
Computers and tablets therefore accounted for a much smaller share of overall personal online time.
This does not mean every search takes place on a smartphone, but it demonstrates the device environment within which much modern search and discovery occurs.
Search implication: Mobile usability, speed, readable content and simple navigation influence access to a substantial proportion of online journeys.
Source: Ofcom, Online Nation 2025, citing Ipsos iris.
15. UK adult smartphone users use an average of 41 apps each month
UK adult smartphone users accessed an average of 41 smartphone apps during May 2025.
That was up from an average of 38 apps in May 2024.
The figure demonstrates why online discovery can no longer be understood entirely through the web browser.
Consumers move between search engines, messaging services, maps, social media, ecommerce apps, video platforms and other applications.
Discovery implication: Search behaviour increasingly takes place within an app ecosystem as well as through conventional websites.
Source: Ofcom, Online Nation 2025.
16. Adults aged 25–44 use an average of 46 smartphone apps per month
UK smartphone users aged 25–34 and 35–44 each used an average of 46 apps during May 2025.
By comparison, adults aged 65 and over used an average of 31 apps.
This demonstrates that younger and middle-aged consumers tend to operate across a wider range of mobile environments.
Search implication: The customer journey for working-age consumers can involve more platform switching and a wider range of discovery touchpoints than a search-engine-only model suggests.
Source: Ofcom, Online Nation 2025, citing Ipsos iris.
17. Google Maps reaches 77% of UK adult smartphone users
Google Maps was used by 77% of UK adult smartphone users in May 2025.
It was the third-highest-reaching smartphone app in Ofcom’s measurement, behind WhatsApp and Facebook.
The scale of Google Maps matters because local search increasingly occurs inside navigation and mapping interfaces rather than through conventional blue-link search results alone.
Consumers can use Maps to locate:
- Restaurants.
- Hotels.
- Retailers.
- Professional services.
- Healthcare providers.
- Local businesses.
Local-search implication: Business profiles, reviews, category information, opening hours and geographic relevance form an increasingly important part of mobile search visibility.
Source: Ofcom, Online Nation 2025.
18. Google Maps has more than five times the reach of Apple Maps among measured UK adult smartphone users
Google Maps reached 77% of UK adult smartphone users, compared with 15% for Apple Maps and 11% for Waze.
These figures show the scale of Google’s position within location-led mobile discovery.
However, businesses should not assume that every navigation user follows the same path to discovery.
Customers can still arrive through other mapping services, directories, search engines, social platforms and AI recommendations.
Source: Ofcom, Online Nation 2025, citing Ipsos iris.
19. 60% of UK adults report already using 5G
60% of UK adults reported already using 5G mobile technology in 2025/2026.
Awareness was much higher, with 94% of adults having heard of 5G.
Faster mobile connectivity supports increasingly media-rich forms of discovery including maps, video, visual search, AI assistants and real-time mobile research.
Search implication: Search experiences are increasingly expected to function effectively away from fixed desktop connections.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026.
20. One in five UK online adults relies solely on a smartphone for internet access
20% of UK online adults were classified by Ofcom as relying solely on a smartphone for internet access.
This is an important reminder that mobile optimisation is not simply about improving convenience for desktop users who occasionally switch devices.
For a significant minority of the online population, the smartphone is effectively the entire personal internet environment.
Accessibility implication: Poor mobile experiences can exclude or materially disadvantage consumers who do not routinely have access to a larger-screen device.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
What Statistics 11–20 Tell Us
The second group of statistics shows why UK search behaviour can no longer be understood primarily through the desktop browser.
Smartphone access is near-universal among working-age adults, most measured online time takes place on smartphones, and users routinely move between dozens of apps.
Search itself is therefore becoming distributed across different mobile interfaces.
A consumer looking for a local service might move through:
↓
Google Maps
↓
Business Profile & Reviews
↓
Website or App
↓
Navigation, Call or Enquiry
A product search might instead involve:
+
Marketplace App
+
Social Platform
+
Video
+
Brand Website
The principal findings from Statistics 11–20 are:
- 93% of adults have access to a smartphone.
- Smartphone availability reaches 98% among adults aged 16–64.
- UK online adults spend 4.5 hours online each day on average.
- Smartphones account for the majority of measured online time.
- Adult smartphone users interact with an average of 41 apps each month.
- Adults aged 25–44 use an even wider app ecosystem.
- Google Maps reaches more than three quarters of adult smartphone users.
- Google Maps substantially exceeds rival mapping apps in measured reach.
- Most UK adults report using 5G.
- One in five online adults relies solely on a smartphone for internet access.
Search behaviour is therefore increasingly mobile, app-based, location-aware and distributed across multiple interfaces rather than confined to one search engine results page.
Statistics 21–30 — Search Intent, Trust & Decision Behaviour
Search behaviour does not end when a user enters a query.
Consumers must decide which result to trust, which result to click and whether the information they encounter appears independent, commercial, relevant or credible.
This makes search behaviour partly a question of interpretation.
Two users can see exactly the same search results and make very different decisions based on their understanding of advertising, ranking, familiarity and trust.
Research context: Ofcom’s 2026 Adults’ Media Use and Attitudes study included 7,533 UK adults and tested both self-reported confidence and actual ability to interpret online information. This distinction is important because confidence does not always match behaviour.
21. 63% of adults believe some search results will be accurate while others will not
63% of adults take the view that some websites appearing in search results will contain accurate or unbiased information while others will not.
This is substantially higher than the minority who assume appearing in search results automatically indicates accuracy.
The finding suggests that most users understand search results as a collection of possible sources rather than a list of equally reliable answers.
Search implication: Ranking creates visibility, but users may still evaluate the organisation, source and evidence before accepting what they find.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
22. 11% of adults say they click search results simply because they “like the look of” them
11% of adults said they do not think about whether search results are accurate or biased and instead select results they “like the look of”.
The figure had increased from 6% in the previous year’s research.
This illustrates the role that appearance, familiarity, wording and perceived relevance can play in result selection.
Behaviour implication: Search decisions are not always based on detailed source verification; presentation can materially influence which result receives the click.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
23. 25% of users associated top sponsored results with being the “best” or most relevant
25% of search-engine users said sponsored links appeared at the top because they were the “best” or most relevant results.
Respondents had been shown a Google search for walking boots in which the first four results were labelled sponsored.
The finding shows that commercial placement can sometimes be interpreted as a signal of relevance.
Paid-search implication: Users do not necessarily interpret search-result ordering using the same distinctions that marketers make between paid and organic visibility.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
24. 24% associated sponsored search placement with popularity
24% of search-engine users believed the sponsored results appeared prominently because the organisations or websites were popular.
Again, this demonstrates that users can attribute ranking position to characteristics other than advertising.
Prominence itself may therefore influence perceived importance or popularity even where the placement is commercial.
Decision implication: Search-result position can shape perception before a user has evaluated the underlying page or business.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
25. 81% of online adults feel confident they can recognise online advertising
81% of online adults said they were confident in their ability to recognise advertising online.
This level of self-reported confidence appears high.
However, Ofcom’s practical search-result test shows that actual ability does not always align with that confidence.
Research implication: Asking users whether they understand search advertising can produce a different picture from testing whether they identify it correctly in practice.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
26. 72% of online adults feel confident judging whether online information is true or false
72% of online adults said they felt confident judging whether information they encountered online was true or false.
Confidence in evaluating information was lower than general confidence as an internet user, which stood at 89%.
This distinction matters because search increasingly exposes users to information from publishers, businesses, social platforms and AI-generated systems with differing levels of reliability.
Trust implication: Digital familiarity does not automatically mean users feel equally confident assessing the accuracy of the information they encounter.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
27. Only 45% of search-engine users were both confident and correct when identifying sponsored search results
45% of search-engine users were both confident that they could recognise online advertising and correctly identified the sponsored links in Ofcom’s test.
This is considerably lower than the 81% who said they felt confident recognising advertising.
The gap between perceived ability and tested performance is important when interpreting consumer search behaviour.
Search-literacy implication: Self-reported understanding of the search results page can overstate actual recognition of commercial placement.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
28. 37% were confident they could recognise advertising but failed the sponsored-search test
37% of search-engine users said they were confident recognising advertising but did not correctly identify the sponsored search results when tested.
Ofcom describes this as a “confident but not able” group.
This is one of the more important behavioural findings in the report because it shows that search-result interpretation is not necessarily improved simply by users feeling digitally experienced.
Marketing implication: Businesses should not assume that every consumer clearly distinguishes organic ranking, advertising and other forms of search presentation.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
29. 47% of 25–34-year-old search users were confident about recognising advertising but incorrect
47% of search-engine users aged 25–34 fell into Ofcom’s “confident but not able” category when recognising search advertising.
The equivalent figure was 42% among 35–44-year-olds and 41% among 16–24-year-olds.
Younger adults therefore did not necessarily perform better simply because they tend to use digital services frequently.
Behaviour implication: High levels of online activity should not automatically be interpreted as high levels of search literacy.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
30. 59% of search users aged 65–74 correctly identified paid search results
59% of search-engine users aged 65–74 correctly identified the paid placements in Ofcom’s sponsored-search test.
Adults aged 55–64 were close behind at 58%.
These older groups outperformed younger users in identifying that the prominent results were advertisements.
This challenges the assumption that younger, heavier internet users necessarily understand every aspect of modern search interfaces better than older consumers.
Research implication: Search behaviour varies by age, but greater digital usage does not automatically produce stronger critical interpretation of search results.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
What Statistics 21–30 Tell Us
The third group of statistics shows that search behaviour is not simply a mechanical process of entering a query and clicking the highest result.
Users interpret the results page through a combination of:
- Position.
- Perceived relevance.
- Popularity.
- Appearance.
- Familiarity.
- Trust.
- Recognition of advertising.
The evidence also demonstrates a substantial difference between confidence and ability.
Most adults believe they can recognise advertising, yet much smaller proportions correctly identify sponsored results when presented with a real search example.
The modern search decision process can therefore be represented as:
↓
Result Visibility
↓
Perceived Relevance & Familiarity
↓
Advertising / Organic Interpretation
↓
Trust Assessment
↓
Click or Continued Research
The principal findings from Statistics 21–30 are:
- Most adults recognise that search results contain sources of differing reliability.
- A growing minority select results primarily because they like their appearance.
- Some users interpret paid prominence as relevance or popularity.
- 81% feel confident recognising online advertising.
- 72% feel confident judging whether online information is true or false.
- Only 45% of search users were both confident and correct in Ofcom’s sponsored-result test.
- 37% were confident but failed to identify the advertising correctly.
- This overconfidence was particularly pronounced among 25–34-year-olds.
- Older search users performed comparatively strongly in recognising paid placement.
The evidence therefore reinforces an important distinction: search visibility determines what can be seen, but trust, interpretation and perceived relevance help determine what users actually choose.
Statistics 31–40 — AI Search, ChatGPT & Conversational Discovery
Artificial intelligence is beginning to change both the interface and the behaviour of online search.
Users increasingly encounter AI-generated answers inside conventional search engines while also actively using standalone systems such as ChatGPT, Gemini, Copilot and Perplexity.
The significance of this change is not simply that another digital platform has appeared.
AI search changes the structure of the search interaction itself.
Instead of entering a short query, reviewing a list of links and selecting a webpage, users can increasingly ask longer questions, receive a synthesised answer and continue the interaction through follow-up prompts.
Research context: AI chatbot usage should not be treated as identical to AI search usage. Users may use ChatGPT, Gemini or other tools for writing, coding, image creation or other activities. Where audience figures measure total chatbot visitors rather than search activity specifically, that distinction is retained below.
31. Around 30% of Google searches now display an AI Overview
Ofcom reports that approximately 30% of searches now display AI-generated Overviews.
AI Overviews place a generated summary above or alongside traditional search results.
This changes search behaviour because users may obtain an answer before deciding whether to visit an external website.
The search-results page therefore increasingly acts as both a navigation interface and an answer interface.
Search implication: Organic visibility increasingly includes the possibility of being represented within an AI-generated answer as well as ranking as a conventional link.
Source: Ofcom, Online Nation 2025.
32. 53% of UK adults say they often see AI-generated search summaries
More than half of UK adults — 53% — say they often encounter AI-generated summaries when searching.
This is important because most users are not necessarily making a deliberate decision to switch from traditional search to AI search.
AI-generated answers are increasingly appearing inside search experiences they already use.
Behaviour implication: AI search adoption can occur passively through changes to mainstream search interfaces as well as actively through standalone AI tools.
Source: Ofcom, From Apps to AI Search: How the UK Goes Online in 2025.
33. ChatGPT recorded 1.8 billion UK visits in the first eight months of 2025
ChatGPT generated approximately 1.8 billion UK visits between January and August 2025.
The scale demonstrates that conversational AI has moved beyond a niche technology audience.
Visits do not tell us what every user was doing, and should therefore not be treated as 1.8 billion searches.
However, the data demonstrates the rapidly growing role of conversational AI within the UK’s wider information ecosystem.
Source: Ofcom, Online Nation 2025.
34. ChatGPT UK visits increased from 368 million to 1.8 billion within one year
ChatGPT recorded 368 million UK visits during the first eight months of 2024, compared with 1.8 billion during the equivalent period in 2025.
That means measured visits were almost five times as high year on year.
Few search-related behavioural shifts have occurred at this speed in recent years.
Discovery implication: Conversational AI has developed sufficient scale that businesses should treat it as an emerging information-discovery environment rather than an experimental edge case.
Source: Ofcom, Online Nation 2025.
35. 15.8 million UK online adults visited a major AI chatbot in June 2025
15.8 million UK online adults visited at least one of seven major AI chatbot services in June 2025.
That represented approximately 32% of the UK online adult population.
The measured services were:
- ChatGPT.
- Microsoft Copilot.
- Google Gemini.
- DeepSeek.
- Perplexity.
- Claude.ai.
- Grok.
Ofcom explicitly notes that these audience numbers do not indicate how many users were specifically conducting searches within the tools.
Source: Ofcom, The Era of Answer Engines, citing Ipsos iris.
36. ChatGPT alone reached 13 million UK online adults in June 2025
ChatGPT reached approximately 13 million UK online adults in June 2025.
This represented approximately 26% of the UK online adult population.
ChatGPT had substantially greater standalone reach than the other individual AI chatbots included in Ofcom’s comparison.
Copilot reached approximately 2.6 million adults, while Gemini reached approximately 1.7 million.
Search implication: ChatGPT has developed an audience large enough for brand and information visibility within the platform to become commercially relevant to many organisations.
Source: Ofcom / Ipsos iris, The Era of Answer Engines.
37. 59% of UK adults recently used some form of generative AI
59% of UK adults reported using a form of generative AI during the previous three months.
The DSIT definition includes generative text and speech systems, image or media generation, and certain workplace AI systems.
It should therefore not be interpreted as meaning that 59% of UK adults use AI specifically for search.
Nevertheless, the statistic establishes that interaction with generative systems has become mainstream.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026.
38. Generative AI usage exceeds 75% among UK adults under 45
At least three quarters of adults in every age group below 45 reported recent generative-AI use.
Usage declines substantially among older age groups, reaching 18% among adults aged 75–84 and 8% among those aged 85 or over.
This age gradient matters because emerging search behaviour is unlikely to develop at the same rate across the whole population.
Search implication: Younger and middle-aged audiences are currently more exposed to AI-mediated information and conversational interfaces than the oldest consumer groups.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026.
39. 75% of generative-AI users in the DSIT online sample use AI at least weekly
Among generative-AI users who completed the online survey, 75% reported using AI tools at least once a week.
A further 35% reported using them at least daily.
This suggests that AI use is becoming habitual among many adopters rather than consisting solely of occasional experimentation.
The survey also found that 48% of these users employed AI to summarise or explain something, an activity closely related to information discovery.
Behaviour implication: Conversational interaction with AI is becoming part of regular digital routines for a substantial proportion of users.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026. The frequency figures apply to generative-AI users within the survey’s online sample.
40. Early Google AI Mode users ask questions two to three times longer than traditional search queries
Google reports that early AI Mode users ask questions that are approximately two to three times the length of traditional search queries.
Google introduced AI Mode in the UK in July 2025.
The interface is designed for longer, more complex questions and follow-up interactions.
A conventional search might be:
SEO agency Manchester
A conversational query can instead become:
Which Manchester SEO agencies specialise in B2B organisations, publish original AI-search research and have experience with enterprise technical SEO?
These longer queries contain considerably more context about what the user actually wants.
Search implication: Conversational search can move search optimisation away from isolated keywords and towards understanding detailed needs, entities, attributes and decision criteria.
Source: Google UK, Introducing AI Mode in the UK, July 2025.
What Statistics 31–40 Tell Us
The fourth group of statistics shows that AI is changing UK search behaviour through two different mechanisms.
The first is embedded AI search.
Users may continue using Google in broadly the same way as before but increasingly encounter AI-generated summaries and conversational features within the search engine itself.
The second is intentional conversational discovery.
Users actively open ChatGPT, Gemini, Copilot or other AI systems and ask questions directly.
These two routes can be represented as:
Traditional Search Query
↓
AI Overview + Search Results
OR
Conversational Question
↓
AI-Generated Answer
↓
Follow-Up Question
↓
Sources, Recommendations or Further Research
The principal findings from Statistics 31–40 are:
- AI Overviews already appear across a substantial proportion of searches.
- More than half of UK adults regularly encounter AI-generated search summaries.
- ChatGPT is generating billions of UK visits.
- Its UK traffic increased almost fivefold year on year in the period measured.
- Major AI chatbots collectively reach almost one third of UK online adults.
- ChatGPT is currently the largest standalone AI chatbot measured by Ofcom.
- Generative-AI use has become mainstream among UK adults.
- Adoption is particularly high among adults under 45.
- AI use is becoming habitual among many adopters.
- Conversational search queries can be substantially longer than traditional keyword searches.
This does not mean traditional search has disappeared.
Google still processes billions of UK searches each month and reaches most online adults.
The more significant behavioural change is that search is expanding from finding links towards receiving answers, asking follow-up questions and conducting increasingly conversational research.
Statistics 41–50 — Changing Search Journeys, Verification & Emerging Behaviour
The final ten statistics show that the most important change in UK search behaviour is not simply the arrival of another search interface.
It is the growing tension between convenience and verification.
AI-generated answers can make information faster to access, summarise and interpret. At the same time, UK consumers remain concerned about accuracy, misleading information and their ability to distinguish machine-generated material from human-created content.
Search behaviour is therefore increasingly likely to involve both answer consumption and source evaluation.
Research context: Ofcom and DSIT use different definitions and survey methodologies when measuring AI usage. Their percentages should therefore be interpreted within the scope of each study rather than combined into a single UK AI-adoption estimate.
41. 54% of UK adults say they use AI tools, up from 31% a year earlier
Ofcom’s 2026 research found that 54% of UK adults said they used AI tools, compared with 31% in the previous year’s study.
This represents a substantial year-on-year increase in reported AI use.
The figure should not be interpreted as meaning that 54% use AI specifically for search. It measures AI-tool usage more broadly.
Nevertheless, the speed of adoption is relevant because AI tools increasingly include search, summarisation, recommendation and information-retrieval capabilities.
Behaviour implication: AI-mediated information access is moving rapidly from early adoption towards mainstream digital behaviour.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
42. 75% of UK online adults read AI-generated search summaries at least sometimes
Three quarters of UK online adults — 75% — said they read AI-generated search summaries at least sometimes.
This is broader than the proportion who say they encounter such summaries often.
It demonstrates that AI-generated search content has already become part of the search experience for a large majority of online adults.
Search implication: AI summaries are increasingly part of mainstream search-result consumption rather than a specialist feature used only by technology enthusiasts.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
43. 57% of adults aware of AI would trust AI-generated news less than a human-written story
57% of adults who were aware of AI said they would trust an AI-generated news story less than one written by a human.
This demonstrates that increasing exposure to AI-generated information does not automatically produce equivalent trust.
Users may value speed and convenience while still attaching importance to human authorship, source reputation and verification.
Trust implication: AI-generated answers do not eliminate the importance of identifiable, credible underlying sources.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
44. Only 44% of adults feel confident identifying AI-generated content
44% of adults said they felt confident recognising AI-generated content.
Ofcom describes confidence in this area as mixed rather than universal.
As generative text, imagery, audio and video become more realistic, identifying whether information has been generated or modified by AI may become increasingly difficult.
Search implication: Users may need to evaluate the credibility of the source and evidence rather than relying only on whether they believe they can recognise AI-generated material visually or linguistically.
Source: Ofcom, Adults’ Media Use and Attitudes 2026.
45. 88% of UK adults are concerned about harmful AI-generated content
57% of UK adults said they were very concerned about harmful AI-generated content and a further 31% were somewhat concerned.
Combined, this means 88% expressed some level of concern.
Concern was evident across age groups, including younger adults who are among the heaviest adopters of generative AI.
Behaviour implication: High adoption and high concern can exist simultaneously. Consumers may use AI regularly while remaining cautious about the information it produces.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026.
46. 74% of UK adults are concerned that AI-generated information may be inaccurate
74% of UK adults identified inaccurate information as a potential risk of artificial intelligence.
Accuracy was the most frequently identified AI risk in the DSIT research.
This is particularly relevant to search because users increasingly encounter generated answers before visiting an external source.
Verification implication: Organisations that publish transparent, sourceable and factually robust information may become increasingly valuable within AI-mediated search journeys.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026.
47. 64% are concerned AI could spread false or misleading information
64% of UK adults identified the spread of false or misleading information as a risk associated with AI.
This concern goes beyond individual factual errors.
It reflects the possibility that inaccurate information can be generated, reproduced and distributed at scale.
Search implication: Source reputation, corroboration and evidence may become increasingly important as generated answers become easier to produce and distribute.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026.
48. 57% are concerned AI could negatively affect people’s ability to think critically or creatively
57% of UK adults identified a negative effect on people’s ability to think creatively or critically as a potential AI risk.
This has implications for search behaviour because answer engines can reduce the effort required to locate, compare and synthesise information.
That convenience can be valuable, but it may also change how often users inspect primary sources or consider competing viewpoints.
Behaviour implication: The future of search is likely to involve an ongoing balance between answer convenience and active information evaluation.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026.
49. 47% of UK adults see easier access to information or advice as a benefit of AI
47% of adults identified easier access to information or advice as a societal benefit of artificial intelligence.
It was the most commonly identified AI benefit overall in the DSIT research.
This directly explains part of AI’s relevance to search.
Users can ask a natural-language question and receive a summarised response without manually reviewing numerous websites first.
Search implication: Convenience and lower information-retrieval effort are powerful drivers of AI-assisted search adoption.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026.
50. 48% of generative-AI users use AI to summarise or explain information
48% of generative-AI users in the DSIT online sample said they used AI to help summarise or explain something.
This is one of the clearest behavioural connections between generative AI and conventional information search.
Instead of simply locating documents, users can ask AI systems to interpret, condense or explain the information for them.
The role of the search interface therefore begins to move from:
“Find me information”
to
“Find, summarise and explain this information for me”
Search implication: Search behaviour is expanding from document retrieval towards interpretation and synthesis.
Source: Department for Science, Innovation and Technology, Public Engagement Survey 2025/2026. This figure applies to generative-AI users represented in the online sample.
What Statistics 41–50 Tell Us
The final ten statistics reveal the central contradiction shaping emerging search behaviour.
Users value AI because it can make information easier and faster to access.
At the same time, they remain concerned about whether the answers are accurate, trustworthy or misleading.
This creates a new search journey:
↓
Search Engine or AI Assistant
↓
Generated Answer or Summary
↓
Trust Assessment
↓
Source Verification
↓
Follow-Up Search or Decision
The principal findings from Statistics 41–50 are:
- AI-tool usage is increasing rapidly.
- Three quarters of online adults already read AI-generated search summaries at least sometimes.
- AI-generated information attracts lower trust than equivalent human-written news among many consumers.
- Less than half of adults feel confident recognising AI-generated content.
- 88% express concern about harmful AI-generated material.
- Accuracy is the most widely identified AI risk.
- False and misleading information remains a major public concern.
- Many adults are concerned about AI’s effect on critical thinking.
- At the same time, easier access to information is considered one of AI’s greatest benefits.
- Almost half of generative-AI users use the technology to summarise or explain information.
These findings help explain why the future of search is unlikely to be determined only by which platform generates the fastest answer.
The more important competitive question may become:
Which organisations are sufficiently relevant, authoritative and verifiable to become trusted sources behind those answers?
The emerging UK search environment therefore combines speed, convenience and conversational discovery with a continuing need for source authority, evidence and trust.
CGO Media Analysis — What the 50 Search Behaviour Statistics Tell Us
Taken together, the 50 statistics show that UK search behaviour is becoming more complex without making traditional search irrelevant.
Google still reaches most online adults and processes billions of searches, but the search journey is increasingly distributed across smartphones, maps, apps, AI-generated summaries, conversational assistants, social platforms and other discovery environments.
The strongest shift is therefore not from “search” to “no search”.
It is from a relatively simple search-engine journey towards a broader, multi-interface discovery system.
UK search behaviour in 2026 is best understood as a connected discovery ecosystem in which conventional search, mobile interfaces, maps, AI answers, conversational assistants and source verification increasingly interact within the same customer journey.
1. Traditional Search Remains Deeply Embedded
The first ten statistics establish that search engines remain a fundamental part of everyday UK online behaviour.
Internet usage is near-universal, search-engine usage is almost universal among online adults, and Google continues to operate at enormous scale.
This matters because discussion around AI search can sometimes imply that conventional search has already been displaced.
The evidence does not support that conclusion.
CGO Media interpretation: The UK is not moving from traditional search to AI search in a single step. AI is being layered onto an existing search environment that still attracts extremely high usage.
2. Search Is Becoming More Mobile and Contextual
Smartphones dominate personal internet access and account for the majority of measured online time.
That changes the context in which people search.
Queries can now occur while:
- Travelling.
- Shopping.
- Comparing local services.
- Watching video.
- Using social media.
- Navigating through maps.
Search increasingly happens at the moment a need emerges rather than at a fixed desktop session.
CGO Media interpretation: Mobile has changed search from a destination into an always-available layer of everyday decision-making.
3. Maps and Apps Are Part of Search Behaviour
Google Maps reaches a large majority of UK adult smartphone users, while consumers routinely use dozens of apps every month.
This demonstrates that search does not always begin on a conventional search-engine results page.
A user looking for a business may begin directly inside:
- Google Maps.
- Amazon.
- YouTube.
- A social platform.
- A retailer app.
- An AI assistant.
CGO Media interpretation: Search visibility increasingly means being discoverable across the platforms where intent is expressed, not only ranking in conventional web search.
4. Search Result Position Influences Perception
The behavioural evidence around sponsored results shows that users do not interpret search interfaces purely analytically.
Prominent placement can be associated with:
- Relevance.
- Popularity.
- Quality.
- Commercial prominence.
This matters because visibility can shape perception before the user has evaluated the underlying content.
CGO Media interpretation: Search visibility is partly informational and partly perceptual. Where a result appears can influence what users infer about the organisation behind it.
5. Digital Confidence Does Not Equal Search Literacy
One of the strongest findings in the research is the gap between self-reported confidence and tested ability.
Many users say they are confident recognising online advertising, yet substantially fewer correctly identify paid search placements when tested.
This difference is visible even among younger adults who are heavy digital users.
CGO Media interpretation: Frequent internet use should not automatically be interpreted as strong understanding of how search interfaces, advertising and algorithmic visibility operate.
6. Ranking Creates Visibility but Not Automatic Trust
Only a minority of adults believe that a website appearing in search results must contain accurate and unbiased information.
Most users recognise that search results contain sources of varying quality.
This means organisations need more than ranking position alone.
Trust can also depend on:
- Brand familiarity.
- Evidence.
- Expertise.
- Reviews.
- Source transparency.
- Third-party authority.
CGO Media interpretation: Search visibility wins consideration; authority and evidence help convert consideration into trust.
7. AI Is Changing Search Without Replacing Google
AI-generated summaries now appear within conventional search, while standalone AI assistants have developed substantial UK audiences.
The significance is that consumers are not necessarily choosing between two completely separate behaviours.
They may:
- Search Google.
- Read an AI Overview.
- Open a cited source.
- Ask ChatGPT a follow-up question.
- Return to conventional search.
The boundaries between search engines and answer engines are therefore becoming increasingly blurred.
CGO Media interpretation: The emerging competition is increasingly between different stages of the same information journey rather than between entirely separate search behaviours.
8. Search Queries Are Becoming More Conversational
AI interfaces enable users to express far more context than conventional short keyword searches.
Instead of reducing a need to a few words, users can specify:
- Location.
- Budget.
- Industry.
- Preferences.
- Constraints.
- Comparison criteria.
Longer conversational queries can therefore expose much more information about real search intent.
CGO Media interpretation: Search optimisation increasingly needs to understand entities, attributes and decision criteria rather than focusing only on isolated keyword phrases.
9. Search Is Shifting From Retrieval Towards Interpretation
A conventional search engine primarily helps users locate information.
Generative AI can increasingly:
- Find information.
- Summarise it.
- Compare it.
- Explain it.
- Answer follow-up questions.
That changes the role of the search interface.
Users may increasingly expect the system to perform part of the research process rather than merely direct them towards documents.
CGO Media interpretation: Search is moving from information retrieval towards information synthesis, which increases the importance of becoming a credible source behind the generated answer.
10. Convenience and Trust Are Developing in Parallel
Consumers clearly value AI’s ability to make information easier to access.
At the same time, concern about inaccurate and misleading information remains high.
This creates a search environment in which convenience and scepticism can coexist.
A user may accept an AI-generated summary as a starting point while still wanting to verify:
- The source.
- The organisation.
- The evidence.
- The publication date.
- The expertise behind the claim.
CGO Media interpretation: The growth of answer engines may increase rather than reduce the strategic value of credible, verifiable source material.
The CGO Media Search Behaviour Model
The 50 statistics suggest that modern UK search behaviour increasingly operates through a connected sequence:
↓
Search Engine, App, Map or AI Assistant
↓
Results, Recommendations or Generated Answer
↓
Relevance & Trust Assessment
↓
Source Verification
↓
Follow-Up Search, Comparison or Decision
This model helps explain why traditional SEO alone no longer describes the entire search visibility challenge.
An organisation can be discovered through:
- A conventional organic result.
- A paid search result.
- Google Maps.
- An AI Overview.
- An AI assistant citation.
- A video result.
- A marketplace.
- A social recommendation.
Each environment has different ranking and recommendation mechanisms, but they increasingly contribute to the same user objective: finding enough relevant and trustworthy information to make a decision.
The strategic shift is therefore from ranking for individual keywords towards earning visibility, relevance and trust across the wider search and discovery ecosystem.
What UK Businesses Should Do in 2026
The 50 search behaviour statistics show that UK businesses need to think beyond conventional rankings without abandoning them.
Traditional search still matters enormously, but discovery is increasingly spread across mobile devices, maps, AI-generated summaries, conversational assistants, marketplaces, social platforms and video.
The strongest strategy is therefore to build visibility across the wider search ecosystem while improving the trust and clarity of the information users find.
The priority for 2026 should not be “SEO or AI search”. It should be building a search visibility system that performs across Google, Maps, AI answers, conversational search and other discovery environments.
1. Protect Traditional Organic Search Visibility
Google still reaches most UK online adults and processes billions of searches every month.
Businesses should therefore continue investing in the foundations of organic search:
- Technical SEO.
- Crawlability.
- Indexation.
- Site architecture.
- Internal linking.
- Content relevance.
- Page speed.
- Mobile usability.
Recommended action: Do not weaken core SEO in response to AI-search growth. Strengthen it while expanding into new discovery environments.
2. Build for Conversational Queries
AI-assisted search allows users to ask longer and more specific questions.
Businesses should therefore create content that answers complete decision criteria rather than targeting only short keyword phrases.
Useful content should address:
- Who the service is for.
- Location.
- Industry.
- Price or budget considerations.
- Use cases.
- Comparisons.
- Advantages and limitations.
- Evidence and proof.
Recommended action: Build pages around real user questions and decision criteria, not just isolated keywords.
3. Strengthen Local and Maps Visibility
Google Maps reaches a large majority of UK adult smartphone users.
For local organisations, Maps can therefore be a search environment in its own right.
Businesses should keep the following accurate and current:
- Business name.
- Address.
- Phone number.
- Opening hours.
- Categories.
- Services.
- Images.
- Reviews.
Recommended action: Treat Google Business Profile and Maps visibility as core search infrastructure for location-dependent businesses.
4. Improve Mobile Search Experiences
Smartphones account for most measured personal online time, and a significant minority of online adults rely solely on a smartphone for internet access.
Businesses should ensure that mobile users can quickly:
- Understand the proposition.
- Read content.
- Navigate the site.
- Find contact details.
- Complete forms.
- Call or message.
- Make purchases.
Recommended action: Test important search landing pages on real mobile devices rather than treating desktop layouts as the default.
5. Make Important Information Explicit
AI systems and search engines work more effectively when important information is clear, consistent and easy to interpret.
Businesses should make core information explicit, including:
- Who the organisation is.
- What it does.
- Where it operates.
- Who it serves.
- What makes it different.
- Who its experts are.
- What evidence supports its claims.
Recommended action: Reduce ambiguity across important commercial and research pages so both users and machines can understand the organisation consistently.
6. Build Source Authority
The statistics show that users do not automatically trust information simply because it appears in search results or an AI answer.
Useful authority signals include:
- Original research.
- Named authors and experts.
- Methodology.
- Primary data.
- Independent citations.
- Media references.
- Current publication dates.
- Transparent corrections and updates.
Recommended action: Publish material worth citing rather than producing content designed only to target keywords.
7. Optimise for AI Answers Without Writing for Machines
AI Overviews and conversational assistants increasingly synthesise information from multiple sources.
Content that is easier to understand and verify may be more useful within those systems.
Businesses should prioritise:
- Clear headings.
- Direct factual answers.
- Concise definitions.
- Evidence.
- Structured comparisons.
- Consistent entity information.
- Strong source attribution.
This should not result in robotic or repetitive content.
Recommended action: Make content easy to interpret, quote and verify while keeping it useful for human readers.
8. Make Verification Easy
Concerns about inaccurate and misleading AI information create an opportunity for organisations that make evidence easy to inspect.
Useful verification elements include:
- Source links.
- Research dates.
- Named methodology.
- Author credentials.
- References.
- Data tables.
- Clearly marked updates.
Recommended action: Assume that high-value users, journalists and researchers may want to verify important claims quickly.
9. Measure More Than Traditional Rankings
Ranking positions remain useful, but they do not capture the whole modern search journey.
Where measurement is possible, businesses should also consider:
- Organic traffic.
- Branded search demand.
- Local visibility.
- Google Business Profile interactions.
- AI referral traffic.
- AI citations.
- Lead quality.
- Conversion rate.
Recommended action: Measure whether search visibility produces meaningful discovery and commercial outcomes rather than relying on rank tracking alone.
10. Build for the Entire Search Journey
The modern user may move between several environments before making a decision.
A journey might look like:
↓
AI Overview
↓
Brand Website
↓
Reviews or Maps
↓
ChatGPT Follow-Up
↓
Return Visit or Enquiry
No single touchpoint necessarily explains the whole decision.
Recommended action: Build a search strategy around discovery, trust, comparison and conversion rather than treating the first click as the entire customer journey.
A Practical Search Visibility Priority Model for 2026
↓
2. Strengthen Mobile & Local Visibility
↓
3. Answer Conversational Search Intent
↓
4. Build Entity & Source Authority
↓
5. Improve AI-Search Readiness
↓
6. Make Evidence Easy to Verify
↓
7. Measure Discovery Through to Conversion
The old search question was often:
“How do we rank number one for this keyword?”
The stronger question for 2026 is:
“How do we become visible, relevant and trusted wherever our audience searches for information?”
That shift turns search strategy from a rankings exercise into a broader discovery, authority and decision system.
Search Behaviour Trends UK 2026–2027
The evidence across the 50 statistics suggests that UK search behaviour will continue to change through 2026 and 2027, but not through a simple replacement of search engines by AI assistants.
The more likely direction is a gradual convergence of conventional search, AI-generated answers, maps, mobile applications, social discovery and conversational interfaces.
The trends below are therefore presented as evidence-led directions rather than guaranteed predictions.
The defining search trend for 2026–2027 is likely to be continued fragmentation of the discovery journey alongside greater integration between search engines, AI answers, conversational assistants and mobile platforms.
Trend 1 — Traditional Search Remains Resilient
Google continues to reach most UK online adults and processes billions of searches every month.
That scale makes rapid abandonment of conventional search unlikely.
Instead, search engines are themselves evolving by incorporating generative AI and conversational functionality.
2026–2027 direction: Traditional search remains a major discovery channel while becoming increasingly AI-assisted.
Trend 2 — AI Overviews Become a Normal Part of Search
AI-generated summaries already appear across a substantial proportion of searches, and most online adults encounter them at least sometimes.
As users become more familiar with generated summaries, the search-results page increasingly operates as both an answer destination and a gateway to external sources.
2026–2027 direction: Businesses increasingly compete for visibility inside generated summaries as well as within traditional organic results.
Trend 3 — Conversational Queries Become Longer and More Specific
AI interfaces allow users to express intent with far greater detail than short conventional keyword searches.
Queries increasingly include:
- Context.
- Budget.
- Location.
- Preferences.
- Constraints.
- Comparison criteria.
This can create richer signals about what the user actually wants.
2026–2027 direction: Search optimisation increasingly shifts from isolated keyword matching towards understanding complete user needs and decision criteria.
Trend 4 — Search Moves From Retrieval Towards Synthesis
Conventional search largely helped users locate documents.
Generative search can increasingly:
- Find information.
- Summarise it.
- Compare options.
- Explain concepts.
- Generate recommendations.
The interface therefore performs more of the research process itself.
2026–2027 direction: Source visibility increasingly depends on whether content can contribute useful evidence to a generated answer, not only whether the page ranks.
Trend 5 — Mobile Search Becomes Even More Contextual
Smartphones already account for most measured online time.
That means search increasingly happens while users are moving between physical and digital environments.
Location, maps, opening hours, availability, reviews and proximity therefore become increasingly relevant to the search journey.
2026–2027 direction: Mobile and local search become more tightly integrated with navigation, business profiles and real-world decision-making.
Trend 6 — Maps Become a Larger Discovery Surface
Google Maps already reaches most UK adult smartphone users.
For many local journeys, a map interface can answer the key questions immediately:
- Where is it?
- Is it open?
- How is it reviewed?
- How far away is it?
- Can I call or navigate there?
2026–2027 direction: Local discovery increasingly becomes a maps-and-profile experience rather than a website-first experience.
Trend 7 — Multi-Platform Search Journeys Become More Normal
Consumers increasingly move between platforms before making a decision.
A search journey can involve:
- Google.
- YouTube.
- Social media.
- Maps.
- Marketplaces.
- ChatGPT or another AI assistant.
This weakens the idea that one platform owns the entire search journey.
2026–2027 direction: Search visibility increasingly depends on consistency across multiple discovery environments.
Trend 8 — Source Authority Becomes More Important
AI-generated information offers convenience, but concern about accuracy and misinformation remains high.
This creates greater potential value for:
- Original research.
- Named experts.
- Primary data.
- Methodology.
- Independent references.
- Clear publication dates.
2026–2027 direction: Search authority increasingly depends on being credible enough to be trusted by both users and systems synthesising information.
Trend 9 — Verification Becomes Part of the Search Journey
If users are uncertain about AI-generated answers, they may increasingly inspect the cited sources behind them.
This creates a new form of search behaviour:
↓
Source Inspection
↓
Brand / Author Evaluation
↓
Verification or Further Search
2026–2027 direction: Search may increasingly include a verification stage after the answer rather than ending when an answer first appears.
Trend 10 — Rankings Become One Visibility Metric Among Several
Traditional ranking positions will remain important, but they increasingly describe only one part of search visibility.
Businesses may also need to assess:
- AI Overview inclusion.
- AI citations.
- Google Maps visibility.
- Branded search demand.
- Video discovery.
- Marketplace visibility.
- Referral traffic from AI systems.
2026–2027 direction: Search measurement broadens from rankings towards overall discoverability across multiple interfaces.
The Direction of UK Search Behaviour
↓
Multi-Interface Discovery
↓
Generated Answers
↓
Conversational Follow-Ups
↓
Source Verification
↓
Comparison & Decision
↓
Integrated Search & Discovery
The major change is therefore not that users stop searching.
It is that search becomes more distributed, more conversational and more integrated with other discovery environments.
The organisations best positioned for 2026–2027 are likely to be those that can remain visible, understandable and trustworthy across both conventional search and emerging answer-led interfaces.
Research Methodology & Limitations
This report was prepared by the CGO Media Research Team to provide an evidence-led overview of search behaviour in the UK in 2026.
The research combines official government statistics, independent audience measurement, media-literacy research and first-party platform data across five main areas:
- UK search usage and online behaviour.
- Devices, mobile access and maps.
- Search intent, trust and decision behaviour.
- AI search, ChatGPT and conversational discovery.
- Changing search journeys, verification and emerging behaviour.
The aim is not to create a single composite measure of “UK search behaviour”.
Instead, the report brings together 50 separate data points that describe how people access search, interpret results, use mobile devices, engage with AI and assess trust across different discovery environments.
Search-engine usage, audience reach, AI-tool usage, survey confidence and tested media-literacy behaviour measure different things. They should not be combined as though they represent the same population, method or underlying behaviour.
Primary Research Sources
CGO Media prioritised primary or near-primary research wherever possible.
Principal sources include:
- Ofcom.
- Office for National Statistics where relevant.
- Department for Science, Innovation and Technology.
- Ipsos iris.
- Google first-party documentation for AI Mode and search-product behaviour.
Secondary SEO blogs, marketing round-ups and statistics aggregation pages were not treated as primary evidence where the original source could be identified.
Source principle: The underlying numerical statistic is attributed to the organisation that collected, measured or published the data.
Internet Usage Measures
Internet-access and frequency statistics in this report are based primarily on the UK Government’s Public Engagement Survey 2025/2026.
These figures measure self-reported internet use within defined periods.
They should not be interpreted as direct measures of search-engine activity.
Interpretation rule: Internet usage provides the broader digital context within which search behaviour occurs; it is not itself equivalent to search usage.
Search-Engine Usage
Search-engine usage figures come primarily from Ofcom’s media-use research and passive audience measurement reported through Ipsos iris.
These datasets can answer different questions:
- Whether people report using a search engine.
- How many people visit a search service.
- How many page views or interactions occur.
These measures are related but not interchangeable.
Measurement principle: Reach, visits, page views and searches should not be treated as identical metrics.
Google Search Volume
This report uses Ofcom’s estimate of approximately three billion Google searches per month in the UK.
Separate Ipsos iris data shows nearly nine billion Google Search page views among UK adults in October 2025.
These two figures measure different activities.
A page view is not necessarily equivalent to an individual search query.
Search-volume principle: The report does not convert search page views into estimated query counts.
Audience Reach
Several statistics use Ipsos iris audience measurement as reported by Ofcom.
These figures estimate the proportion or number of people using websites, applications or online services during a defined period.
Audience reach should not be interpreted as proof of a specific user intention.
For example, visiting ChatGPT does not establish that the user was conducting a search.
Audience principle: Platform reach indicates exposure or usage, not the purpose of every session.
Smartphone and Device Usage
Smartphone availability, app usage and online-time statistics describe the device environment within which search increasingly occurs.
They do not establish that all smartphone time is search activity.
The data is used to show why search behaviour increasingly occurs within mobile, app-based and location-aware environments.
Device principle: Mobile usage provides context for search behaviour; it should not be described as search usage unless the source measures search directly.
Maps and Local Discovery
Google Maps usage is treated as a form of local discovery infrastructure rather than conventional web search.
Maps can help users find businesses, locations, opening hours, reviews and directions without necessarily visiting a search-engine results page.
The report therefore includes Maps within the wider discovery ecosystem while keeping it methodologically distinct from web search.
Search Literacy and Trust
One of the most important source sets in this report comes from Ofcom’s Adults’ Media Use and Attitudes research.
This includes both:
- Self-reported confidence.
- Tested interpretation of search-result advertising.
These measures are intentionally kept separate.
A user may say they are confident recognising online advertising and still fail to identify sponsored search results correctly when tested.
Search-literacy principle: Perceived understanding and demonstrated understanding are different behaviours.
Generative AI Usage
AI adoption statistics in this report come from both Ofcom and DSIT.
Their methodologies and definitions are not identical.
For example, one study may ask broadly about AI-tool usage while another asks about specific categories of generative AI used within the previous three months.
These percentages should therefore not be presented as if they were directly comparable measurements of exactly the same behaviour.
AI adoption principle: Different AI-usage percentages are retained with their original definitions, survey populations and time periods.
AI Chatbot Audience Versus AI Search
Ofcom reports audience reach for major AI-chatbot platforms including ChatGPT, Gemini, Copilot and others.
These platforms support search and information discovery, but they are also used for:
- Writing.
- Brainstorming.
- Coding.
- Image creation.
- Summarisation.
- Work assistance.
For this reason, chatbot visitors are not labelled as AI-search users unless the underlying study measures search behaviour specifically.
AI-search principle: AI-chatbot reach and AI-search adoption are related but distinct measures.
AI Overviews
The report uses Ofcom evidence indicating that AI-generated Overviews appear across approximately 30% of searches and that substantial numbers of adults encounter or read generated search summaries.
These figures describe the prevalence and visibility of AI-generated search experiences.
They do not establish that every user trusts, clicks or acts upon the generated summary.
Google AI Mode Query Length
The statistic showing AI Mode questions at approximately two to three times the length of traditional queries originates from Google.
It is therefore first-party platform evidence.
The figure is useful for understanding behaviour within AI Mode, but it should not automatically be generalised to every AI-search interface or the entire UK population.
Platform-data principle: Behaviour reported within one product is described within the scope of that product unless independent evidence supports wider generalisation.
Trust and AI Accuracy
Public concern about AI-generated information is used in this report to understand the trust environment surrounding AI-assisted search.
Concern about inaccuracy does not prove that every user verifies AI answers, nor does it mean all AI-generated information is considered unreliable.
It demonstrates that trust remains a meaningful issue even as AI adoption increases.
Trust principle: Adoption and trust should be measured separately. High usage can coexist with significant concern.
Age Differences
Several statistics demonstrate material differences by age in:
- Smartphone access.
- AI adoption.
- App usage.
- Recognition of sponsored search results.
Age should therefore be treated as a relevant segmentation variable when interpreting search behaviour.
However, the findings also caution against simplistic assumptions that younger users always understand digital interfaces better than older users.
Correlation and Causation
The report identifies several trends occurring at the same time:
- High traditional search usage.
- Growing AI adoption.
- Increasing exposure to AI-generated search answers.
- Heavy smartphone usage.
- Strong concern about AI accuracy.
These relationships should not automatically be interpreted as direct causation.
For example, growth in ChatGPT usage does not by itself prove that conventional search usage has fallen by the same amount.
Interpretation principle: CGO Media distinguishes observed behavioural change from unsupported claims that one platform or technology has directly caused another to decline.
Research Limitations
The principal limitations of this report include:
- Different sources use different measurement periods.
- Some measures are self-reported while others are passively measured.
- Search reach, visits, page views and query volume are not identical metrics.
- AI-tool usage does not automatically equal AI-search usage.
- AI products and interfaces are changing rapidly.
- Platform companies may use proprietary measurement methodologies.
- Some search behaviours cannot be observed fully across closed apps or private sessions.
- User intent cannot always be inferred from platform usage alone.
- Audience behaviour differs materially by age and device.
- Forecast-style trend analysis is interpretive rather than guaranteed.
These limitations do not make the data unusable.
They define the boundaries within which the evidence should be interpreted.
CGO Media Search Behaviour Research Standard
CGO Media applies six principles when compiling search-behaviour statistics:
↓
Define the Behaviour Being Measured
↓
Identify Population, Device & Time Period
↓
Separate Reach from Intent
↓
Distinguish Evidence from CGO Media Analysis
↓
Avoid Unsupported Claims About Search Replacement
Search behaviour is especially vulnerable to oversimplification because conventional search, AI chatbots, maps, social discovery and ecommerce platforms increasingly overlap.
CGO Media therefore recommends preserving the original source definition, date, population and methodology whenever individual statistics from this report are quoted or reused.
Frequently Asked Questions — Search Behaviour Statistics UK 2026
The questions below address some of the most important issues surrounding UK search behaviour, Google Search, mobile discovery, AI Overviews, ChatGPT, conversational search, trust and changing information-retrieval behaviour in 2026.
The central finding is that search remains deeply embedded in UK digital behaviour, but the journey is becoming increasingly distributed across Google, mobile devices, maps, AI-generated answers and conversational assistants.
1. How widely used are search engines in the UK?
Search engines remain close to universal among UK online adults.
Ofcom’s 2026 research found that 96% of UK online adults had used a search engine during the previous 12 months.
Short answer: Search-engine usage remains extremely high, with 96% of UK online adults reporting use within the previous year.
2. How important is Google Search in the UK?
Google Search continues to operate at very large scale.
It reached 82% of UK online adults in May 2025, while Ofcom estimates that around three billion Google searches take place in the UK each month.
Ipsos iris also measured nearly nine billion Google Search page views among UK adults in October 2025.
Short answer: Google remains one of the UK’s dominant search and information-discovery platforms.
3. Is traditional search declining because of AI?
The available evidence does not support the idea that traditional search has disappeared or become marginal.
Google still processes billions of UK searches every month while AI functionality is increasingly being integrated into conventional search itself.
The clearer trend is convergence rather than straightforward replacement.
Short answer: AI is changing how search works, but conventional search remains heavily used.
4. What percentage of Google searches show AI Overviews?
Ofcom reports that approximately 30% of searches display an AI Overview.
These generated summaries can appear before traditional organic results and can answer parts of a query without requiring an immediate website visit.
Short answer: Around three in ten searches now display an AI-generated Overview according to Ofcom’s cited evidence.
5. How many UK adults encounter AI-generated search summaries?
Ofcom reports that 53% of UK adults say they often encounter AI-generated search summaries.
Its 2026 research also found that 75% of online adults read AI-generated search summaries at least sometimes.
Short answer: AI-generated search content has already become part of the mainstream search experience for a large majority of UK online adults.
6. How popular is ChatGPT in the UK?
ChatGPT reached approximately 13 million UK online adults in June 2025, equivalent to around 26% of the online adult population measured by Ipsos iris.
Ofcom also reports 1.8 billion UK ChatGPT visits during the first eight months of 2025.
These visits include activities beyond search, so they should not be described as 1.8 billion search queries.
Short answer: ChatGPT has developed a UK audience measured in the tens of millions and traffic measured in billions of visits.
7. Are people replacing Google with ChatGPT?
Some users are clearly using ChatGPT for information discovery, but the evidence does not establish a complete substitution of Google Search.
Users can move between both environments depending on the task.
A person may use ChatGPT for explanation or comparison and Google for maps, current sources, navigation or further verification.
Short answer: Search behaviour is becoming multi-platform rather than moving uniformly from Google to one AI assistant.
8. Are search queries becoming longer?
Within Google’s AI Mode, yes.
Google reports that early AI Mode questions are approximately two to three times longer than traditional search queries.
Conversational interfaces allow users to express more context, preferences and constraints within a single question.
Short answer: AI-assisted search encourages longer and more detailed questions than conventional keyword search.
9. How important are smartphones to search behaviour?
Smartphones are central to modern UK search behaviour.
93% of adults have access to a smartphone for personal use, and smartphones account for most measured personal online time.
One in five UK online adults also relies solely on a smartphone for internet access.
Short answer: Search is increasingly mobile by default rather than desktop-first.
10. How important is Google Maps for local search?
Google Maps reached 77% of UK adult smartphone users in Ofcom’s May 2025 measurement.
That gives it substantial importance for local discovery, navigation and business selection.
Users can evaluate businesses through location, reviews, opening hours and directions without beginning with a traditional web result.
Short answer: Maps is now a major search and discovery surface for local businesses.
11. Do users understand which Google results are advertisements?
Not always.
In Ofcom’s practical search test, only 52% of search-engine users correctly identified sponsored Google results as paid placements.
Some users instead associated the prominent positions with relevance or popularity.
Short answer: A substantial proportion of users do not clearly distinguish paid search placement from other reasons for prominence.
12. Do people automatically trust websites because they rank in search results?
No.
Only 17% of adults said they believed appearing in search results meant a website would contain accurate and unbiased information.
Most users recognised that some search results would be reliable while others would not.
Short answer: Search visibility earns attention, but it does not guarantee trust.
13. Are younger users better at understanding search results?
Not necessarily.
Ofcom’s sponsored-search test found a substantial gap between confidence and actual ability among younger adults.
47% of search users aged 25–34 were confident that they could identify advertising but failed to identify the sponsored results correctly.
Older groups performed comparatively well in recognising paid placement.
Short answer: Heavy digital usage does not automatically produce stronger search literacy.
14. Do UK consumers trust AI-generated information?
Trust is mixed.
AI adoption is high, but 74% of UK adults are concerned about inaccurate AI-generated information and 64% identify false or misleading information as a risk.
Ofcom also found that 57% of adults aware of AI would trust an AI-generated news story less than a human-written equivalent.
Short answer: Consumers are adopting AI quickly while remaining cautious about the reliability of generated information.
15. Why do people use AI for search and information discovery?
Convenience is an important factor.
47% of UK adults identified easier access to information or advice as a benefit of AI.
Among generative-AI users represented in DSIT’s online sample, 48% used AI to summarise or explain information.
Short answer: AI can reduce the work required to find, summarise and interpret information.
16. What should UK businesses prioritise for search visibility in 2026?
There is no single tactic suitable for every organisation, but the evidence supports several broad priorities:
- Maintain strong traditional SEO.
- Improve mobile usability.
- Strengthen local and Maps visibility where relevant.
- Answer conversational search intent.
- Publish credible, sourceable information.
- Improve entity clarity.
- Measure AI and multi-platform discovery where possible.
Short answer: Businesses should optimise for the broader discovery journey rather than relying on traditional rankings alone.
The Core Search Question for 2026
The traditional search question was often:
“Where do we rank in Google?”
The stronger question is:
“Where can our audience discover us, and why should they trust what they find?”
That question better reflects a search environment increasingly shaped by conventional rankings, maps, generated answers, conversational assistants and source verification.
Conclusion — Search Behaviour Statistics UK 2026
The evidence across the 50 statistics shows that search remains one of the most important digital behaviours in the UK, but the way people search is becoming more varied, more conversational and more distributed across platforms.
Google continues to dominate conventional search usage, smartphones now shape much of the search context, Maps has become a major local-discovery surface, and AI-generated answers are increasingly becoming part of mainstream search behaviour.
The most important change is therefore not the disappearance of search.
It is the expansion of search into a wider discovery ecosystem.
The defining feature of UK search behaviour in 2026 is convergence: conventional search, mobile discovery, Maps, AI Overviews and conversational assistants increasingly contribute to the same information journey.
Traditional Search Remains Fundamental
Search-engine usage remains close to universal among UK online adults.
Google continues to reach most of the online population and processes billions of searches every month.
That scale means traditional search remains essential for businesses seeking visibility.
Search Is Increasingly Mobile and Location-Aware
Smartphones account for most measured personal online time, and Google Maps reaches a large majority of adult smartphone users.
This means many search journeys now occur in real-world contexts involving location, proximity, reviews, navigation and immediate intent.
For local businesses, search visibility increasingly includes Maps and business-profile visibility alongside conventional rankings.
Users Interpret Search Results Differently
The research also shows that users do not always understand or interpret search results in the same way.
Some users associate prominent sponsored results with popularity or relevance, while many remain only partially able to distinguish paid placement from organic visibility.
This makes search behaviour partly a question of perception, not only ranking.
AI Is Expanding the Search Interface
AI-generated summaries are increasingly integrated into search engines, while standalone AI assistants have developed large UK audiences.
This adds a new layer to the search journey.
Users can now move between conventional search results, generated summaries and conversational answers without treating those experiences as entirely separate systems.
Search Is Becoming More Conversational
Longer AI-assisted queries allow users to describe what they want with more context.
That shifts optimisation away from isolated keywords and towards understanding:
- User needs.
- Attributes.
- Entities.
- Preferences.
- Decision criteria.
For businesses, this increases the value of detailed, well-structured information that answers real questions rather than simply repeating target keywords.
Search Is Shifting From Retrieval Towards Explanation
Generative AI changes the role of the search interface.
Instead of only helping users locate information, it can also summarise, explain and compare that information.
This means businesses increasingly compete not only to rank, but to become useful sources within generated answers.
Trust and Verification Remain Central
Consumers value the convenience of AI, but concern about inaccurate and misleading information remains high.
That makes authority, transparency and verification increasingly important.
Useful trust signals include:
- Original research.
- Named experts.
- Transparent methodology.
- Current publication dates.
- Primary evidence.
- Independent citations.
CGO Media conclusion: The strongest search strategies for 2026 are built around visibility, relevance and trust across conventional search, mobile discovery, Maps and AI-assisted search rather than focusing on keyword rankings alone.
Final Research Findings
Across the 50 search-behaviour statistics reviewed in this report, ten findings stand out:
- Search-engine usage remains close to universal among UK online adults.
- Google continues to operate at very large scale and processes billions of UK searches every month.
- Smartphones now shape most everyday search and discovery contexts.
- Google Maps has become a major local-discovery surface.
- Users do not always correctly distinguish paid search placement from organic prominence.
- Ranking visibility does not automatically create trust.
- AI-generated search summaries have entered mainstream search behaviour.
- ChatGPT and other AI assistants have developed substantial UK audiences.
- Conversational search is making queries longer and more detailed.
- The future of search increasingly depends on visibility, source authority and verifiability across multiple discovery environments.
+
Mobile & Maps
+
Conversational Queries
+
AI-Generated Answers
+
Source Authority
+
Verification
=
Modern Search Behaviour
The practical message for UK organisations is not to abandon SEO in favour of AI search.
It is to widen the definition of search visibility.
The organisations best positioned for the next stage of search will be those that can remain discoverable, understandable and trustworthy wherever users choose to search.
Research Usage, Citation & Press
CGO Media publishes search, AI and digital-behaviour research to support journalists, businesses, researchers, analysts and organisations examining how people discover, evaluate and verify information online.
The statistics and analysis contained within this report may be referenced in editorial coverage, academic work, industry research, presentations and commercial analysis, provided the original source and relevant research context are retained.
Recommended Citation
CGO Media Research Team (2026). Search Behaviour Statistics UK 2026: 50 Data Points on Google, AI Search, Search Intent & Online Discovery. CGO Media.
Using Individual Statistics
Where an individual statistic originates from Ofcom, Ipsos iris, the Department for Science, Innovation and Technology, Google or another external organisation, CGO Media recommends citing the original research as the primary source wherever practical.
CGO Media may be cited for the selection, organisation, comparison and interpretation of that evidence within the wider context of UK search behaviour.
Preferred citation approach: Attribute the numerical statistic to the organisation that produced the underlying data and attribute the wider interpretation or search-behaviour analysis to CGO Media.
Using CGO Media Analysis
The analytical sections of this report — including the Search Behaviour Model, practical recommendations, search trends and interpretation of the 50 statistics — represent CGO Media Research Team analysis.
Journalists, publishers and researchers may quote or summarise these findings with attribution to:
CGO Media Research Team
Search Behaviour Statistics UK 2026
cgomedia.com/search-behaviour-statistics-uk-2026/
Press & Media Enquiries
Journalists, editors, broadcasters, researchers and industry publications requiring additional commentary or clarification can use the dedicated CGO Media Press & Media area.
Relevant enquiry topics include:
- UK search behaviour.
- Google Search usage.
- AI Overviews.
- ChatGPT and conversational search.
- Search intent and user behaviour.
- Search-result trust.
- Mobile and local discovery.
- Google Maps.
- AI-generated answers.
- Search literacy.
- Source authority and verification.
- Future search behaviour.
Press & Media Resources
Access CGO Media research, press information, journalist resources and current research programmes.
Research Methodology
CGO Media publishes a dedicated Research Methodology explaining how sources are selected, checked and interpreted across the wider research programme.
The methodology addresses:
- Source selection.
- Primary versus secondary evidence.
- Audience measurement.
- Platform-reported data.
- Research limitations.
- Geographic context.
- Responsible interpretation.
View the CGO Media Research Methodology
Research Updates
Search behaviour is changing quickly.
Google interfaces, AI Overviews, conversational search products, AI-chatbot audiences, mobile behaviour and user attitudes can change materially over relatively short periods.
CGO Media therefore reviews search-behaviour evidence as new datasets and official research become available.
Readers quoting individual statistics should preserve the original date, population, geography and methodology of the underlying source.
Research principle: Search-behaviour statistics should be treated as dated evidence rather than permanent figures that remain unchanged as platforms and consumer behaviour evolve.
Editorial & Research Attribution
This report was prepared and reviewed by the CGO Media Research Team as part of CGO Media’s wider research programme examining search behaviour, SEO, GEO, AI search, source selection, entity authority, citation authority and changing digital discovery.
The report combines external evidence with CGO Media analysis to examine how UK search behaviour is changing across conventional search, mobile discovery, maps, AI-generated answers and conversational assistants.
Research, Press & Citation
↓
Clear Behavioural Definition
↓
Population & Platform Context
↓
Responsible Interpretation
↓
Journalist & Research Access
↓
Citable Search Behaviour Research
CGO Media’s objective is to make its search research useful not simply as online content, but as a transparent and referenceable evidence resource for journalists, researchers, businesses and organisations examining the future of search and digital discovery.
Sources & References
The Search Behaviour Statistics UK 2026 report draws primarily on Ofcom, Ipsos iris, the UK Department for Science, Innovation and Technology and first-party Google documentation.
CGO Media prioritised original research and official evidence rather than relying on third-party statistics pages where the underlying source could be identified.
Numerical statistics remain attributable to their original publishers. CGO Media’s contribution is the selection, organisation, comparison and interpretation of the evidence within the wider context of UK search behaviour and digital discovery.
1. Ofcom — Online Nation 2025
Publisher: Ofcom
Publication: Online Nation 2025
Geography: United Kingdom
Research area: Search, apps, mobile behaviour, maps and online audiences
This is one of the principal sources used throughout the report.
Relevant evidence includes:
- Google Search reach.
- Estimated monthly UK Google searches.
- Search use among children.
- Daily time spent online.
- Smartphone share of online time.
- Monthly app usage.
- Google Maps reach.
- ChatGPT traffic growth.
- AI Overview exposure.
Used principally in: Statistics 5–8, 13–18 and 31–34.
2. Ofcom — Adults’ Media Use and Attitudes 2026
Publisher: Ofcom
Publication: Adults’ Media Use and Attitudes 2026
Published: 2026
Geography: United Kingdom
Research area: Search literacy, media understanding, online trust and AI use
This source provides several of the strongest behavioural measures in the report because it includes both self-reported confidence and practical interpretation tests.
Relevant evidence includes:
- Search-engine use.
- Google Search page views.
- Recognition of sponsored search results.
- Perceptions of search-result accuracy.
- Confidence identifying online advertising.
- Confidence assessing whether information is true or false.
- Age differences in recognising paid search results.
- Smartphone-only internet access.
- AI-tool usage.
- Reading AI-generated search summaries.
- Confidence identifying AI-generated content.
- Trust in AI-generated news.
Used principally in: Statistics 4–5, 9–10, 20–30 and 41–44.
View Ofcom Adults’ Media Use and Attitudes
3. Ofcom — The Era of Answer Engines
Publisher: Ofcom
Publication: The Era of Answer Engines: Generative AI’s Impact on Search Experiences and Online Safety
Research area: AI chatbots, answer engines and changing search behaviour
The publication examines how generative AI is changing the way users search for, receive and interpret information online.
It includes Ipsos iris audience measurements for major AI chatbot services including:
- ChatGPT.
- Microsoft Copilot.
- Google Gemini.
- Perplexity.
- Claude.ai.
- DeepSeek.
- Grok.
Used principally in: Statistics 35–36 and analysis of answer-engine behaviour.
View Ofcom — The Era of Answer Engines
4. Ipsos iris — UK Online Audience Measurement
Research organisation: Ipsos
Dataset: Ipsos iris
Geography: United Kingdom
Ipsos iris provides passive audience measurement across websites and applications and is cited extensively by Ofcom.
It supports audience and usage figures relating to:
- Google Search.
- Google Maps.
- YouTube.
- ChatGPT.
- Other AI chatbot services.
- Smartphone and app usage.
CGO Media cites Ipsos iris through the corresponding Ofcom publications where those figures are reported.
Used principally in: Audience-reach, page-view, app and platform-usage statistics throughout the report.
5. Department for Science, Innovation and Technology — Public Engagement Survey 2025/2026
Publisher: UK Department for Science, Innovation and Technology
Publication: DSIT Public Engagement Survey 2025/2026
Published: 2026
Population: UK adults
The survey provides official UK evidence on internet use, devices, artificial intelligence adoption and attitudes towards AI.
Relevant evidence includes:
- Internet usage within the previous three months.
- Daily internet use.
- Internet use at home.
- Smartphone access.
- Age differences in smartphone access.
- 5G use.
- Generative-AI adoption.
- Age differences in AI usage.
- Frequency of AI use.
- AI use for summarising or explaining information.
- Concern about inaccurate AI information.
- Concern about misleading information.
- Concern about harmful AI-generated content.
- Perceived benefits of easier information access.
Used principally in: Statistics 1–3, 11–12, 19, 37–39 and 45–50.
View DSIT Public Engagement Survey 2025/2026
6. Google UK — AI Mode in Search
Publisher: Google UK
Publication: AI Mode in Search — UK Launch
Published: July 2025
Research area: Conversational search and query behaviour
Google’s first-party documentation is used to support discussion of how search behaviour changes inside AI Mode.
Google reported that early AI Mode users asked questions approximately two to three times longer than conventional search queries.
Used principally in: Statistic 40 and the analysis of conversational query behaviour.
View Google UK AI Mode Announcement
Source Hierarchy Used by CGO Media
CGO Media applied the following hierarchy when selecting evidence for this report:
↓
Independent Audience Measurement
↓
Regulator Research
↓
First-Party Platform Behavioural Data
↓
Supporting Industry Evidence
Unsourced SEO statistics pages, third-party round-ups and marketing claims were not treated as primary evidence where an original source could be identified.
Important Citation Note
Journalists and researchers citing an individual statistic should, wherever practical, reference the original organisation responsible for the data.
CGO Media should be cited where the material being referenced relates to:
- The organisation of the 50-statistic dataset.
- Comparison between different search behaviours.
- CGO Media analysis.
- The CGO Media Search Behaviour Model.
- Practical recommendations for organisations.
- Search Behaviour Trends UK 2026–2027.
This distinction preserves the integrity of the original evidence while allowing CGO Media’s synthesis and interpretation to be cited independently.
Research Review Date
Research reviewed: September 2026
Prepared by: CGO Media Research Team
Search behaviour, AI-search interfaces and generative-AI adoption remain fast-moving areas.
Statistics should therefore be reviewed periodically as new Ofcom, government, audience-measurement and platform evidence becomes available.
Research Integrity
The evidence in this report does not support the simplistic conclusion that AI has replaced conventional search.
It instead points towards a more complex discovery environment:
+
Mobile & Maps
+
AI Search
+
Conversational Assistants
+
Source Verification
=
Modern Search & Discovery Behaviour
CGO Media will continue reviewing this evidence as search platforms, AI systems and user behaviour develop.