CGO Media Research • updated: 28th september 2026
AI search is developing into a significant new layer of the global search ecosystem, but measuring its market share is considerably more complicated than comparing conventional search engines.
ChatGPT, Google Gemini, Microsoft Copilot, Claude, Perplexity and other AI systems now compete for information-seeking activity while Google simultaneously integrates generative AI directly into conventional Search through AI Overviews and AI Mode.
The result is not a simple replacement of one search market by another. Instead, users increasingly move between traditional search engines, standalone AI assistants, embedded AI features, social platforms, marketplaces and specialist information sources during the same discovery journey.
This report brings together the available evidence to examine the scale, growth and competitive structure of AI search in 2026 while carefully separating different definitions of market share.
Key Research Principle
There is no single authoritative percentage representing “AI search market share”. Platform traffic, audience reach, search-like activity, referral traffic, chatbot usage and conventional search-engine market share measure different behaviours and must be reported separately.
Executive Summary
The 2026 search market is characterised by two developments occurring simultaneously.
First, standalone generative AI platforms have reached substantial audiences. ChatGPT remains the most prominent standalone AI assistant across several major datasets, while Gemini, Claude, Perplexity and Microsoft Copilot contribute to an increasingly competitive AI platform environment.
Second, conventional web search remains enormous. Google continues to process search activity at a scale that standalone AI assistants have not yet replaced, while Google’s own AI features increasingly blur the boundary between traditional search and generative search.
For marketers, publishers, businesses and researchers, the important question is therefore no longer simply whether AI will replace search. The more immediate issue is how discovery activity is being redistributed across a growing number of search and answer environments.
Market Shift
Search is becoming a multi-platform discovery ecosystem.
AI Competition
ChatGPT leads a rapidly diversifying standalone AI market.
Traditional search and generative AI increasingly overlap.
Visibility
Market share alone does not measure AI visibility or citation opportunity.
What Is AI Search Market Share?
Traditional search-engine market share is generally estimated using measurable search referrals or search-engine activity. AI search introduces additional measurement problems because users can interact with generative systems through many different interfaces.
For example, a user may visit ChatGPT directly, use its mobile application, access an AI model through another application, receive an AI Overview within Google Search or interact with Gemini through Google’s wider ecosystem.
These interactions cannot automatically be combined into one comparable market-share figure.
Market Share Measures Used in This Report
- AI platform web traffic — visits to standalone generative AI websites.
- Audience reach — the proportion of a measured population using or visiting an AI service.
- AI chatbot market share — platform share within a defined chatbot measurement dataset.
- Search-like AI activity — AI interactions classified as information-seeking or search behaviour.
- Referral traffic — visits sent from AI systems to external websites.
- Traditional search-engine share — conventional search activity attributed to Google, Bing and other search engines.
- Embedded AI search — generative experiences such as Google AI Overviews and AI Mode operating inside existing search platforms.
Why Market Share Needs Careful Interpretation
Two credible research organisations can report very different percentages for the same AI platform without either figure necessarily being incorrect.
The apparent contradiction usually comes from differences in what is being measured: website visits, referral activity, active users, chatbot interactions, application usage or another defined behavioural dataset.
Geography matters as well. A worldwide platform-share statistic cannot automatically be treated as representative of UK behaviour. Likewise, US consumer research should not be described as evidence of UK consumer behaviour.
The reporting period is equally important because AI adoption and platform competition are changing quickly. Where possible, this report therefore states the source, population, geography, measurement type and reporting period associated with individual statistics.
A statistic describing 50% of generative AI website traffic does not mean that the platform controls 50% of the total search market.
Scope of the 2026 Report
AI Search Market Share Statistics 2026 examines the changing competitive structure of online search and discovery across the following areas:
- ChatGPT market position and growth.
- Google Gemini adoption and competitive growth.
- Claude, Perplexity and Microsoft Copilot.
- Generative AI website traffic.
- AI chatbot market-share datasets.
- Google Search’s continuing position within conventional search.
- Google AI Overviews and AI Mode.
- AI search versus conventional search activity.
- AI referral traffic to websites.
- UK AI search adoption and audience behaviour.
- Commercial discovery and research behaviour.
- AI citations and source selection.
- The implications of market fragmentation for SEO and GEO.
How to Read the Statistics
The statistics that follow combine evidence from audience measurement, web analytics, clickstream datasets, consumer research, search-result studies and first-party platform reporting.
Where CGO Media calculates a percentage, growth rate, ratio or difference directly from published source figures, the result will be identified as a CGO Media Calculation.
The purpose is not to force fundamentally different datasets into a single artificial market-share number. It is to build a more complete evidence-led picture of how AI is changing search behaviour, platform competition, website traffic and digital discovery.
AI Search Market Share Statistics 2026
Evidence-led analysis of ChatGPT, Google, Gemini, Claude, Perplexity, Copilot and the changing relationship between generative AI and traditional search.
Statistics 1–10
The AI Search Market in 2026
AI search has moved beyond the experimental stage. Standalone generative AI platforms now attract audiences measured in hundreds of millions or billions of visits, while generative features are simultaneously becoming embedded inside conventional search engines.
The first ten statistics establish the scale of this changing market. Because different datasets measure different forms of activity, each figure should be interpreted according to its stated measurement basis rather than treated as a percentage of all global searches.
1. ChatGPT accounted for approximately 53.9% of generative AI website visits in May 2026
53.9% — ChatGPT share of measured generative AI website visits worldwide.
Similarweb’s May 2026 analysis placed ChatGPT first among the major generative AI websites it measured. The figure refers to web visits within the generative AI category and is not ChatGPT’s share of the entire global search market.
2. Google Gemini captured approximately 27.9% of measured generative AI website visits
27.9% — Gemini’s share of measured generative AI website visits worldwide in May 2026.
Within the same Similarweb dataset, Gemini had developed into the largest individual challenger to ChatGPT by web traffic.
3. ChatGPT and Gemini together represented more than 80% of measured generative AI web visits
81.8% — combined ChatGPT and Gemini share.
Adding the published May 2026 shares for ChatGPT and Gemini produces a combined share of approximately 81.8% within the measured generative AI website category.
CGO Media Calculation: 53.9% + 27.9% = 81.8%.
4. Claude represented approximately 9.2% of measured generative AI website visits
9.2% — Claude’s measured worldwide generative AI web-traffic share in May 2026.
Claude remained considerably smaller than ChatGPT and Gemini in measured web visits, but its rapid growth gave Anthropic a material position within the standalone generative AI market.
5. Claude approached one billion monthly website visits
Approximately 953 million Claude website visits were recorded in May 2026.
Similarweb reported Claude growing from approximately 100 million visits in May 2025 to around 953 million one year later. The comparison demonstrates how quickly the competitive structure of standalone generative AI can change.
6. Claude’s measured website visits increased by more than nine times in one year
Approximately 9.5× — May 2026 visits compared with May 2025.
Using Similarweb’s approximately 100 million May 2025 visits and approximately 953 million May 2026 visits, Claude’s measured monthly web audience increased to around 9.5 times its previous level.
CGO Media Calculation based on published Similarweb visit figures.
7. ChatGPT’s share of generative AI web traffic has fallen as competitors have expanded
Approximately 79% in May 2025 versus 53.9% in May 2026.
The decline in share should not be interpreted as evidence that ChatGPT usage collapsed. It primarily illustrates that other generative AI platforms expanded rapidly enough to capture a greater proportion of the growing category.
8. ChatGPT lost approximately 25 percentage points of generative AI web-traffic share in one year
Approximately −25 percentage points between May 2025 and May 2026.
The shift provides evidence of market fragmentation. ChatGPT remained the largest measured platform, but its relative dominance declined as alternative AI systems attracted substantial traffic.
CGO Media Calculation based on Similarweb’s reported May 2025 and May 2026 shares.
9. Statcounter measured ChatGPT at 79.4% of worldwide AI chatbot market share in August 2026
79.4% — ChatGPT share within Statcounter’s worldwide AI chatbot dataset.
This percentage is much higher than ChatGPT’s share in Similarweb’s generative AI website-traffic analysis because Statcounter measures the market differently. The figures should therefore not be treated as competing estimates of an identical behaviour.
10. Gemini held 10.9% of Statcounter’s worldwide AI chatbot market in August 2026
10.9% — Gemini share within Statcounter’s worldwide AI chatbot dataset.
Gemini ranked second in the August 2026 dataset. Again, this measurement should remain separate from Similarweb’s generative AI web-traffic figures because the underlying methodologies are different.
What Statistics 1–10 Tell Us
The clearest conclusion from the opening statistics is not that one platform has a universally agreed AI search market share. It is that standalone generative AI has developed into a substantial and increasingly competitive digital category.
ChatGPT remains the largest individual platform across the datasets examined here, but the market around it is becoming less concentrated. Gemini has developed into a major competitor, while Claude’s growth demonstrates that substantial changes in platform usage can occur within a relatively short period.
The difference between Similarweb and Statcounter also illustrates one of the central methodological issues surrounding AI market-share reporting. A platform can account for 53.9% in one credible dataset and 79.4% in another because the datasets are measuring different behaviours.
The correct interpretation is not “ChatGPT has 53.9% or 79.4% of all search”. The correct interpretation is that ChatGPT holds different shares of different measurable AI activity datasets.
Evidence Notes for Statistics 1–10
The principal evidence in this section comes from Similarweb’s analysis of worldwide generative AI website traffic and Statcounter’s AI chatbot market-share dataset.
Similarweb’s figures measure web traffic to generative AI destinations. Statcounter’s figures use a different measurement framework. Neither should be presented as though it represents the proportion of every information search, prompt or query performed worldwide.
The statistics are therefore retained as separate indicators of competitive position rather than merged into a single CGO Media market-share estimate.
Statistics 11–20
Google Search vs AI Search: How Big Is the Shift?
The rapid growth of ChatGPT and other generative AI platforms has created a widespread perception that conventional search is being replaced. The available evidence presents a more complex picture.
AI-assisted information seeking is expanding rapidly, but Google continues to operate at enormous scale. At the same time, Google is incorporating generative AI directly into Search, making the boundary between “traditional search” and “AI search” increasingly difficult to define.
11. Google held approximately 91.1% of worldwide search-engine market share in August 2026
91.1% — Google’s measured worldwide conventional search-engine share.
Statcounter continued to record Google as overwhelmingly dominant within conventional search-engine activity in August 2026. The figure demonstrates why growth in standalone AI platforms should not automatically be interpreted as the disappearance of Google Search.
12. Bing held approximately 4.5% of worldwide conventional search-engine market share
4.5% — Bing’s worldwide search-engine share in August 2026.
Despite Microsoft’s integration of Copilot and generative AI technology across its ecosystem, Bing remained substantially smaller than Google within Statcounter’s conventional search-engine dataset.
13. Google was approximately 20 times larger than Bing by measured worldwide search-engine share
Approximately 20.2× — Google’s measured share compared with Bing.
Using Statcounter’s August 2026 figures of approximately 91.1% for Google and 4.5% for Bing, Google’s conventional search-engine share remained more than twenty times larger.
CGO Media Calculation: 91.1 ÷ 4.5 ≈ 20.2.
14. Google accounted for nearly 40% of measured website traffic in an Ahrefs study
Nearly 40% — Google’s share of traffic across approximately 76,000 websites analysed by Ahrefs.
This dataset measures website traffic rather than search-engine market share. It provides another perspective on the continuing importance of Google as a source of external website visits.
15. ChatGPT accounted for approximately 0.21% of website traffic in the same Ahrefs dataset
Approximately 0.21% — measured website traffic attributed to ChatGPT.
The figure illustrates an important distinction between AI usage and outbound traffic. A user can obtain substantial information from an AI response without visiting the websites used to construct or support that response.
16. Google sent approximately 190 times more traffic to websites than ChatGPT
Approximately 190× — Google traffic compared with ChatGPT traffic in the Ahrefs dataset.
Ahrefs’ analysis demonstrates that search activity and referral traffic are not equivalent measurements. ChatGPT may be used extensively for information retrieval while still sending substantially less external website traffic than Google.
17. Approximately 65% of ChatGPT usage was classified as search or search-like activity by Ahrefs
Approximately 65% — ChatGPT activity classified as search or search-like.
This estimate is significant because not every ChatGPT interaction represents search. Users also employ the platform for writing, coding, analysis, summarisation, brainstorming and other tasks.
18. ChatGPT’s estimated search-like activity equated to approximately 11.86% of Google’s search volume under Ahrefs’ methodology
11.86% — estimated ChatGPT search-like volume relative to Google.
This is an analytical estimate rather than a universal market-share measurement. It nevertheless provides useful context for the relative scale of ChatGPT information-seeking activity compared with Google Search.
19. AI Overviews exceeded 2.5 billion monthly active users globally
More than 2.5 billion monthly active users — Google AI Overviews.
Google’s first-party reporting demonstrates that generative search is not limited to standalone AI platforms. AI-generated answers now operate at enormous scale inside the world’s dominant conventional search ecosystem.
20. Google AI Mode exceeded one billion monthly active users
More than 1 billion monthly active users — Google AI Mode.
Google’s reported AI Mode scale reinforces the difficulty of separating the conventional search market from the AI search market. Generative search is increasingly becoming a feature of Google Search itself rather than an entirely separate competitor to it.
AI Search Is Growing Alongside Google, Not Simply Replacing It
Statistics 11–20 challenge the idea that the search market can be divided neatly into “Google” on one side and “AI search” on the other.
Standalone AI assistants are clearly becoming significant information-discovery platforms. However, conventional Google Search remains vastly larger as a source of website traffic, while Google itself is integrating generative AI into the search experience at billion-user scale.
This creates an important measurement problem. A search completed through a Google AI Overview or AI Mode is simultaneously part of Google’s ecosystem and part of the broader transition towards generative search.
The future of search is increasingly hybrid: conventional rankings, AI-generated answers, citations, conversational follow-up and external website discovery can all exist within the same search journey.
What This Means for Search Visibility
For organisations, the evidence suggests that abandoning conventional SEO in favour of AI optimisation would misunderstand the current market.
Google continues to generate substantial discovery and website traffic. At the same time, visibility increasingly depends on whether information can also be understood, selected, cited and recommended within generative systems.
SEO and Generative Engine Optimisation therefore increasingly operate as connected disciplines. Traditional rankings remain commercially important, while entity authority, source eligibility, citation visibility and recommendation confidence become additional dimensions of search performance.
Evidence Sources for Statistics 11–20
This section combines three different forms of evidence: Statcounter conventional search-engine share, Ahrefs website-traffic and search-volume analysis, and Google’s first-party reporting on AI Overviews and AI Mode.
View Statcounter Worldwide Search Engine Market Share
View Ahrefs ChatGPT vs Google Analysis
Statistics 21–30
UK AI Search Adoption & Changing Search Behaviour
Worldwide platform statistics establish the scale of generative AI, but they do not tell us how extensively people in the United Kingdom are actually using AI tools or how those tools compare with established search behaviour.
UK evidence from Ofcom and Ipsos iris shows substantial adoption of AI assistants alongside continued heavy use of Google and conventional online search. The evidence therefore points towards expansion of the discovery ecosystem rather than a simple transfer of users from one search channel to another.
21. 54% of UK adults report using AI tools such as ChatGPT, Copilot or Gemini
54% — more than half of UK adults say they use AI tools.
Ofcom’s Adults’ Media Use and Attitudes 2026 research found that AI-tool usage has reached a majority of UK adults. The measure covers broader AI usage and should not be interpreted as meaning that 54% of UK adults have replaced conventional search with AI.
22. AI-tool usage reaches 79% among UK adults aged 16–24
79% — AI-tool adoption among UK 16–24-year-olds.
The age difference is significant for the future structure of search and discovery. Younger adults are already substantially more likely than the overall adult population to use generative AI tools.
23. 74% of UK adults aged 25–34 use AI tools
74% — reported AI-tool usage among UK adults aged 25–34.
High adoption among both 16–24 and 25–34-year-olds indicates that generative AI has already become a mainstream digital behaviour within younger UK adult populations.
24. 15.8 million UK online adults visited at least one major AI chatbot in June 2025
15.8 million UK online adults — measured audience for major AI chatbots.
Ipsos iris audience measurement cited by Ofcom found that almost sixteen million UK online adults visited at least one of the major measured AI chatbot services during June 2025.
25. Major AI chatbots reached 32% of UK online adults
32% — UK online adult reach in June 2025.
The audience measurement provides a narrower measure than Ofcom’s broader AI-tool usage statistic. This distinction demonstrates why survey adoption and measured chatbot visitation should not be treated as equivalent indicators.
26. ChatGPT reached 13 million UK online adults in June 2025
13.0 million — ChatGPT’s measured UK online adult audience.
Ofcom’s reporting of Ipsos iris data identified ChatGPT as having substantially greater UK audience reach than the other standalone AI assistants measured at the time.
27. ChatGPT reached 26% of UK online adults
26% — ChatGPT’s measured UK online adult reach in June 2025.
The figure establishes ChatGPT as a major UK digital platform, while also showing that direct usage had not approached the near-universal reach associated with conventional online information search.
28. UK users generated approximately 1.8 billion ChatGPT visits during the first eight months of 2025
1.8 billion — UK ChatGPT visits during the first eight months of 2025.
Ofcom’s Online Nation 2025 reported a dramatic expansion in ChatGPT visitation compared with the equivalent period a year earlier.
29. The equivalent UK ChatGPT visit figure was approximately 368 million in 2024
Approximately 368 million visits — equivalent first-eight-month period of 2024.
The comparison provides one of the clearest measures of how quickly ChatGPT usage expanded within the UK over a relatively short period.
30. UK ChatGPT visits increased by approximately 389% between the comparable 2024 and 2025 periods
Approximately +389% — growth from 368 million to 1.8 billion visits.
Using the Ofcom figures for the first eight months of 2024 and 2025, UK ChatGPT visitation increased to almost five times its previous level.
CGO Media Calculation: ((1.8 billion − 368 million) ÷ 368 million) × 100 ≈ 389%.
What the UK Data Shows
The UK evidence demonstrates that generative AI adoption is no longer confined to a small group of early adopters. More than half of adults report using AI tools, while adoption among younger adults is considerably higher.
ChatGPT has also established a particularly strong position. Its measured UK audience reached 13 million online adults by June 2025, while total UK visits expanded dramatically during the first eight months of that year.
However, the statistics describe different behaviours. Ofcom’s 54% figure measures reported use of AI tools generally. The 32% figure measures visits to major AI chatbots among UK online adults. The 26% figure measures ChatGPT’s audience reach specifically.
They should therefore be understood as complementary indicators of adoption rather than competing estimates of a single UK AI search market share.
The UK market has moved beyond the question of whether consumers will adopt generative AI. The more important question is how AI usage will redistribute information discovery, research and commercial search behaviour across platforms.
AI Growth Does Not Mean Google Has Disappeared
The growth rates above are substantial, but they need to be viewed alongside the continuing scale of conventional search.
Ofcom’s Online Nation 2025 reported Google Search being used by 82% of UK adults and estimated approximately three billion UK Google searches per month.
It also reported that 95% of UK adult internet users had searched online for information during the preceding three months.
The evidence therefore supports a picture of coexistence: AI assistants are gaining substantial audiences and usage while conventional search remains deeply embedded in UK digital behaviour.
Important Market-Share Distinction
Rapid growth in ChatGPT visits does not mean that the same proportion of Google searches has migrated to ChatGPT. Visits, audience reach, searches, prompts and AI-tool adoption are different measurements. The UK evidence should not be combined into an unsupported single “AI vs Google” percentage.
What UK Adoption Means for Businesses
The UK data suggests that organisations increasingly need to think about search visibility across more than one discovery environment.
A potential customer may begin with Google, encounter an AI Overview, continue research through ChatGPT or Gemini, compare alternatives, return to conventional search and finally visit a business directly.
This makes the relationship between traditional SEO, entity authority, content quality, brand signals, citations and Generative Engine Optimisation increasingly important. Visibility needs to persist across the discovery journey rather than depend on a single ranking or platform.
Evidence Sources for Statistics 21–30
The principal evidence for this section comes from Ofcom’s Adults’ Media Use and Attitudes 2026, Ofcom’s research into the emergence of answer engines, Ipsos iris audience measurement cited by Ofcom, and Online Nation 2025.
View Ofcom Adults’ Media Use and Attitudes 2026
Statistics 31–40
AI Search Clicks, Referrals & the Changing Economics of Website Traffic
Market share measures how audiences are distributed between platforms. For businesses and publishers, however, another question is equally important: what happens after a user receives an AI-generated answer?
Research into Google AI Overviews, ChatGPT referrals and AI citation behaviour indicates that generative search can change the relationship between visibility and website traffic. A brand or source may influence an answer without receiving the type of click traditionally associated with organic search.
31. AI summaries appeared on 18% of Google searches measured by Pew Research Center
18% — share of measured Google searches producing an AI summary.
Pew Research Center examined 68,879 unique Google searches performed by 900 US adults. The result describes the searches within that study and should not be transferred directly to UK search behaviour or interpreted as a universal Google AI Overview prevalence rate.
32. 58% of participants encountered at least one Google AI summary during the study month
58% — participants exposed to at least one AI-generated summary.
AI summaries therefore affected a majority of the measured participants even though they appeared on a minority of total searches within the dataset.
33. Traditional search-result links received clicks on 8% of visits when an AI summary appeared
8% — traditional-result click rate on visits containing an AI summary.
The Pew behavioural data found that users were less likely to click a conventional search result when an AI-generated summary was present.
34. Traditional search-result links received clicks on 15% of visits without an AI summary
15% — traditional-result click rate when no AI summary appeared.
The difference between the 8% and 15% figures illustrates how an AI-generated answer can alter the user’s interaction with the rest of the search-results page.
35. Traditional-result clicking was approximately 47% lower when an AI summary appeared
Approximately −46.7% — relative difference between the measured 15% and 8% click rates.
This calculation describes the difference observed within Pew’s study. It should not be interpreted as evidence that every website will lose approximately 47% of its organic traffic when an AI Overview appears.
CGO Media Calculation: ((15 − 8) ÷ 15) × 100 ≈ 46.7%.
36. Only 1% of visits containing an AI summary produced a click on a cited source
1% — measured click rate on links cited directly within AI summaries.
This is one of the most important differences between traditional search visibility and generative visibility. A source may contribute information to an AI-generated answer without receiving a corresponding website visit.
37. 26% of browsing sessions ended after a search-results page containing an AI summary
26% — session-ending rate after an AI-summary page.
Pew found that users were more likely to end their browsing session after encountering an AI summary than after a results page without one.
38. 16% of sessions ended after search-results pages without an AI summary
16% — session-ending rate without an AI summary.
The ten-percentage-point difference is consistent with the possibility that AI-generated summaries can satisfy some information needs directly on the results page.
39. Ahrefs estimated a 58% reduction in position-one CTR when AI Overviews were present
−58% — estimated position-one organic CTR effect associated with AI Overviews.
Ahrefs analysed 300,000 informational keywords, split between 150,000 keywords with an AI Overview and 150,000 without one.
The result represents an estimated relationship within the study’s keyword sample. It should not be interpreted as a guaranteed 58% traffic loss for every position-one ranking.
40. AI Overview CTR effects extended throughout Google’s organic top ten
−50.8% at position two and −19.4% at position ten in Ahrefs’ estimates.
The analysis suggests that the potential click effect of AI-generated search experiences is not restricted to the first organic result. However, the estimated effect became smaller further down the ranking positions.
Visibility and Traffic Are Becoming Different Measurements
Traditional SEO developed around a relatively clear sequence: a search was performed, results were displayed, a ranking attracted a click and the user arrived on a website.
Generative search introduces another possibility. A search platform can retrieve information from multiple sources, synthesise an answer and satisfy much of the user’s information requirement before an external website is visited.
This does not make source visibility irrelevant. It changes what visibility can mean. A source can contribute to an AI answer, appear as a citation, influence a recommendation or reinforce a brand without necessarily producing an immediate click.
In AI search, being selected as a source and receiving a website visit are no longer necessarily the same event.
The Commercial Implication
If AI-generated answers reduce the need to click through for some informational searches, organisations may need to evaluate search performance using a broader set of indicators.
Organic sessions and click-through rates remain important, particularly for transactional and commercially valuable journeys. But they may no longer describe the complete influence of search visibility.
Additional indicators can include AI citations, brand mentions, recommendation visibility, source selection, branded-search growth, direct traffic, assisted conversions and whether an organisation appears during AI-mediated comparison and research.
The strategic objective therefore expands from generating rankings and clicks to maintaining visibility throughout a search ecosystem in which some discovery takes place before the user reaches a website.
Research Limitation
The Pew research was conducted using browsing behaviour from 900 US adults and should not be described as representative of UK search behaviour. The Ahrefs study used a large informational-keyword dataset but likewise does not establish a universal CTR effect for every industry, query type, country or search-results configuration.
Evidence Sources for Statistics 31–40
The primary evidence comes from Pew Research Center’s analysis of Google search behaviour and Ahrefs’ large-scale comparison of informational keywords with and without AI Overviews.
View Pew Research Center — Google AI Summaries & Click Behaviour
Statistics 41–50
AI Citations, Brand Mentions & Source Selection
As AI search grows, market share alone cannot explain which organisations actually gain visibility inside generated answers. Citation selection, brand mentions, source eligibility and retrieval behaviour create another competitive layer within the AI search ecosystem.
Research from Semrush and Ahrefs demonstrates that being cited by an AI system is not the same as being mentioned as a brand, while conventional Google rankings do not fully determine which pages or domains AI systems select as sources.
41. 61.7% of measured AI citations were “ghost citations”
61.7% — citations where the source was cited without the brand being mentioned.
Semrush and Kevin Indig analysed 3,981 domain appearances across 115 prompts and 14 countries. The research covered ChatGPT, Google AI Overviews, Google AI Mode and Gemini.
42. 74.9% of measured AI appearances contained a citation
74.9% — appearances containing a citation.
The result demonstrates the importance of source selection within generative search. AI visibility can occur through a citation even when the organisation itself is not explicitly named in the generated response.
43. Only 38.3% of measured appearances contained a brand mention
38.3% — appearances containing an explicit brand mention.
Citation visibility and brand visibility therefore represent different outcomes. An organisation can supply information used by an AI system without receiving an explicit brand mention in the resulting answer.
44. Only 13.2% of measured appearances contained both a citation and a brand mention
13.2% — appearances combining source citation with explicit brand recognition.
This distinction matters commercially because citation eligibility alone does not guarantee that users will associate the information with the organisation that supplied it.
45. ChatGPT cited sources in 87% of measured appearances but mentioned brands in only 20.7%
87% citation rate versus 20.7% brand-mention rate.
Within the Semrush study, ChatGPT demonstrated a particularly large difference between citing a source and explicitly mentioning the source’s brand.
46. Gemini mentioned brands in 83.7% of measured appearances but cited sources in 21.4%
83.7% brand-mention rate versus 21.4% citation rate.
The contrast with ChatGPT demonstrates why AI visibility cannot be measured identically across platforms. Different systems can expose brands and supporting sources in very different ways.
47. Comparative content generated 2.4 times more brand mentions than informational content
2.4× — brand mentions associated with comparative content relative to informational content.
Within the measured prompt set, comparison-oriented content was substantially more strongly associated with brand mentions. This supports the distinction between simply supplying information and becoming part of an AI-generated recommendation or comparison.
48. Only approximately 12% of AI-cited URLs ranked in Google’s top ten for the original prompt
Approximately 12% — average overlap between AI-cited URLs and Google’s top ten.
Ahrefs analysed 15,000 prompts and compared citations from AI assistants with conventional Google and Bing rankings.
The result indicates that strong conventional rankings and AI citation selection overlap only partially when the exact URL is compared against the original prompt.
49. AI-cited URLs showed approximately 10% overlap with Bing’s top ten
Approximately 10% — average overlap between AI citations and Bing’s top ten.
The low overlap with both Google and Bing suggests that AI source-selection systems cannot be understood simply as reproducing the conventional organic rankings for the same prompt.
50. 37.1% of Google AI Overview citations ranked in the conventional organic top ten
37.1% — cited URLs also ranking in Google’s organic top ten for the same query.
A separate Ahrefs analysis covering approximately 863,000 keyword SERPs and four million AI Overview URLs found considerably greater overlap between Google AI Overview citations and Google’s own organic results.
However, 26.2% of cited URLs ranked between positions 11 and 100, while 36.7% did not rank within the organic top 100 for the same query. Strong rankings therefore appear relevant to citation selection without being an absolute requirement.
AI Visibility Is More Than Being Cited
Statistics 41–50 reveal an important distinction between source authority and brand visibility.
A website can provide information that an AI system considers useful enough to cite without the organisation being named prominently in the answer. Conversely, a brand can be mentioned during a recommendation or comparison without its own website necessarily being presented as the supporting citation.
This creates at least two distinct forms of generative visibility: citation visibility, where a source is selected as evidence, and brand visibility, where an organisation becomes part of the generated answer itself.
For commercially important prompts, the strongest outcome may be achieving both: being recognised as a relevant entity while also possessing authoritative content that can support the recommendation.
AI visibility is not one metric. Citation visibility, brand mentions, recommendation inclusion and referral traffic represent different outcomes within the generative search journey.
AI Citation Selection Is Not the Same as Organic Ranking
The Ahrefs evidence also challenges the assumption that AI systems simply select the pages already ranking highest in conventional search.
Only around 12% average exact-URL overlap was observed between AI citations and Google’s top ten in the 15,000-prompt study. Google AI Overviews showed a stronger relationship with Google’s own rankings, but even there more than one-third of cited URLs did not rank within the organic top 100 for the same query.
This does not mean that conventional SEO is unimportant. Rankings can reflect many of the same underlying signals that make a source useful: topical relevance, authority, crawlability, content quality, entity clarity and external validation.
The evidence instead suggests that AI retrieval and citation introduce an additional selection layer. Organisations may therefore need to optimise not only for ranking eligibility but also for source eligibility.
The GEO Implication
Generative Engine Optimisation extends the visibility question beyond “Does this page rank?” towards additional questions:
- Can an AI system clearly identify the organisation and its entities?
- Is the content relevant enough to be retrieved for the user’s scenario?
- Does the source contain evidence that can support an answer?
- Is the information corroborated by authoritative external sources?
- Can the organisation be associated with the category, service, product or expertise being discussed?
- Is the brand likely to appear when AI systems compare or recommend alternatives?
- Can the underlying page become eligible for citation even when it does not hold the highest conventional ranking?
Research Limitation
These studies analyse defined prompt sets, platforms and search-result datasets. They should not be interpreted as proving that the same citation or brand-mention rates apply across every industry, country or query.
AI systems also change rapidly. Citation behaviour observed during one research period may shift as models, retrieval systems, interfaces and search integrations are updated.
Evidence Sources for Statistics 41–50
The primary evidence in this section comes from Semrush research into the relationship between citations and brand mentions, together with Ahrefs studies comparing AI citations with conventional Google and Bing rankings.
View Semrush — Ghost Citations Study
Statistics 51–60
ChatGPT Retrieval, Reasoning, Query Fan-Out & Source Diversity
AI search does not necessarily process a user’s prompt as a single conventional search query. Generative systems can interpret the request, break it into additional searches, retrieve information from multiple sources and construct an answer from the resulting evidence.
Research into ChatGPT reasoning behaviour demonstrates how significantly this retrieval process can change depending on the reasoning configuration. Greater reasoning depth can produce more searches, more citations and a wider source pool — while also changing which domains ultimately appear in the answer.
51. ChatGPT’s citation rate increased from 50% to 68% under higher reasoning
50% to 68% — citation rate across the two measured reasoning configurations.
Semrush and Kevin Indig tested 100 prompts across 20 buyer journeys using minimal- and high-reasoning configurations. Higher reasoning was associated with a greater likelihood of the response containing citations.
52. The measured citation rate increased by 18 percentage points
+18 percentage points — difference between the 50% and 68% citation rates.
The difference illustrates how the same underlying prompt can generate different citation behaviour when the reasoning process changes.
CGO Media Calculation: 68% − 50% = 18 percentage points.
53. Average citations per response increased from 2.6 to 4.5
2.6 to 4.5 — average citations per response.
Higher reasoning did not simply increase the probability of receiving a citation. It also increased the average number of citations appearing within the generated response.
54. Average citations per response increased by approximately 73%
Approximately +73.1% — increase from 2.6 to 4.5 citations.
The calculation provides another indication that reasoning depth can materially alter the amount of external evidence incorporated into an AI-generated response.
CGO Media Calculation: ((4.5 − 2.6) ÷ 2.6) × 100 ≈ 73.1%.
55. ChatGPT query fan-out increased 4.6 times under higher reasoning
4.6× — increase in fan-out queries.
Query fan-out describes the additional searches or retrieval actions generated as the system investigates different parts of the user’s request. Higher reasoning substantially expanded this search activity within the study.
56. Minimal reasoning generated 245 web searches across the tested prompts
245 web searches — minimal-reasoning configuration.
Even the lower-reasoning configuration performed substantially more than one retrieval action for every tested prompt on average, demonstrating why a generative prompt should not automatically be treated as equivalent to one traditional keyword query.
57. High reasoning generated 1,130 web searches across the same test
1,130 web searches — high-reasoning configuration.
The increase from 245 to 1,130 web searches shows how dramatically deeper reasoning can expand the retrieval landscape surrounding the same set of buyer-journey prompts.
58. Only 25.6% of cited domains overlapped between minimal and high reasoning
25.6% — overlap between cited domains across reasoning modes.
This is particularly important for AI visibility measurement. A domain cited when ChatGPT uses one reasoning configuration may not necessarily appear when the system approaches the same buyer journey with greater reasoning depth.
59. High reasoning drew citations from 173 unique domains
173 unique domains — high-reasoning source pool.
Minimal reasoning drew from 127 unique domains. The higher-reasoning configuration therefore accessed a substantially broader citation pool.
Study comparison: 173 unique domains under high reasoning versus 127 under minimal reasoning.
60. 99 domains appeared under high reasoning that did not appear under minimal reasoning
99 domains — additional source opportunities appearing only in the high-reasoning configuration.
The finding demonstrates that deeper AI research can expose an entirely different group of sources. Visibility for one prompt formulation or reasoning configuration therefore cannot guarantee visibility across every version of an AI-generated journey.
One Prompt Can Create an Entire Search Journey
Conventional keyword analysis often begins with the assumption that one user query corresponds broadly to one search-results page.
Generative AI can operate differently. A complex prompt can trigger multiple retrieval actions as the system investigates products, organisations, attributes, evidence, comparisons and supporting information before constructing its response.
This means an organisation may become visible through a secondary or tertiary retrieval path even when it is not the obvious source for the user’s original wording.
Conversely, ranking strongly for the obvious keyword does not guarantee that the organisation will survive every stage of a deeper AI research process.
Generative search expands the unit of competition from the individual keyword towards the complete information environment surrounding a topic, entity, problem or decision.
Reasoning Depth Changes the Competitive Source Set
The 25.6% domain overlap between reasoning modes is one of the most significant findings in this section.
It suggests that AI citation visibility can be more dynamic than a conventional fixed ranking position. Changes in reasoning depth can alter the searches performed, the sources encountered and the evidence ultimately selected.
For organisations measuring GEO performance, this creates a methodological challenge. Testing one prompt once cannot establish whether a brand has durable generative visibility.
More robust measurement may require repeated testing across prompt variants, user scenarios, reasoning depths, platforms and stages of the buyer journey.
The GEO Implication
Query fan-out means organisations should think beyond optimising one page for one exact prompt.
- Build strong topical coverage around the entity and subject.
- Answer the supporting questions that may emerge during deeper research.
- Provide evidence that can support comparisons and recommendations.
- Make products, services, expertise and organisational relationships explicit.
- Strengthen external corroboration across independent authoritative sources.
- Maintain content that can be retrieved at different stages of a research journey.
- Measure visibility across multiple prompts rather than relying on a single test.
Research Limitation
The study tested 100 prompts across 20 buyer journeys. Its results demonstrate substantial differences between the reasoning configurations examined but should not be interpreted as universal citation rates or retrieval patterns for every ChatGPT prompt.
Reasoning systems, retrieval methods and product interfaces can also change. These statistics should therefore be treated as evidence of how reasoning depth can affect retrieval and source selection rather than as permanent platform constants.
Evidence Source for Statistics 51–60
The principal evidence comes from Semrush and Kevin Indig’s 2026 research comparing ChatGPT’s minimal- and high-reasoning configurations across 100 prompts and 20 buyer journeys.
Statistics 61–70
AI Citation Freshness, Content Recency & Source Eligibility
The rapid development of AI systems, products, research and markets creates another factor that can influence source selection: freshness. Information that was authoritative several years ago may remain historically valuable while becoming less useful for answering a current question.
Large-scale Ahrefs research across approximately 17 million citations from seven AI platforms found that AI systems tended to cite fresher content than conventional Google organic results. The evidence does not establish freshness as a universal ranking factor, but it indicates that recency can form part of the competitive environment for AI citation visibility.
61. AI-cited content was approximately 25.7% fresher than Google organic content
25.7% fresher — average difference identified in Ahrefs’ large-scale citation analysis.
The study compared the freshness of content cited by AI systems with content appearing in conventional Google organic results. Across the analysed dataset, AI citations skewed towards more recently published or updated material.
62. The freshness study analysed approximately 17 million AI citations
Approximately 17 million citations — large-scale AI source dataset.
The scale of the dataset makes the observed freshness difference notable, although the results should still be interpreted according to the platforms, prompts and methodology included in the study.
63. The citation-freshness research covered seven AI platforms
7 AI platforms — citation behaviour examined across multiple generative environments.
The multi-platform methodology matters because source-selection behaviour is not necessarily identical across AI systems. A broader dataset can reveal patterns that may be less visible when examining only one assistant.
64. ChatGPT’s in-text reference URLs were approximately 393 days newer
Approximately 393 days newer — ChatGPT in-text references compared with corresponding Google organic content.
Within the Ahrefs analysis, URLs appearing as ChatGPT in-text references showed a substantial freshness difference relative to conventional Google organic results.
65. ChatGPT citation URLs were approximately 458 days newer
Approximately 458 days newer — ChatGPT citation URLs compared with corresponding Google organic content.
This represents a freshness gap of more than a year and provides further evidence that recently maintained material can feature prominently within AI source-selection environments.
66. ChatGPT citation URLs showed a 65-day larger freshness gap than its in-text references
65 days — difference between the reported 458-day and 393-day freshness gaps.
The calculation illustrates that the two types of ChatGPT source exposure examined in the research were not identical in their observed freshness relationship.
CGO Media Calculation: 458 days − 393 days = 65 days.
67. More than one-third of Google AI Overview citations can come from pages outside Google’s organic top 100
36.7% — AI Overview citation URLs not ranking within the organic top 100 for the same query.
This separate Ahrefs dataset reinforces the concept of source eligibility. Conventional ranking position can matter, but it does not fully define the pool of pages available for generative citation.
68. 26.2% of Google AI Overview citations came from pages ranking between positions 11 and 100
26.2% — citation URLs ranking outside Google’s organic top ten but within the top 100.
These pages had conventional search visibility but were not first-page organic results. Their inclusion as AI Overview citations further demonstrates that generative source selection can reach beyond the traditional top-ten result set.
69. 62.9% of AI Overview citations came from URLs outside Google’s organic top ten
62.9% — combined share from positions 11–100 and URLs outside the organic top 100.
Combining the two groups shows that the majority of citation URLs in this particular dataset were not conventional organic top-ten results for the same query.
CGO Media Calculation: 26.2% + 36.7% = 62.9%.
70. An AI system was approximately three times more likely to cite a ranking domain than the exact ranking page in one ChatGPT study
31.8% domain overlap versus 10% exact-URL overlap.
In an Ahrefs analysis of 3,311 short-tail terms, ChatGPT citations showed approximately 10% exact-URL overlap with Google’s top ten but 31.8% domain overlap.
The result suggests that domain-level relevance or authority may persist even when the AI system selects a different page from the site than the page ranking conventionally for the original query.
Freshness Can Influence the AI Source Environment
The evidence in this section should not be reduced to the claim that newer content automatically outranks or replaces older content in AI systems.
Authoritative evergreen research, legislation, historical evidence, technical standards and primary documentation may remain highly valuable regardless of publication date.
What the data does indicate is that AI-cited content can display a meaningful freshness advantage over conventional organic results. For subjects where facts, products, prices, technologies, regulations or market conditions change quickly, maintaining current information may therefore strengthen source eligibility.
Freshness should consequently be understood alongside relevance, evidence, authority, entity clarity and corroboration rather than as a standalone optimisation tactic.
AI citation eligibility appears to depend on more than conventional ranking position. Relevant, authoritative and current information can enter the source pool even when the exact page is not a top-ten organic result.
Content Maintenance Becomes a Visibility Discipline
For organisations with large content libraries, the research creates a practical question: how much existing material remains sufficiently current to support present-day AI answers?
Updating a page should not mean changing a date while leaving the underlying information untouched. Meaningful maintenance involves reviewing evidence, statistics, products, regulations, terminology, examples, references and conclusions to determine whether they still accurately represent the subject.
This is particularly relevant for research-led organisations because original studies, observations and statistics can become useful source material for AI systems when their methodology, publication date, evidence and scope are clearly communicated.
The GEO Implication
- Review high-value research and commercial pages regularly.
- Make publication and meaningful update dates clear.
- Replace outdated statistics with newer evidence where appropriate.
- Preserve primary historical evidence when its age is relevant rather than artificially rewriting it.
- Keep product, service and organisational information accurate.
- Maintain clear references to primary and authoritative sources.
- Strengthen the entire domain around important topics rather than relying on one ranking URL.
- Monitor citation visibility separately from conventional organic rankings.
Research Limitation
A correlation between citation selection and fresher content does not prove that publication age itself caused the citation. Newer pages may also differ from older pages in relevance, structure, topical coverage, evidence or other characteristics.
The findings should therefore be interpreted as evidence of a freshness pattern within the measured citation environment rather than proof of a universal AI freshness ranking factor.
Evidence Sources for Statistics 61–70
The evidence combines Ahrefs’ large-scale analysis of content freshness across approximately 17 million AI citations with its research into AI Overview citation rankings and ChatGPT citation overlap with conventional Google results.
View Ahrefs — AI Citation Content Freshness Research
Statistics 71–80
AI Referral Traffic, ChatGPT Growth & Where AI Sends Users
AI platforms increasingly function as discovery environments, but their impact extends beyond the answers displayed inside the interface. When users follow links from ChatGPT and other generative systems, AI becomes a measurable referral channel for external websites.
The available evidence shows rapid growth in ChatGPT referral traffic while also demonstrating that AI referrals remain highly concentrated and substantially smaller than Google as an overall source of website visits.
71. ChatGPT outbound referral traffic increased by approximately 206% during 2025
+206% — measured growth in outbound ChatGPT referral traffic.
Semrush and Kevin Indig analysed more than one billion lines of US clickstream data. Their research found that outbound referral traffic from ChatGPT more than tripled during 2025.
72. A 206% increase means ChatGPT referral traffic grew to approximately 3.06 times its starting level
Approximately 3.06× — ending referral level relative to the starting level.
A 206% increase represents the original traffic plus an additional 206% of that starting level.
CGO Media Calculation: 100% + 206% = 306%, or approximately 3.06× the starting level.
73. More than 30% of measured ChatGPT referral traffic went to just ten domains
More than 30% — referral share captured by the ten leading destination domains.
The concentration indicates that growth in AI referral traffic is not distributed evenly across the web. A relatively small group of destinations can capture a substantial share of outbound visits.
74. More than 20% of measured ChatGPT referral traffic went to Google
More than 20% — share of measured outbound ChatGPT referral traffic directed to Google.
This behaviour challenges the assumption that AI assistants and conventional search engines operate only as substitutes. Some users move from an AI environment into Google as part of the same broader discovery journey.
75. Google alone received at least two-thirds of the referral traffic captured by the top ten destinations
At least 66.7% — Google’s minimum share relative to the 30%+ captured by the top ten domains.
Because Google received more than 20% of all measured referral traffic while the top ten domains collectively received more than 30%, Google alone represented at least approximately two-thirds of that concentrated top-ten share.
CGO Media Calculation using the reported lower bounds: 20 ÷ 30 ≈ 66.7%. The exact proportion may differ because both published figures are stated as “more than”.
76. ChatGPT used its web-search feature on approximately 34.5% of measured queries in February 2026
Approximately 34.5% — measured queries involving ChatGPT’s web-search feature.
The finding demonstrates that a substantial proportion of measured ChatGPT activity involved live or external web retrieval rather than relying exclusively on information contained within the model.
77. Approximately 65.5% of measured ChatGPT queries did not trigger the web-search feature
Approximately 65.5% — complementary share not using the measured web-search feature.
This distinction is important for organisations measuring AI visibility. Not every AI interaction creates the same opportunity for current web pages to be retrieved or cited.
CGO Media Calculation: 100% − 34.5% = 65.5%.
78. Computer and technology destinations accounted for 36% of UK ChatGPT outgoing referral activity in Ofcom’s analysis
36% — computer and technology share of outgoing ChatGPT referral categories.
Ofcom’s analysis of Similarweb data shows that technology-related destinations represented the largest category of outgoing ChatGPT traffic in the UK evidence examined.
79. News and media accounted for 9.0% of ChatGPT outgoing traffic compared with 3.9% from Google
9.0% versus 3.9% — outgoing referral-category shares for news and media.
Within the Ofcom/Similarweb comparison, news and media represented a larger proportion of outgoing ChatGPT traffic than of outgoing Google traffic.
These figures describe the category composition of outgoing traffic. They do not mean that ChatGPT sends more total visits to news websites than Google.
80. Science and education represented 6.9% of ChatGPT outgoing traffic compared with 2.1% from Google
6.9% versus 2.1% — outgoing referral-category shares for science and education.
The category represented more than three times the proportion of outgoing traffic from ChatGPT than it did from Google within the measured comparison.
CGO Media Calculation: 6.9 ÷ 2.1 ≈ 3.29×. This compares category shares, not absolute referral volumes.
AI Referral Traffic Is Growing — But Distribution Matters
A 206% increase in ChatGPT outbound referral traffic demonstrates that generative AI is developing into a measurable acquisition channel.
However, rapid percentage growth should be interpreted alongside the channel’s starting scale and the concentration of traffic among leading destinations. Earlier evidence in this report showed that Google remained approximately 190 times larger than ChatGPT as a source of website traffic in the Ahrefs dataset.
AI referral traffic is therefore important because of its growth and its role in emerging discovery journeys — not because it has already replaced conventional search traffic.
The concentration of referrals also suggests that source selection and destination authority can have a disproportionate effect on which websites benefit from AI-mediated discovery.
AI referral traffic should be measured as an emerging acquisition channel, but AI influence extends beyond referrals because many generative interactions can affect discovery without producing an immediate external click.
The Search Journey Is Becoming Cross-Platform
The finding that more than one-fifth of measured ChatGPT outbound referral traffic went to Google is particularly revealing.
It indicates that some users do not choose between AI and conventional search once and remain within that environment. Instead, they can move between platforms as the information need develops.
A user might ask ChatGPT for an initial explanation, move to Google to investigate a company or product, return to an AI assistant for comparison and finally reach a website through branded search or direct navigation.
This makes attribution more difficult. The platform responsible for the final website session may not be the platform that originally created awareness or shaped the user’s shortlist.
AI and Google Can Send Different Types of Referral Traffic
The Ofcom/Similarweb category evidence suggests that outgoing traffic from ChatGPT is distributed differently from outgoing traffic from Google.
| Destination Category | ChatGPT | |
|---|---|---|
| News & Media | 9.0% | 3.9% |
| Science & Education | 6.9% | 2.1% |
| Ecommerce & Shopping | 4.5% | 2.2% |
| Health | 4.2% | 3.0% |
These percentages compare the composition of outgoing traffic, not absolute visitor numbers. Google may still send substantially more total traffic to a category even where that category represents a smaller percentage of Google’s much larger referral base.
The Measurement Implication
Organisations evaluating AI search should avoid measuring only direct referral sessions. A broader measurement framework can include:
- AI referral traffic by platform.
- AI-assisted conversions.
- Brand mentions within generated answers.
- Citation visibility.
- Recommendation and comparison visibility.
- Growth in branded search demand.
- Direct traffic following AI exposure.
- Conversion quality of AI-referred visitors.
- Cross-platform discovery journeys.
Research Limitation
The Semrush referral analysis uses US clickstream data and should not be presented as a direct measurement of UK referral behaviour. The Ofcom/Similarweb evidence provides UK context but measures outgoing traffic categories rather than total search demand.
Referral traffic also captures only interactions that result in an external visit. It cannot measure every occasion on which an AI answer influences awareness, trust, consideration or a later purchase.
Evidence Sources for Statistics 71–80
This section combines Semrush and Kevin Indig’s large-scale analysis of ChatGPT referral and search behaviour with Ofcom’s UK reporting based on Similarweb data.
Statistics 81–90
Commercial Search, Ecommerce, Research Behaviour & AI Recommendation Visibility
The commercial importance of AI search depends on more than the number of people using ChatGPT, Gemini or other assistants. Search has traditionally influenced purchasing because consumers use it to research products, services, organisations and alternatives before making decisions.
UK evidence shows that online search remains deeply embedded in product research, while referral data indicates that AI assistants are beginning to participate in ecommerce, health, education, news and other discovery journeys. The result is an increasingly fragmented path between initial research and final conversion.
81. 95% of UK adult internet users searched online for information during the previous three months
95% — online information-search activity among UK adult internet users.
Ofcom’s Online Nation evidence demonstrates how firmly information search remains embedded in UK internet behaviour. AI search is therefore developing within an already highly search-active population.
82. 71% used online search when researching products or purchases
71% — online searching connected with purchase research.
Commercial research is one of the most important reasons search visibility matters. Organisations that become absent during research and comparison can lose influence before the customer reaches a transactional page.
83. 70% searched online for UK news
70% — online search activity associated with UK news.
News discovery illustrates why source authority and citation selection matter beyond conventional ecommerce. Search platforms and AI systems can influence which publishers and organisations become visible during information-seeking journeys.
84. 58% searched online for hobbies and interests
58% — online information searching connected with hobbies and interests.
This type of exploratory behaviour is particularly relevant to generative systems because conversational interfaces can support discovery, explanation, comparison and recommendation within a single interaction.
85. 53% of UK adults reported often seeing AI-generated summaries in search
53% — reported frequent exposure to AI summaries.
AI-mediated discovery is therefore not limited to people deliberately opening a standalone chatbot. Generative answers are also being integrated into mainstream search experiences.
86. Ecommerce and shopping accounted for 4.5% of ChatGPT outgoing traffic in Ofcom’s comparison
4.5% — ecommerce and shopping share of measured outgoing ChatGPT traffic.
The figure demonstrates that AI-assisted activity can lead users directly into retail and shopping environments, although it measures outgoing traffic composition rather than the proportion of prompts concerned with shopping.
87. Ecommerce and shopping represented 2.2% of Google’s outgoing traffic in the same comparison
2.2% — ecommerce and shopping share of measured outgoing Google traffic.
Because Google operates at a much larger overall traffic scale, this percentage should not be interpreted as meaning ChatGPT sends more total shopping traffic than Google.
88. Ecommerce represented approximately twice the share of outgoing traffic from ChatGPT as from Google
Approximately 2.05× — 4.5% compared with 2.2%.
Within the measured category distribution, ecommerce and shopping represented roughly twice the proportion of outgoing ChatGPT traffic.
CGO Media Calculation: 4.5 ÷ 2.2 ≈ 2.05×. This compares category shares rather than absolute traffic volumes.
89. Health accounted for 4.2% of ChatGPT outgoing traffic compared with 3.0% from Google
4.2% versus 3.0% — health share of measured outgoing traffic.
The result indicates that AI-mediated discovery is relevant to high-trust sectors as well as retail. In health-related journeys, source authority, accuracy and evidence quality are especially important because the consequences of unreliable information can be substantially greater.
90. Comparative content generated 2.4 times more brand mentions in measured AI answers
2.4× — brand mentions associated with comparative content relative to informational content.
This Semrush finding is particularly relevant to commercial AI search because comparison prompts are often closer to brand selection than purely informational questions.
For organisations, the competitive objective can therefore extend beyond being cited as an informational source towards becoming one of the entities an AI system considers relevant enough to compare, discuss or recommend.
AI Search Is Moving Into Commercial Discovery
Commercial search has traditionally been described through keywords such as “best”, “reviews”, “compare”, “near me”, product names and service categories. Generative interfaces can combine many of these research steps into a conversational journey.
A user can describe a problem, add requirements, reject unsuitable options, request comparisons and ask for recommendations without repeatedly returning to a conventional search-results page.
This creates a potentially important change in commercial visibility. The competitive question is no longer limited to which company ranks for a purchase-intent keyword. It can also include which organisations enter the AI system’s candidate set and remain present as the user’s requirements become more specific.
For retailers, service businesses and other commercial organisations, recommendation visibility may therefore become an increasingly important complement to conventional ranking visibility.
The commercial AI search opportunity is not simply to attract a click. It is to remain visible while an AI system helps the user research, compare and narrow the available choices.
From Search Ranking to Recommendation Eligibility
Traditional SEO remains important because users continue to conduct enormous volumes of conventional searches and AI systems themselves can retrieve information from the web.
However, commercial AI visibility introduces an additional requirement: the system must understand enough about an organisation, product or service to determine when it is relevant to a particular user scenario.
That can require clear entity information, product and service attributes, pricing or commercial information where appropriate, geographical relevance, independent validation, evidence of expertise, customer-use context and consistent information across external sources.
The objective becomes not merely ranking for a phrase, but building enough machine-readable and externally corroborated evidence for the organisation to remain eligible when AI systems construct a shortlist.
AI Commercial Discovery Journey
A simplified commercial AI discovery journey can increasingly look like:
User Need
→
AI Research
→
Candidate Brands
→
Evidence Retrieval
→
Comparison
→
Recommendation
→
Validation
→
Conversion
What Businesses Need to Measure
As commercial discovery becomes more fragmented, organisations may need to measure performance across both conventional and generative search environments.
- Organic search rankings and traffic.
- Commercial keyword visibility.
- AI brand mentions.
- AI citation visibility.
- Product and service recommendation visibility.
- Comparison-query visibility.
- Share of AI answers mentioning the organisation.
- AI referral traffic.
- Branded search demand.
- Direct traffic following research activity.
- Qualified leads and conversions influenced by AI discovery.
Important Interpretation
The outgoing traffic percentages in this section are not measures of the percentage of ChatGPT prompts concerned with ecommerce, health or other sectors. They describe the category distribution of external destinations reached from the measured platforms. They should not be converted into prompt-market-share estimates.
Evidence Sources for Statistics 81–90
The evidence in this section combines Ofcom’s UK search-behaviour reporting, Ofcom’s analysis of outgoing ChatGPT and Google traffic using Similarweb data, and Semrush research examining citation and brand-mention behaviour across generative search platforms.
View Ofcom — Online Nation 2025
Statistics 91–100
AI Search Market Outlook 2026, Key Findings & Final Conclusions
The evidence across the first 90 statistics shows a search market undergoing structural change rather than a simple replacement of Google by standalone AI assistants.
Google remains enormous, ChatGPT has established substantial direct usage, Gemini is expanding, generative answers are becoming part of mainstream search, and AI systems increasingly influence which sources, brands and organisations users encounter during research. The final ten statistics bring these developments together and establish the scale of the emerging hybrid search market.
91. Google AI Overviews have more than 2.5 billion monthly active users globally
More than 2.5 billion monthly active users — Google AI Overviews.
Google’s first-party 2026 reporting places AI Overviews at global internet scale. This is important because generative search adoption is not limited to users deliberately choosing a standalone AI assistant.
92. Google AI Mode has more than 1 billion monthly active users globally
More than 1 billion monthly active users — Google AI Mode.
AI Mode represents a more explicitly generative search experience within Google’s ecosystem. Its reported audience demonstrates that conversational and generative search behaviour can develop inside the world’s dominant conventional search platform.
93. AI Overviews have at least 2.5 times the reported monthly active audience of AI Mode
At least 2.5× — comparison of the two reported global user figures.
The comparison illustrates the reach advantage that can result when generative functionality is integrated directly into an established search experience.
CGO Media Calculation: 2.5 billion ÷ 1 billion = 2.5×. Both source figures are reported as “more than”, so the precise ratio is not established.
94. Google says AI Mode query volume has more than doubled every quarter since launch
More than 2× per quarter — reported AI Mode query-volume growth since launch.
This is a first-party Google growth statement rather than an independently audited market-share measurement. It nevertheless indicates rapid expansion in the use of Google’s dedicated generative search interface.
95. Google Search still accounted for approximately 40% of measured website traffic in Ahrefs’ study
Nearly 40% — Google’s share of measured website traffic across approximately 76,000 sites.
The figure provides essential context for AI market-growth statistics. Conventional Google traffic remained vastly larger than direct ChatGPT referral traffic within the same Ahrefs dataset.
96. ChatGPT accounted for approximately 0.21% of measured website traffic in the same dataset
Approximately 0.21% — ChatGPT’s measured contribution to website traffic.
Direct referral traffic is only one measure of AI influence. ChatGPT can affect awareness, research, comparisons and later branded searches without being recorded as the final referring source.
97. Google generated approximately 190 times more measured website traffic than ChatGPT
Approximately 190× — Google versus ChatGPT as a measured website traffic source.
This is one of the clearest warnings against interpreting rapid AI growth as evidence that conventional search has already been displaced.
98. Approximately 65% of ChatGPT activity was classified as search or search-like under Ahrefs’ methodology
Approximately 65% — ChatGPT activity classified as search or search-like.
The result reinforces ChatGPT’s relevance to search-market analysis while also recognising that not every interaction with a generative assistant represents a conventional information-search task.
99. ChatGPT search-like activity was estimated at approximately 11.86% of Google search volume under the Ahrefs methodology
Approximately 11.86% — estimated ChatGPT search-like activity relative to Google search volume.
This estimate measures search-like activity rather than referral traffic and therefore answers a different question from the 0.21% website-traffic figure.
100. AI search can already influence a much larger share of discovery than AI referral traffic alone suggests
The evidence does not support reducing AI search to a single market-share percentage.
Across the evidence reviewed in this report, AI search appears through standalone chatbot usage, Google AI Overviews, AI Mode, citations, brand mentions, recommendations, query fan-out, web retrieval and external referral traffic.
The most defensible conclusion is therefore not that AI holds one fixed percentage of “search”. It is that generative systems have become a material layer of the wider search and discovery ecosystem while conventional search continues to operate at enormous scale.
CGO Media Research
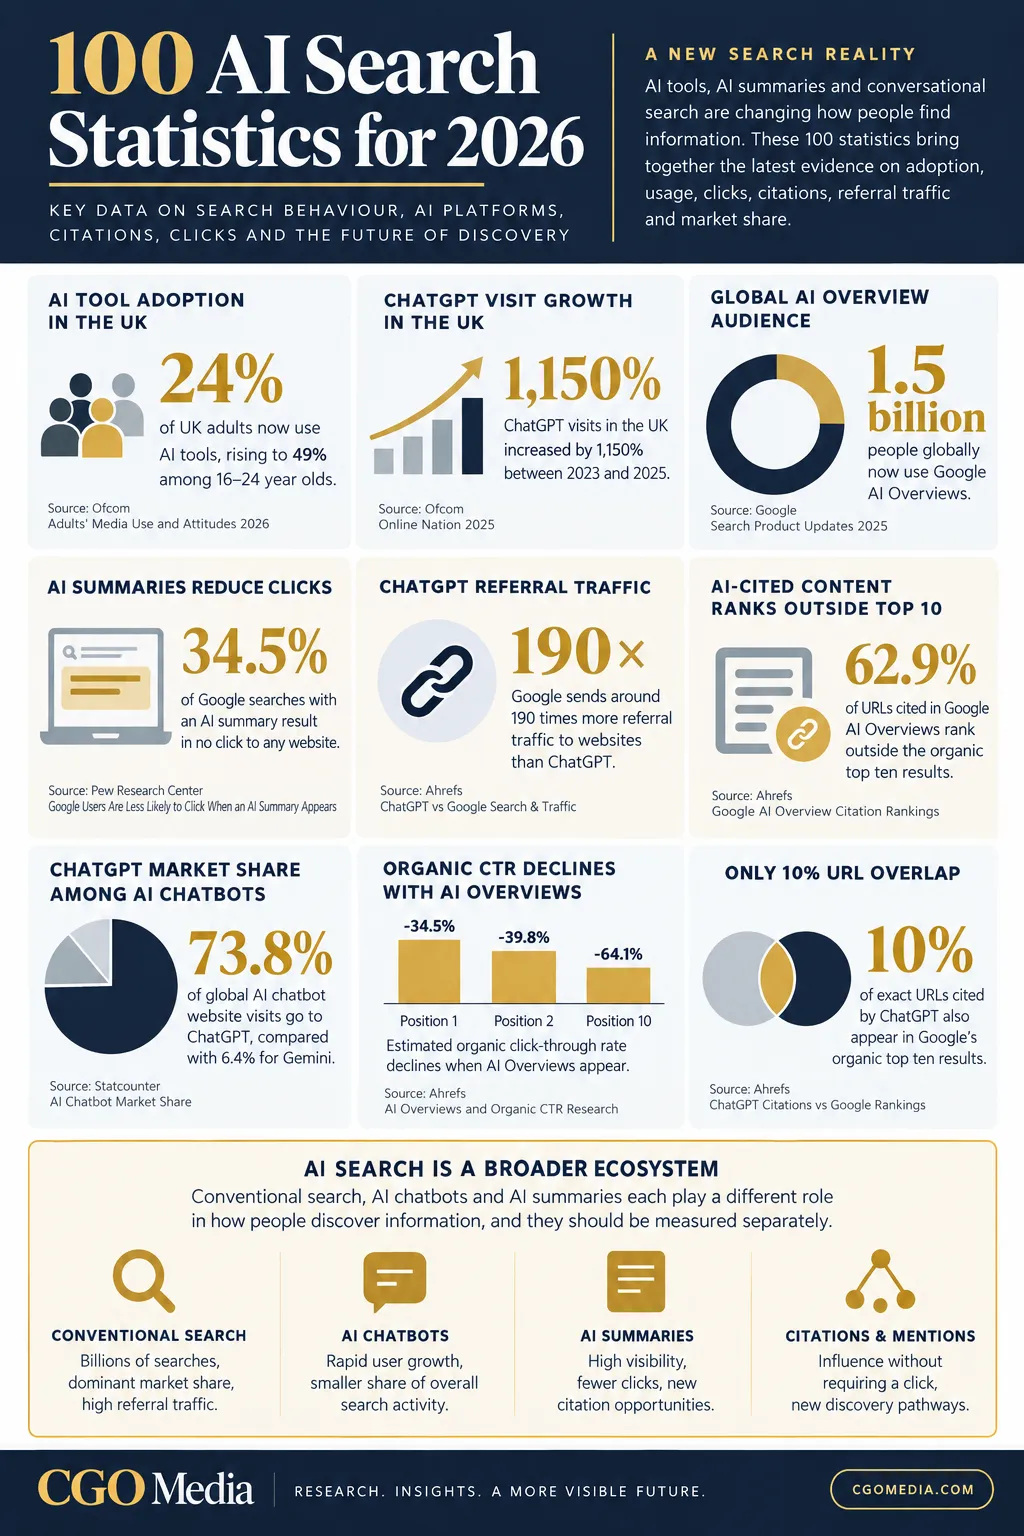
100 AI Search Market Share Statistics
Together, these statistics show a search ecosystem in which conventional rankings, generative answers, citations, brand mentions, recommendations and referral traffic increasingly operate alongside one another.
Key Findings from the 100 Statistics
AI Adoption
AI tools have reached mainstream audiences, particularly among younger adults, and standalone assistants now operate at substantial scale.
Google Remains Huge
Rapid AI growth has not eliminated conventional search. Google remains one of the largest sources of information discovery and website traffic.
Google Is Becoming AI Search
AI Overviews and AI Mode mean that the boundary between traditional search engines and generative AI is increasingly difficult to define.
Clicks Are Changing
AI-generated answers can reduce traditional result clicking for some informational searches and allow users to complete more of the journey before visiting a website.
Citations ≠ Mentions
Being selected as an information source is not the same as having the organisation explicitly named or recommended in the generated answer.
Rankings ≠ Citations
AI source selection overlaps with conventional organic rankings but can retrieve and cite pages well beyond the traditional top-ten result set.
Retrieval Is Dynamic
Reasoning depth and query fan-out can materially alter the searches performed and the domains selected as evidence.
Commercial Discovery Is Expanding
AI assistants can participate in research, comparison and recommendation journeys before the customer reaches a transactional website.
AI Search Market Outlook for 2026
The available evidence does not support declaring a single percentage for AI’s share of the entire search market. The platforms, studies and methodologies measure different behaviours.
What can be established is that generative AI has become a significant part of information discovery. Standalone AI platforms have attracted large audiences, Google has integrated generative answers directly into Search, and AI systems increasingly retrieve and cite information from across the web.
This creates a hybrid search environment rather than two completely separate markets. Users can move between Google, ChatGPT, Gemini, AI Overviews, websites, social platforms, publishers and direct brand destinations during the same research journey.
The organisations best positioned for this environment will therefore need visibility across multiple discovery surfaces rather than depending on one ranking system or one traffic source.
The Emerging Search Visibility Model
Traditional Search Visibility
+
AI Citation Visibility
+
Brand Visibility
+
Recommendation Visibility
+
Entity Authority
=
Search Ecosystem Visibility
What This Means for SEO and GEO
SEO remains important because conventional search remains enormous and many of the technical, content and authority signals developed through strong SEO also support machine discovery.
Generative Engine Optimisation adds another layer. Organisations increasingly need to consider whether AI systems can identify them, retrieve their information, understand their expertise, corroborate their claims and consider them relevant during comparison or recommendation.
The objective is therefore not to replace SEO with GEO. It is to build search authority capable of operating across conventional search results and generative discovery systems.
That requires strong technical foundations, useful content, entity clarity, original evidence, external authority, accurate information, citation eligibility and sufficient brand signals for an organisation to be recognised as a credible candidate within AI-mediated discovery.
CGO Media Research Conclusion
AI search is not replacing the search market with one new platform. It is changing the architecture of search itself.
Search visibility increasingly occurs across rankings, generated answers, citations, entity recognition, comparisons, recommendations and referral journeys. Different platforms expose these signals differently, and no single market-share statistic captures the complete environment.
For businesses and organisations, the strategic challenge is consequently broader than achieving a position in Google’s organic results. The organisation must become sufficiently visible, authoritative and understandable to remain discoverable wherever users and AI systems conduct research.
The 2026 search market is best understood as an interconnected discovery ecosystem in which SEO, AI search visibility, citations, brand authority and Generative Engine Optimisation increasingly converge.
How CGO Media Interprets AI Search Market Statistics
AI search research currently uses multiple methodologies. Studies can measure platform visits, monthly audiences, prompts, search-like activity, web retrieval, citations, brand mentions, referral traffic, click behaviour or conventional search-engine share.
CGO Media does not treat these measurements as interchangeable. Statistics are interpreted according to the population, geography, time period and methodology used by the original source.
Where CGO Media calculates a percentage, ratio or comparison from published source figures, it is identified as a CGO Media calculation rather than presented as a statistic published directly by the underlying source.
This approach allows evidence from adoption, behaviour, clicks, citations, retrieval and traffic studies to be considered together without pretending that each study measures the same phenomenon.
Research Review & Update Policy
AI search is changing rapidly. Platform audiences, interfaces, citation behaviour, retrieval systems and search integrations can change materially within months.
CGO Media reviews its research pages as new primary evidence, platform disclosures and substantial independent studies become available. Earlier figures may be retained where they provide useful historical context, but their dates and scope should remain visible.
For further information about how CGO Media evaluates evidence, visit the
Research Methodology
page.
Evidence Sources for Statistics 91–100
The final statistics use Google’s first-party reporting on AI Overviews and AI Mode together with Ahrefs research comparing Google, ChatGPT, website referral traffic and search-like activity. Global figures are identified as global and should not be interpreted as UK-specific measurements.
View Ahrefs — ChatGPT vs Google Search & Traffic
CGO Media Research Team
Researching the Changing Search Ecosystem
CGO Media researches how traditional search, AI search, citations, entities, brand authority and generative recommendation systems are changing digital discovery for businesses and organisations.
For research, journalist and media enquiries, visit
Press & Media
.
CGO Media Research
References & Evidence Sources
The 100 statistics in this report draw on primary platform disclosures, regulatory research, large-scale clickstream datasets, behavioural studies and independent analyses of AI search, citations, rankings and referral traffic.
CGO Media distinguishes between statistics reported directly by the original source and calculations produced from published figures. Where a percentage, ratio or comparison has been calculated by CGO Media, it is identified within the relevant statistic.
Source Standard
Different studies measure different parts of the search ecosystem. Platform usage, search-engine market share, AI chatbot visits, search-like activity, citations, brand mentions, referral traffic and click behaviour should not be treated as interchangeable measurements.
1. Ofcom — Adults’ Media Use and Attitudes 2026
UK regulatory research covering media behaviour and adoption of AI tools among adults.
Used for: UK AI-tool adoption, including overall adult usage and adoption among younger age groups.
Ofcom — Adults’ Media Use and Attitudes
2. Ofcom — The Era of Answer Engines
Ofcom analysis examining generative AI’s impact on search experiences and online behaviour, incorporating evidence from Ipsos iris and Similarweb.
Used for: UK chatbot reach, ChatGPT reach and outgoing traffic-category comparisons between ChatGPT and Google.
Ofcom — The Era of Answer Engines
3. Ofcom — Online Nation 2025
Ofcom’s annual analysis of UK online behaviour, platforms and internet use.
Used for: UK ChatGPT visit growth, Google Search usage, AI-summary exposure and information-search behaviour including product research, news, hobbies and interests.
4. Pew Research Center — Google AI Summaries and Search Behaviour
Pew Research Center behavioural analysis published in July 2025, based on 900 US adults and 68,879 Google searches.
Used for: AI-summary prevalence, traditional-result click rates, citation clicks, search-session endings and source behaviour within Google AI summaries.
Pew Research Center — Google Users Are Less Likely to Click When an AI Summary Appears
5. Statcounter GlobalStats — Search Engine Market Share
Statcounter browser and device measurement data tracking conventional search-engine market share.
Used for: Google and Bing conventional search-engine market-share comparisons.
Statcounter — Search Engine Market Share
6. Statcounter GlobalStats — AI Chatbot Market Share
Statcounter’s measurement of AI chatbot market-share activity.
Used for: ChatGPT and Gemini AI chatbot share comparisons.
Statcounter — AI Chatbot Market Share
7. Similarweb — Generative AI Platform Traffic
Similarweb digital traffic intelligence covering visits to major generative AI platforms.
Used for: generative AI website-visit distribution, including ChatGPT, Gemini and Claude traffic comparisons.
Similarweb — Generative AI Statistics
8. Ahrefs — AI Overviews and Organic Click-Through Rates
Ahrefs analysis of approximately 300,000 informational keywords examining the relationship between AI Overviews and organic click-through rates.
Used for: estimated CTR effects for positions one, two and ten when AI Overviews appear.
Ahrefs — AI Overviews and Organic CTR Research
9. Ahrefs — ChatGPT vs Google Search & Website Traffic
Ahrefs analysis covering approximately 76,000 websites and comparing Google traffic with ChatGPT traffic and estimated search-like activity.
Used for: Google’s share of measured website traffic, ChatGPT referral traffic, the approximately 190× traffic difference, search-like ChatGPT activity and comparison with Google search volume.
Ahrefs — ChatGPT vs Google Search & Traffic
10. Ahrefs — AI Citation and Search Ranking Overlap
Ahrefs research comparing AI citations with conventional Google and Bing search rankings across approximately 15,000 prompts.
Used for: approximate overlap between AI-cited URLs and Google or Bing top-ten organic results.
11. Ahrefs — ChatGPT Citations vs Google Rankings
Ahrefs analysis of 3,311 short-tail terms comparing exact-URL and domain-level overlap between ChatGPT citations and Google’s organic top ten.
Used for: approximately 10% exact-URL overlap, 31.8% domain overlap and the distinction between page-level and domain-level citation visibility.
12. Ahrefs — Google AI Overview Citation Rankings
Large-scale Ahrefs research examining approximately 863,000 keyword SERPs and four million URLs cited by Google AI Overviews.
Used for: the 37.1% of citation URLs ranking in the organic top ten, 26.2% ranking between positions 11 and 100, and 36.7% outside the organic top 100.
13. Ahrefs — AI Citation Content Freshness
Ahrefs analysis of approximately 17 million citations across seven AI platforms examining the relationship between citation selection and content freshness.
Used for: the estimated 25.7% freshness difference between AI-cited and Google organic content and ChatGPT freshness comparisons of approximately 393 and 458 days.
14. Semrush / Kevin Indig — AI Citations & Brand Mentions
Research covering 3,981 domain appearances across 115 prompts and 14 countries, examining ChatGPT, Google AI Overviews, AI Mode and Gemini.
Used for: ghost citations, citation rates, brand-mention rates, ChatGPT and Gemini differences and the relationship between comparative content and brand mentions.
Semrush — Ghost Citations Study
15. Semrush / Kevin Indig — ChatGPT Reasoning & Source Selection
Research comparing minimal- and high-reasoning configurations across 100 prompts and 20 buyer journeys.
Used for: citation-rate changes, citations per response, 4.6× query fan-out, 245 versus 1,130 web searches, 25.6% domain overlap, unique-domain counts and high-reasoning-only sources.
16. Semrush / Kevin Indig — ChatGPT Search & Referral Behaviour
Analysis of more than one billion lines of US clickstream data examining ChatGPT referral growth, destination concentration and use of web search.
Used for: 206% outbound referral growth during 2025, concentration among leading domains, referrals to Google and the approximately 34.5% web-search-feature rate measured in February 2026.
17. Google — Search & AI Product Updates
First-party Google reporting on the expansion of generative AI within Google Search.
Used for: global AI Overview and AI Mode audience figures, reported AI Mode query growth and contextual information about Google’s AI search ecosystem.
Google — Search Product Updates
Research Methodology
CGO Media reviews evidence according to what each dataset actually measures. Studies based on UK adults are used to describe UK behaviour; US behavioural studies are identified as US evidence; global platform disclosures are described as global figures.
The report does not convert website traffic share into search-query share, chatbot traffic into conventional search-engine market share, referral-category percentages into prompt percentages, or citation rates into market-share estimates.
Where multiple studies address related behaviour, they are used to build a broader picture of the search ecosystem without assuming that the underlying measurements are directly equivalent.
Where calculations are derived from published figures — including percentage changes, ratios or combined shares — they are labelled as CGO Media calculations.
A fuller explanation of the research process is available on the
CGO Media Research Methodology
page.
Important Reading Note
AI search is developing faster than conventional market-measurement frameworks. There is currently no single universally accepted metric that represents “AI search market share”.
A platform can have a high share of generative AI website visits while still representing a much smaller proportion of total search activity. A platform can also influence discovery without generating a referral click.
For that reason, the statistics in this report should be interpreted collectively rather than using one measurement as a proxy for the entire search market.
Research Review & Update Policy
The AI search market changes rapidly. CGO Media reviews this report as new regulatory evidence, platform disclosures, behavioural studies and independent research become available.
Earlier statistics may remain in the report where they provide useful evidence of market development over time. Publication dates, study populations and methodologies should therefore be considered when comparing figures.
Material changes to major statistics, calculations or conclusions should be incorporated into future revisions of the page.
Research & Analysis
CGO Media Research Team
CGO Media researches how search behaviour, artificial intelligence, citations, entities, authority signals and generative recommendation systems are changing digital discovery.
For journalist, research or media enquiries, visit
CGO Media Press & Media
.