Financial Services GEO
 Financial Services GEO is the application of Generative Engine Optimisation to financial services, banking, insurance, lending, investment, payments, fintech and other regulated financial environments where AI-assisted systems increasingly influence how consumers and businesses discover, compare and evaluate financial providers.
Financial discovery is becoming more complex because users are no longer relying exclusively on conventional search results, comparison websites and direct provider research. They are increasingly asking AI assistants and generative search systems questions about products, providers, suitability, costs, eligibility, regulation, risk, features and alternatives.
This creates a new visibility challenge for financial organisations. It is no longer enough to rank prominently for commercial keywords. Providers increasingly need to be accurately understood as entities, represented correctly at product level, supported by reliable regulatory and trust evidence, cited by credible sources, included in appropriate comparison sets and recommended only where customer fit is genuine.
1. Financial GEO Extends Traditional Financial SEO
Traditional financial SEO remains essential because technical accessibility, content quality, search demand, site architecture and authority continue to influence digital discovery.
2. Financial GEO Adds a Generative Discovery Layer
Financial GEO adds explicit focus on:
- AI source selection
- Citation visibility
- Entity representation
- Product representation
- Provider comparison
- Recommendation visibility
3. Financial GEO Is Not Simply About Appearing in AI Answers
The more important objective is to appear appropriately.
4. Qualified Financial GEO Visibility Requires More Than Mentions
A useful relationship is:
Relevant Presence + Accurate Representation + Strong Trust Evidence + Appropriate Provider Recommendation
5. Financial Services Are High-Trust Environments
Financial decisions can affect:
- Income
- Debt
- Savings
- Insurance protection
- Investment outcomes
- Business continuity
6. Financial GEO Must Therefore Be Evidence-Led
Unsupported claims, ambiguous product descriptions and weak regulatory information can create substantial trust problems.
7. Financial GEO Begins with Entity Clarity
AI systems should be able to understand who the provider is.
8. Financial Entities Can Include
- Banks
- Insurers
- Lenders
- Investment firms
- Payment providers
- Fintech companies
9. Entity Clarity Includes Organisational Relationships
Financial groups can contain:
- Parent companies
- Subsidiaries
- Trading brands
- Regional entities
- Licensed operating entities
10. Financial Entity Ambiguity Can Create Material Risk
Users may receive incorrect information about:
- Who provides the product
- Which entity is regulated
- Which company owns the brand
- Which jurisdiction applies
11. Financial GEO Requires Clear Provider Identity
A basic relationship can be represented as:
Financial Group → Operating Entity → Brand → Product → Customer Segment → Jurisdiction
12. Product Clarity Is the Second Financial GEO Foundation
AI systems need to understand what financial products actually do.
13. Financial Products Can Include
- Current accounts
- Savings accounts
- Credit cards
- Loans
- Mortgages
- Insurance products
- Investment products
- Payment services
14. Product Representation Should Be Explicit
Important product information can include:
- Eligibility
- Fees
- Rates
- Terms
- Benefits
- Restrictions
15. Financial Product Ambiguity Can Distort Recommendation
An AI system may recommend an unsuitable provider if it misunderstands:
- Who can apply
- Where the product is available
- What fees apply
- What risks exist
16. Product Clarity Should therefore Support Customer Fit
A useful relationship is:
Customer Need → Product Type → Eligibility → Terms → Risk → Provider Fit
17. Regulatory Clarity Is a Core Financial GEO Requirement
Financial services operate within regulated environments where provider legitimacy is critical.
18. Regulatory Evidence Can Include
- Regulator registration
- Authorisation status
- Licence information
- Jurisdiction
- Regulatory disclosures
19. Regulatory Evidence Should Be Easy to Verify
Important claims should connect clearly to authoritative regulatory sources.
20. Financial GEO Should Distinguish Brand from Regulated Entity
This distinction is particularly important where commercial brands operate through separately regulated companies.
21. Trust Evidence Extends Beyond Regulation
Financial trust can also include:
- Financial stability
- Customer protection
- Independent reviews
- Professional recognition
- Operational history
- Security standards
22. Trust Evidence Should Match the Claim
A strong relationship is:
Financial Claim → Appropriate Evidence → Independent Validation → Customer Confidence
23. Trust Claims Should Avoid Vagueness
Statements such as “trusted”, “secure” or “leading” are weak without supporting evidence.
24. Specific Evidence Is Stronger Than Generic Assurance
For example:
- Named regulator
- Published licence status
- Defined customer protection
- Independent research
- Documented security standard
25. Financial GEO Also Depends on Source Authority
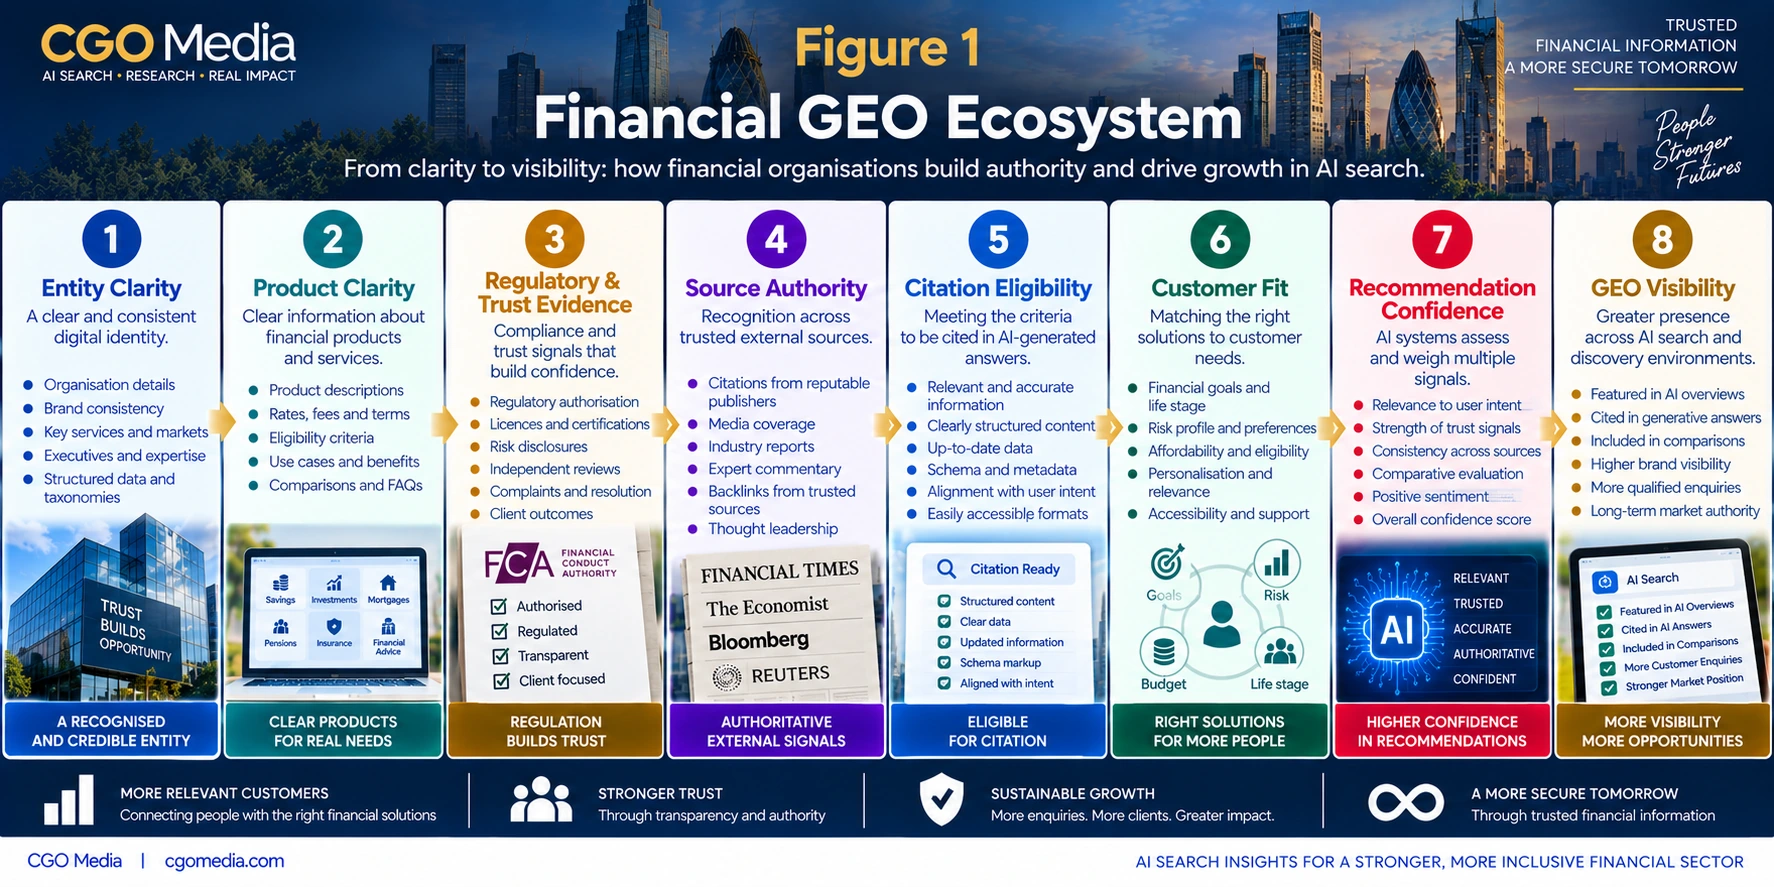
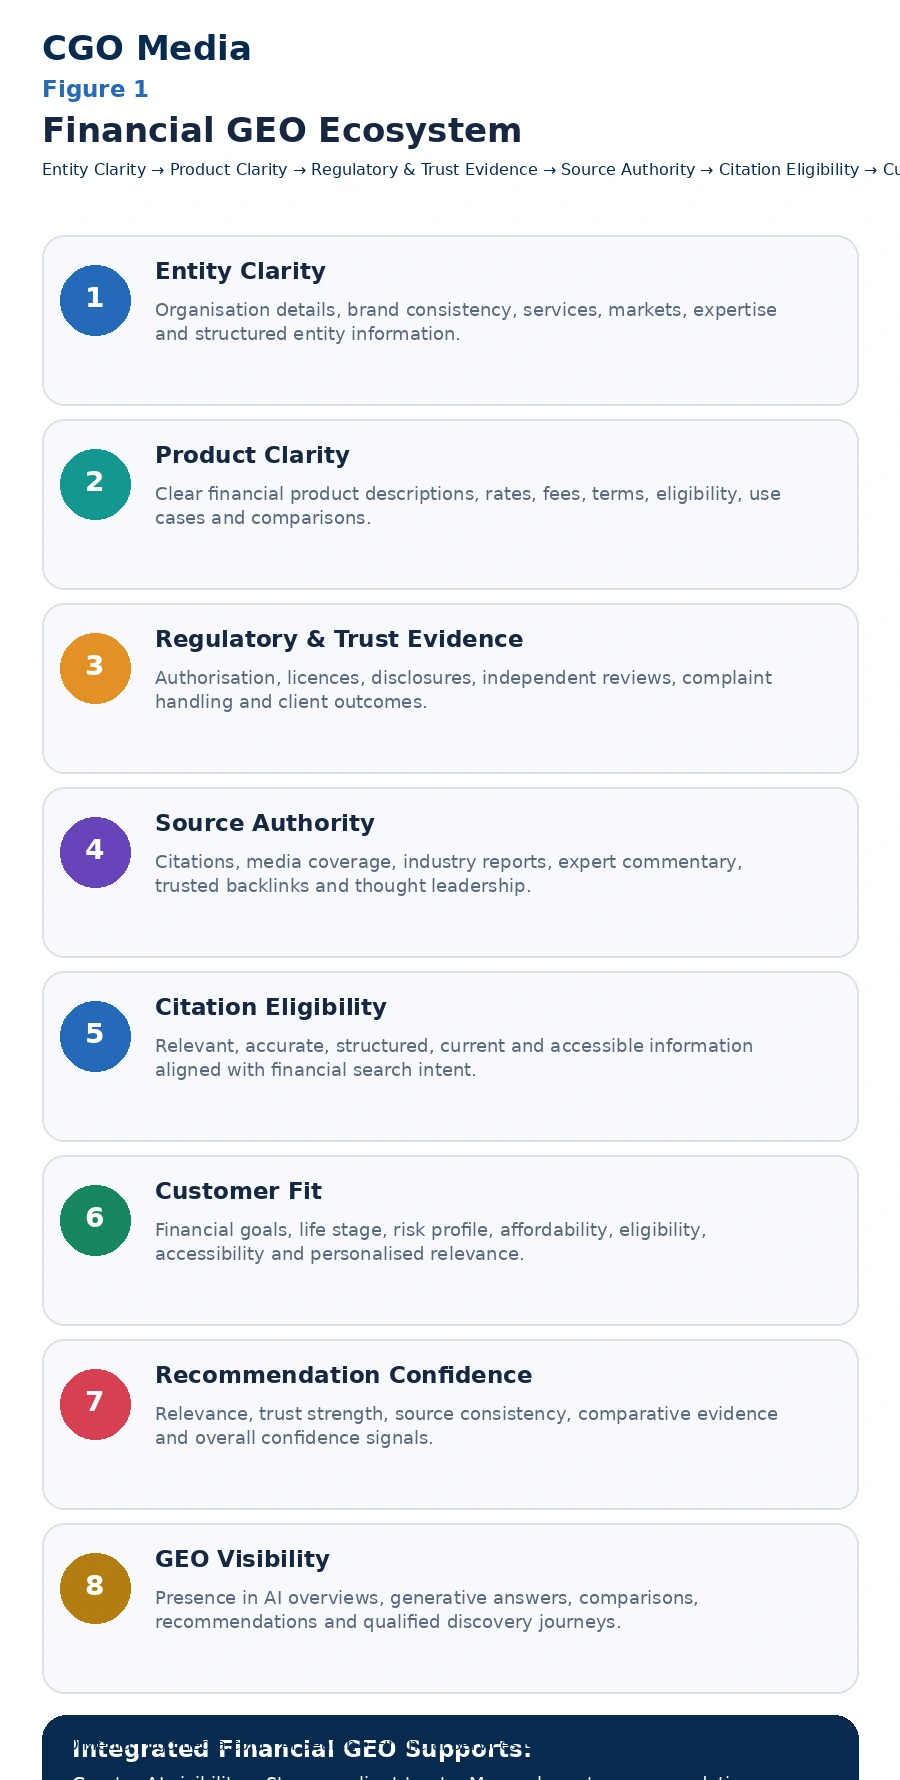
Generative systems can draw from many types of financial information sources.
26. Potential Financial Sources Can Include
- Provider websites
- Regulators
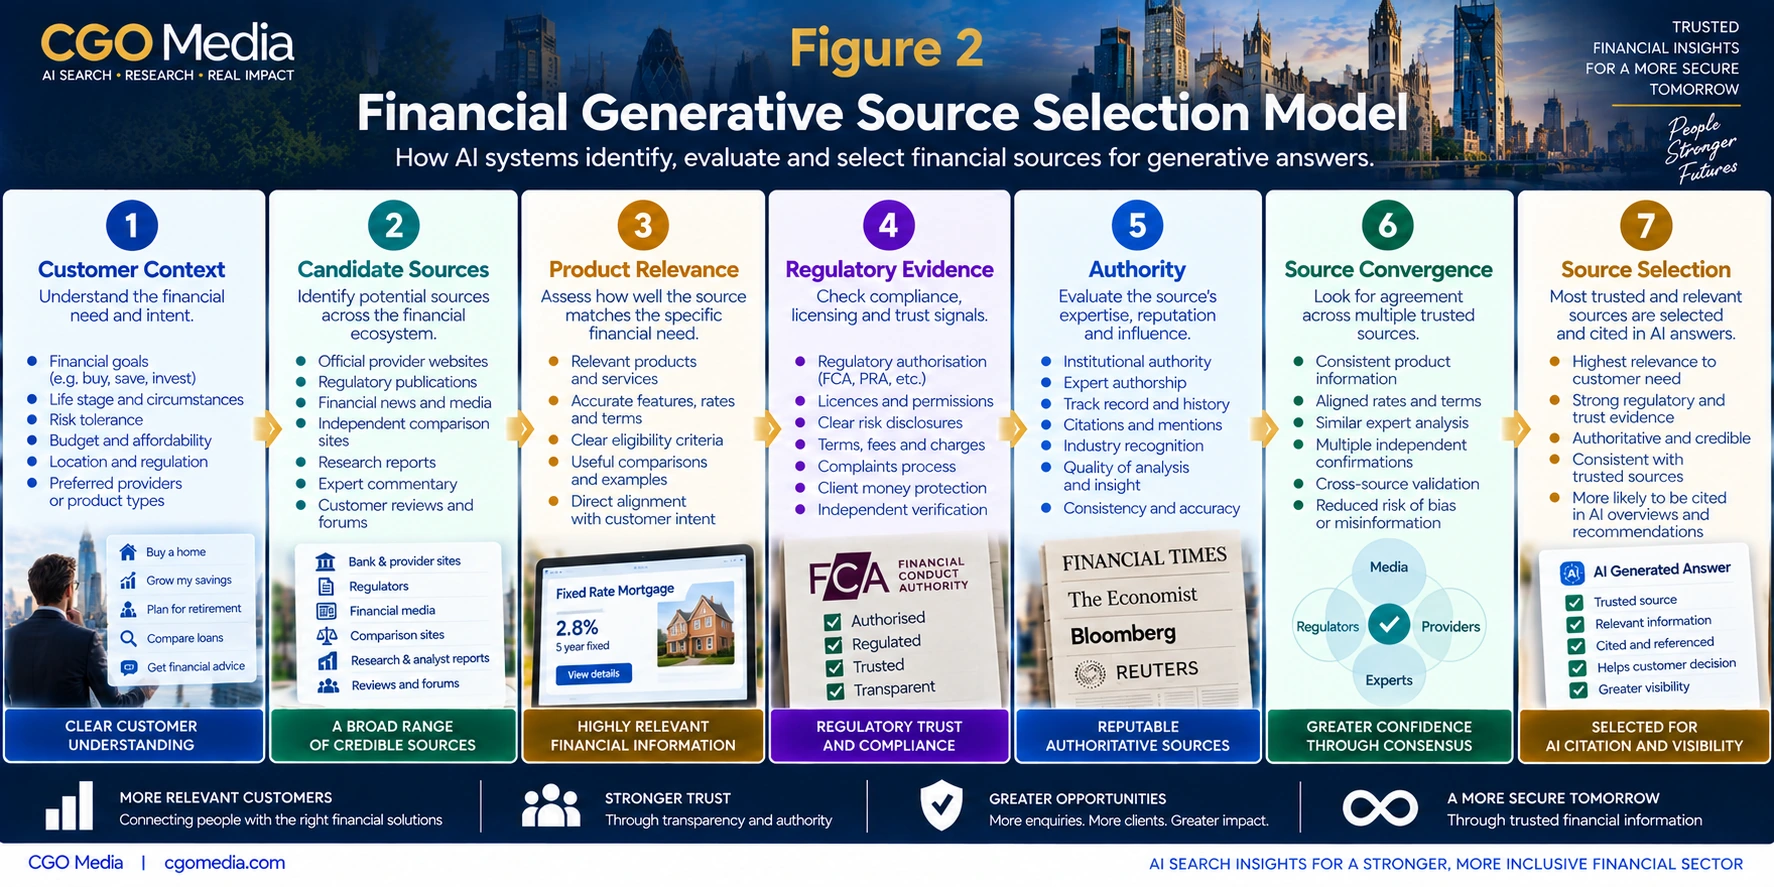
- Government sources
- Comparison platforms
- Financial media
- Professional organisations
27. Different Financial Questions Require Different Sources
A regulatory question may require different evidence from a product-comparison question.
28. Provider-Owned Sources Are Strongest for First-Party Facts
These can include:
- Fees
- Rates
- Product features
- Eligibility
- Application process
29. Independent Sources Can Strengthen Validation
External evidence can support:
- Regulatory legitimacy
- Market position
- Trust
- Product comparisons
- Industry authority
30. Financial GEO Requires Source Convergence
Important facts should materially agree across credible sources.
31. Source Convergence Can Be Represented as
Provider Information + Regulatory Evidence + Independent Financial Sources + Customer Evidence
32. Conflicting Financial Information Creates Risk
Conflicts can occur around:
- Rates
- Fees
- Eligibility
- Regulatory status
- Product availability
33. Source Conflict Can Reduce Recommendation Confidence
Generative systems may be less confident when critical information is inconsistent.
34. Financial GEO Should therefore Include Canonical Fact Management
Organisations should maintain clear sources of truth for high-value product and regulatory facts.
35. High-Change Financial Information Requires Strong Governance
Examples include:
- Interest rates
- Fees
- Promotional terms
- Eligibility criteria
- Product availability
36. Freshness Is Therefore a Financial GEO Signal
Old financial information can become actively misleading.
37. Financial GEO Should Prioritise Current Information
A useful relationship is:
Accuracy + Freshness + Evidence + Authority → Reliable Financial Representation
38. Citation Eligibility Is Another Core Financial GEO Layer
Financial content may be visible without being explicitly cited.
39. Citation Eligibility Depends on Multiple Factors
A useful conceptual model is:
Relevance + Clarity + Evidence + Authority + Freshness
40. Relevance
The source should directly address the financial question being asked.
41. Clarity
Important information should be explicit and easy to interpret.
42. Evidence
Claims should be supported by appropriate data or authoritative sources.
43. Authority
The source should have credible expertise or institutional legitimacy.
44. Freshness
Financial facts should be current where time sensitivity matters.
45. Citation Visibility Is Not the Same as Citation Authority
A provider may receive isolated citations without becoming a recurring financial source.
46. Citation Authority Develops Through Repeated Useful Reference
A useful relationship is:
Useful Financial Evidence → Citation → Repeated Reference → Greater Source Authority
47. Financial Organisations Can Create Citation Assets
These can include:
- Market research
- Financial statistics
- Consumer studies
- Payment data
- Original frameworks
48. Original Financial Research Can Strengthen GEO
Research creates evidence that other organisations may reference.
49. Financial Research Should Be Methodologically Clear
Strong research can explain:
- Sample
- Method
- Measurement period
- Definitions
- Limitations
50. Research Findings Should Be Separated from Interpretation
This makes the evidence easier to assess and cite.
51. Financial GEO Should Include Provider Comparison Visibility
AI systems may construct shortlists of providers rather than simply return individual pages.
52. Provider Comparison Visibility Means Entering the Relevant Decision Set
The provider becomes one of the organisations evaluated for a specific customer scenario.
53. Financial Comparison Sets Are Contextual
Different providers may appear depending on:
- Customer type
- Product
- Risk profile
- Location
- Budget
54. Comparison Visibility Should therefore Be Segmented
A provider can be highly visible in one product category and largely absent in another.
55. Financial Recommendation Visibility Is More Selective Than Comparison Visibility
Being compared does not mean being recommended.
56. Recommendation Requires Provider Fit
A useful relationship is:
Customer Scenario → Product Fit → Eligibility Fit → Trust Evidence → Commercial Fit → Provider Recommendation
57. Customer Scenario Is the Starting Point
A recommendation depends on who the customer is and what they need.
58. Customer Context Can Include
- Personal or business
- Financial objective
- Location
- Income or turnover
- Credit profile
- Risk preference
59. Product Fit Evaluates Functional Suitability
The product should solve the customer’s actual financial need.
60. Eligibility Fit Evaluates Whether the Customer Can Realistically Apply
Relevant criteria can include:
- Age
- Residence
- Income
- Business type
- Credit requirements
61. Regulatory Fit Evaluates Legal Availability
A provider may not be able to serve every jurisdiction or customer category.
62. Commercial Fit Evaluates Practical Suitability
Relevant considerations can include:
- Price
- Rates
- Fees
- Contract terms
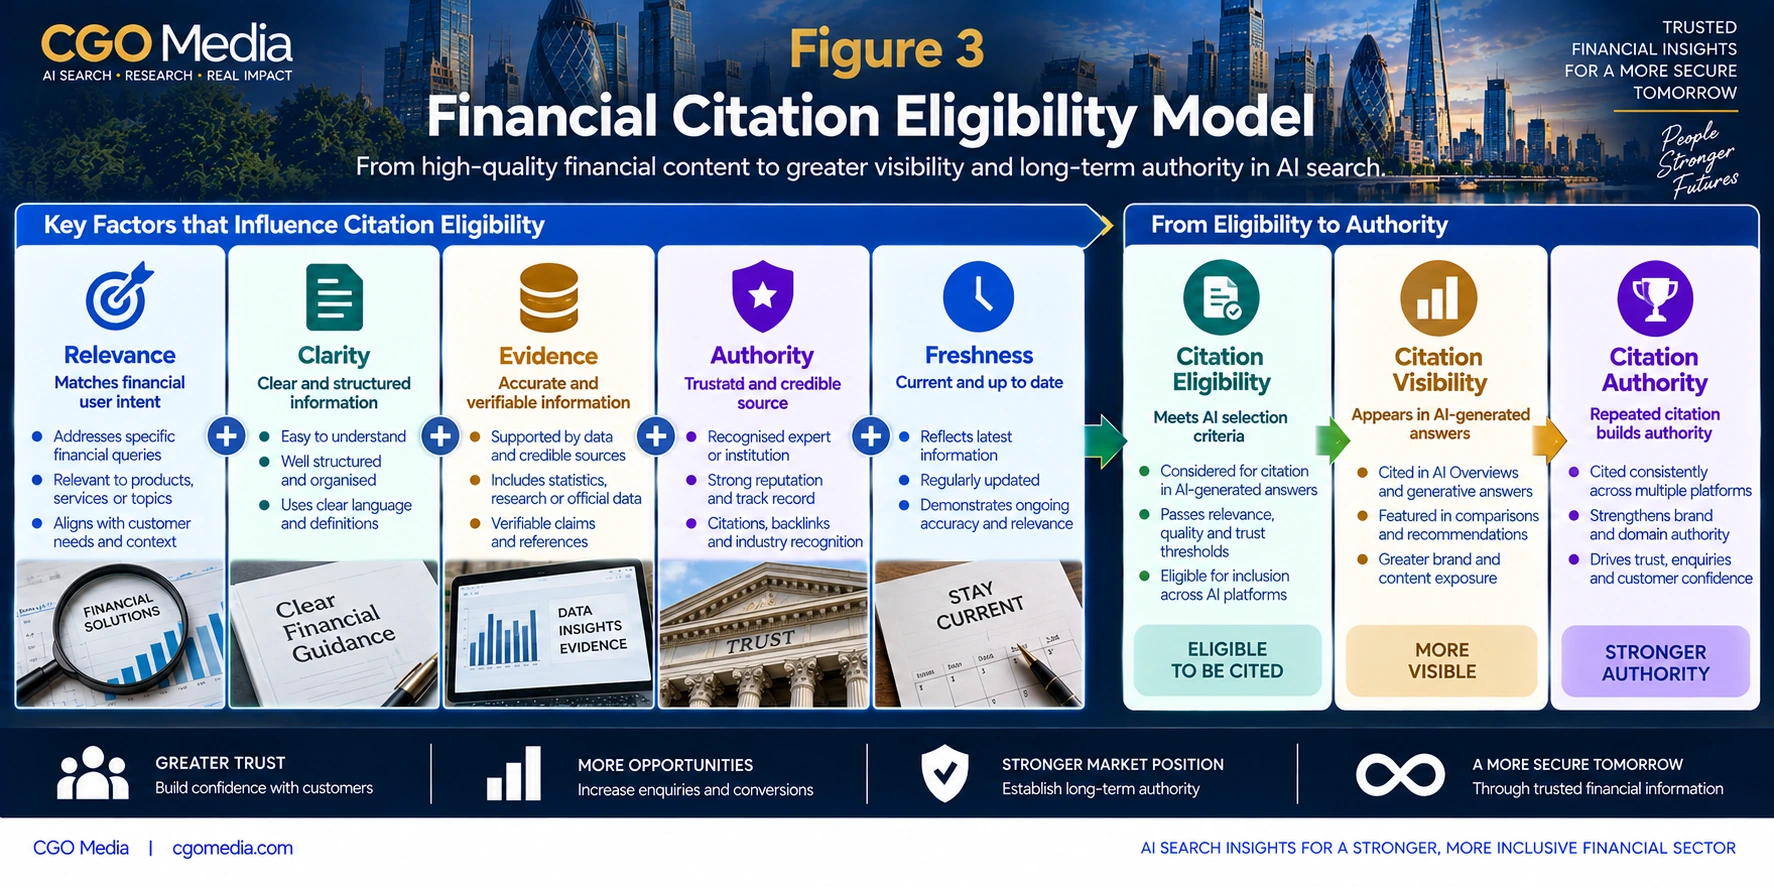
- Service model
63. Trust Fit Evaluates Provider Confidence
Relevant evidence can include:
- Regulatory status
- Customer protection
- Independent reputation
- Operational history
64. Recommendation Confidence Is Therefore Multi-Dimensional
A useful relationship is:
Customer Relevance + Product Fit + Eligibility Fit + Regulatory Confidence + Commercial Fit + External Validation
65. Financial GEO Should Not Aim for Universal Recommendation
A provider should not appear in scenarios where the product is unsuitable.
66. Appropriate Exclusion Can Be Positive
The provider may correctly be omitted where:
- The customer is ineligible
- The product is unavailable
- The risk profile is unsuitable
- The jurisdiction does not match
67. Qualified Recommendation Visibility Is the Better Objective
This can be represented as:
Relevant Inclusion + Accurate Product Representation + Strong Trust Evidence + Appropriate Customer Fit
68. Financial GEO Should Measure Multiple Visibility Layers
A useful model includes:
- Source Visibility
- Citation Visibility
- Entity & Product Accuracy
- Comparison Visibility
- Recommendation Visibility
69. Source Visibility
Measures whether provider information contributes to generated financial answers.
70. Citation Visibility
Measures whether provider, research or product sources are explicitly referenced.
71. Entity & Product Accuracy
Measures whether the organisation, regulated entity, products, terms and eligibility are represented correctly.
72. Comparison Visibility
Measures whether the provider enters relevant financial consideration sets.
73. Recommendation Visibility
Measures whether the provider is appropriately recommended within customer scenarios.
74. These Measures Should Remain Separate
Strong source visibility does not necessarily imply strong recommendation visibility.
75. Financial GEO Should Begin with a Scenario Library
Monitoring should be based on realistic customer decisions.
76. Financial Scenario Categories Can Include
- Banking
- Insurance
- Lending
- Investments
- Payments
- Fintech
77. Banking Scenarios Can Include
- Current accounts
- Business accounts
- Savings
- International banking
78. Insurance Scenarios Can Include
- Health insurance
- Life insurance
- Business insurance
- Travel insurance
79. Lending Scenarios Can Include
- Personal loans
- Business loans
- Mortgages
- Asset finance
80. Investment Scenarios Can Include
- Investment platforms
- Advisory services
- Pensions
- Wealth management
81. Payments Scenarios Can Include
- Merchant acquiring
- Online payments
- Payment gateways
- Cross-border payments
82. Fintech Scenarios Can Include
- Digital banking
- Automated investing
- Financial management software
- Alternative lending
83. Scenario Libraries Should Reflect Customer Journey Stage
Relevant stages can include:
- Discovery
- Education
- Comparison
- Selection
- Application
84. Discovery Questions Are Broad
Examples can concern:
- Types of providers
- Types of products
- General financial options
85. Education Questions Seek Understanding
They can concern:
- Fees
- Risk
- Eligibility
- Regulation
- Product differences
86. Comparison Questions Create Provider Sets
These questions can have significant commercial importance.
87. Selection Questions Ask Which Provider Fits Best
These are often the most recommendation-sensitive.
88. Application Questions Concern Practical Next Steps
Examples can include:
- Documents required
- Eligibility
- Application process
- Decision times
89. Financial GEO Monitoring Should Include Accuracy
Accuracy should be assessed across:
- Entity
- Product
- Regulatory status
- Eligibility
- Commercial terms
90. Regulatory Errors Should Receive High Priority
Incorrect regulatory representation can create substantial trust and compliance risk.
91. Product Errors Can Also Be High-Risk
Examples include:
- Incorrect rates
- Incorrect fees
- Incorrect eligibility
- Incorrect product availability
92. Financial GEO Risk Should therefore Be Weighted
A useful relationship is:
Severity + Persistence + Customer Impact + Regulatory Importance
93. Severity Measures Potential Harm
Some errors are materially more serious than others.
94. Persistence Measures Repetition
A recurring error may indicate a deeper information problem.
95. Customer Impact Measures Decision Consequence
Incorrect information can affect whether a user applies, purchases or invests.
96. Regulatory Importance Measures Compliance Sensitivity
Certain claims require especially careful treatment.
97. Financial GEO Should Prioritise High-Risk Information
These can include:
- Regulatory status
- Product risk
- Fees
- Rates
- Eligibility
98. Financial GEO Should Be Cross-Functional
It should not sit solely within SEO.
99. Relevant Financial GEO Functions Can Include
- SEO
- Marketing
- Compliance
- Legal
- Product
- Research
100. SEO Can Coordinate Discovery Intelligence
SEO can connect search behaviour, information architecture and generative visibility.
101. Compliance Can Validate Regulatory Claims
Compliance should help ensure critical information remains accurate and appropriately presented.
102. Product Teams Can Validate Product Truth
They can confirm:
- Features
- Eligibility
- Rates
- Fees
- Availability
103. Legal Teams Can Support High-Risk Claims
This is particularly important where product, regulatory or risk statements have legal implications.
104. Research Teams Can Strengthen Citation Authority
Original financial research can create externally useful evidence.
105. Marketing Can Improve Clarity and Distribution
Marketing can connect:
- Product information
- Research
- External communications
- Customer education
106. Financial GEO Should Be Governed
Critical financial information should have:
- Owner
- Source
- Review frequency
- Escalation route
107. High-Change Financial Facts Need Frequent Review
Rates, fees, availability and promotional terms can change quickly.
108. Stable Financial Facts May Require Less Frequent Review
Examples can include:
- Institutional history
- Long-standing licences
- Foundational product categories
109. Financial GEO Should Begin with Baseline Measurement
An organisation should understand its current:
- Source presence
- Citation visibility
- Entity accuracy
- Comparison presence
- Recommendation visibility
110. Baseline Measurement Should Be Segmented
Financial GEO should be assessed by:
- Product
- Customer type
- Market
- Journey stage
- AI environment
111. The First Financial GEO Principle
Financial GEO should begin with clear provider, product and regulated-entity relationships because generative systems cannot reliably compare, cite or recommend financial organisations when basic identity, product ownership and jurisdiction remain ambiguous.
112. The Second Financial GEO Principle
Financial GEO should be evidence-led, with material claims supported by current regulatory, product, trust and independent evidence appropriate to the customer’s financial decision and the potential risk of misinformation.
113. The Third Financial GEO Principle
Financial GEO should optimise for qualified visibility rather than maximum mentions, distinguishing source presence, citation, accurate product representation, comparison inclusion and appropriate provider recommendation according to real customer fit.
114. The Fourth Financial GEO Principle
Financial GEO should be governed cross-functionally because high-value financial information spans SEO, product, compliance, legal, research and marketing, with higher-risk regulatory and commercial facts requiring clear ownership, review and escalation.
115. The Financial GEO Ecosystem
The core relationship can be summarised as:
Entity Clarity → Product Clarity → Regulatory & Trust Evidence → Source Authority → Citation Eligibility → Customer Fit → Recommendation Confidence → GEO Visibility
116. The Strategic Implication
Financial services organisations should treat Generative Engine Optimisation as an extension of financial SEO, product information governance, regulatory trust, entity management, research and provider-authority strategy, building an evidence-rich information system that makes the organisation easier to identify, verify, cite, compare and recommend appropriately across AI-assisted financial discovery environments.
117. Financial Generative Source Selection
Generative systems may draw from multiple sources when answering financial questions, comparing providers or explaining products.
118. Financial Source Selection Is Contextual
The most appropriate source depends on the financial question being asked.
119. A Useful Financial Source Selection Model Is
Customer Context → Candidate Sources → Product Relevance → Regulatory Evidence → Authority → Source Convergence → Source Selection
120. Customer Context Comes First
A financial question cannot be evaluated in isolation from the customer’s situation.
121. Customer Context Can Include
- Personal or business use
- Location
- Financial objective
- Risk profile
- Eligibility
- Product category
122. Different Contexts Produce Different Source Needs
A mortgage question may require different evidence from a merchant-acquiring question.
123. Candidate Sources Are the Information Pool
These are the sources potentially available to support the generated answer.
124. Candidate Financial Sources Can Include
- Provider websites
- Regulators
- Government websites
- Comparison platforms
- Financial media
- Professional associations
- Research reports
- Consumer organisations
125. Provider Websites Are Important for First-Party Product Truth
They can provide current information about:
- Product features
- Fees
- Rates
- Eligibility
- Application processes
126. Provider-Owned Information Has Limits
First-party sources cannot independently validate every trust or comparative claim.
127. Regulatory Sources Can Validate Provider Legitimacy
They can provide evidence concerning:
- Authorisation
- Registration
- Licensing
- Jurisdiction
- Regulatory status
128. Regulatory Sources Are Particularly Important for High-Risk Claims
Provider identity and authorisation should not depend only on commercial marketing pages.
129. Government Sources Can Support Financial Context
Government information may support:
- Consumer protection
- Tax information
- Financial regulation
- Policy
- Public guidance
130. Comparison Platforms Can Support Market Comparison
They may provide structured information across multiple providers.
131. Comparison Platforms Should Be Evaluated Carefully
Their usefulness can depend on:
- Coverage
- Freshness
- Commercial model
- Methodology
- Independence
132. Financial Media Can Support Market Authority
Relevant publications may contribute:
- Market context
- Provider analysis
- Industry developments
- Expert commentary
133. Professional Organisations Can Support Specialist Financial Claims
They may provide evidence around:
- Professional standards
- Industry guidance
- Technical terminology
- Best practice
134. Consumer Organisations Can Support Customer-Focused Evidence
They may provide:
- Consumer guidance
- Risk warnings
- Product comparisons
- Complaint information
135. Research Sources Can Support Broader Financial Understanding
Useful research can include:
- Market studies
- Consumer surveys
- Payment data
- Credit research
- Investment research
136. Product Relevance Filters Candidate Sources
A source may be authoritative yet still be irrelevant to the specific product question.
137. Product Relevance Should Be Specific
A generic provider homepage may be less useful than a dedicated product page.
138. Product-Specific Sources Can Include
- Product pages
- Pricing pages
- Eligibility pages
- Terms and conditions
- Product documentation
139. Financial Questions Often Require Granular Sources
The relevant answer may depend on one specific:
- Account
- Policy
- Loan
- Investment product
- Payment service
140. Granularity Reduces Product Confusion
Providers should avoid grouping materially different products into ambiguous descriptions.
141. Product Relevance Can Be Represented as
Customer Need → Product Type → Product Variant → Eligibility → Terms → Relevance
142. Regulatory Evidence Is a Distinct Source Selection Layer
Financial source selection should consider whether regulatory claims are externally verifiable.
143. Regulatory Validation Can Include
- Licence verification
- Authorisation status
- Regulatory jurisdiction
- Professional registration
144. Regulatory Clarity Reduces Entity Confusion
It helps distinguish:
- Brand
- Legal entity
- Licensed entity
- Parent company
145. Regulatory Source Selection Should Be Jurisdiction-Aware
The relevant regulator may differ by country, product and customer type.
146. Cross-Border Financial Services Require Additional Care
A provider may be permitted to offer one product in one market but not another.
147. Source Selection Should Therefore Include Geographic Relevance
A useful relationship is:
Provider + Product + Jurisdiction + Customer Type → Applicable Regulatory Evidence
148. Authority Is Another Source Selection Factor
Not every source should carry equal evidential weight.
149. Source Authority Can Derive from
- Regulatory status
- Institutional expertise
- Editorial standards
- Research quality
- Professional credibility
150. Authority Should Be Relevant to the Claim
A strong media publication may be authoritative for market analysis but not the primary source for current product fees.
151. Claim-Specific Authority Is More Useful Than Generic Authority
The best source is often the one most authoritative for the exact financial fact.
152. First-Party Authority Is Strong for Product Truth
Providers are normally authoritative for their current:
- Features
- Pricing
- Eligibility
- Application process
153. Regulatory Authority Is Strong for Authorisation Truth
Regulators are normally more authoritative for regulatory status.
154. Independent Authority Is Strong for Comparative Context
External sources can strengthen:
- Market comparison
- Reputation
- Industry standing
- Consumer perspective
155. Financial Source Selection Should Use Multiple Source Roles
A robust answer may depend on several complementary source types.
156. A Financial Source Role Model Can Include
- Provider for product facts
- Regulator for legitimacy
- Independent source for comparison
- Research source for evidence
157. Source Convergence Strengthens Financial Confidence
Confidence increases when independent credible sources materially agree.
158. A Useful Source Convergence Model Is
Provider Truth + Regulatory Validation + Independent Comparison + Research Evidence
159. Source Convergence Does Not Require Identical Wording
Different sources can describe the same underlying fact differently.
160. Material Agreement Is More Important Than Exact Language
Sources should agree on substantive facts such as:
- Product availability
- Regulatory status
- Eligibility
- Fees
- Risk
161. Source Conflict Should Trigger Investigation
Financial organisations should identify when public sources disagree materially.
162. Common Financial Source Conflicts Can Include
- Old interest rates
- Outdated fees
- Incorrect eligibility
- Legacy product names
- Old regulatory descriptions
163. Legacy Financial Content Is a Significant Source Risk
Old product pages can remain discoverable long after an offer has changed.
164. Legacy Pages Should Be Governed
Organisations should decide whether old content should be:
- Updated
- Redirected
- Archived clearly
- Removed from active discovery
165. Archived Financial Information Should Be Clearly Identified
Historical information should not be mistaken for current product truth.
166. Freshness Is Particularly Important in Financial Source Selection
Rates, fees and promotional terms can change frequently.
167. Freshness Should Be Matched to Information Volatility
A useful relationship is:
Rate of Change + Customer Impact + Financial Risk → Required Freshness
168. High-Volatility Information Requires Frequent Updating
Examples include:
- Interest rates
- Exchange rates
- Fees
- Promotional offers
- Eligibility thresholds
169. Lower-Volatility Information May Change Less Frequently
Examples can include:
- Company history
- Core product category
- Established regulatory framework
170. Freshness Signals Should Be Explicit
Financial pages can benefit from clear:
- Published dates
- Updated dates
- Effective dates
- Review dates
171. Effective Dates Are Particularly Important for Financial Terms
They help distinguish between historic and current pricing or conditions.
172. Source Selection Should Consider Information Extractability
Relevant facts should be easy to identify within the page.
173. Important Financial Facts Should Not Be Buried
Key information such as:
- Fees
- Rates
- Eligibility
- Risk
- Regulatory status
should be presented clearly.
174. Extractability Improves Source Utility
Well-structured information is easier for users and automated systems to interpret.
175. Financial Pages Should Use Explicit Statements
For example:
This product is available to UK-resident businesses with an annual turnover above the stated threshold.
176. Explicit Statements Reduce Inference Risk
Generative systems should not need to infer critical eligibility or product facts from vague marketing language.
177. Conditional Financial Claims Should Be Clearly Qualified
Providers should distinguish:
- Guaranteed
- Indicative
- Variable
- Subject to eligibility
- Subject to market conditions
178. Ambiguous Conditional Language Can Distort AI Answers
The difference between “available” and “may be available subject to approval” can be commercially significant.
179. Financial GEO Should therefore Use Claim Precision
Important product claims should communicate conditions explicitly.
180. Source Selection Can Be Weakened by Overly Promotional Content
Pages dominated by marketing claims may provide less usable factual evidence.
181. Financial Content Should Balance Persuasion and Evidence
Commercial pages should still provide:
- Clear facts
- Terms
- Eligibility
- Limitations
- Evidence
182. Source Selection Can Also Be Weakened by Thin Content
A page may be relevant but lack enough information to support a confident answer.
183. Thin Product Pages Can Omit Critical Decision Information
Examples include:
- No eligibility detail
- No pricing explanation
- No risk explanation
- No regulatory context
184. Financial GEO Should Identify Source Gaps
A source gap exists when important customer questions lack a strong authoritative source.
185. Source Gap Analysis Can Begin with Customer Questions
The organisation can map:
Customer Question → Required Fact → Best Source → Existing Source → Gap
186. Common Financial Source Gaps Can Include
- Eligibility explanations
- Product comparisons
- Fee explanations
- Risk guidance
- Regulatory explanations
187. Source Gaps Can Create External Dependence
If the provider does not explain a product clearly, external sources may become the dominant information source.
188. External Dependence Is Not Always Negative
Independent sources can strengthen trust and comparison visibility.
189. Excessive External Dependence Can Reduce Provider Control
The organisation may struggle to correct inaccurate or outdated third-party information.
190. Financial GEO Should therefore Build Strong First-Party Sources
Critical product facts should have authoritative owned pages.
191. First-Party Sources Should Be Reinforced Externally
The strongest environment combines owned clarity with independent validation.
192. Source Selection Should Also Consider Research Methodology
Research-based financial claims should explain how evidence was produced.
193. Strong Financial Research Methodology Can Include
- Sample size
- Sample definition
- Measurement period
- Collection method
- Limitations
194. Methodological Transparency Improves Citation Utility
Researchers, journalists and AI systems can assess the evidence more confidently.
195. Financial Statistics Should Define Their Scope
A number should make clear whether it refers to:
- Consumers
- Businesses
- UK respondents
- Global respondents
- A particular time period
196. Unscoped Statistics Can Be Misused
Generative systems may generalise a narrow statistic beyond its intended population.
197. Financial GEO Should therefore Encourage Data Precision
Useful evidence should make its boundaries explicit.
198. Source Selection Should Include Independent Validation
Important claims may become stronger when supported by external organisations.
199. Independent Validation Can Include
- Regulator references
- Government sources
- Professional bodies
- Media references
- Research citations
200. Independent Validation Strengthens Source Convergence
It reduces dependence on the provider’s own claims.
201. Financial Media Authority Should Be Assessed by Relevance
A specialist financial publication may carry greater subject value than a general publication for a technical product claim.
202. Professional Authority Should Also Be Claim-Specific
A professional association can be useful for standards or terminology within its area of expertise.
203. Financial Source Selection Should Consider Source Recurrence
A source repeatedly appearing across related questions may have stronger practical authority.
204. Source Recurrence Can Be Monitored
The organisation can track:
- Which sources recur
- For which products
- For which customer scenarios
- In which AI environments
205. Recurring Competitor Sources Can Reveal Authority Gaps
If a competitor’s research, guides or product pages repeatedly appear where the organisation does not, this can indicate a source-strength gap.
206. Financial GEO Should Include Source Competitor Analysis
This differs from conventional ranking analysis.
207. Source Competitor Analysis Asks
- Which sources are selected?
- Which organisations are cited?
- Which content formats recur?
- Which evidence types dominate?
208. Source Competitors May Differ from Commercial Competitors
Financial information can be supplied by:
- Regulators
- Publishers
- Comparison websites
- Research organisations
- Consumer groups
209. This Makes Financial GEO a Source-Ecosystem Discipline
Providers compete for visibility within a wider information environment.
210. Financial Source Authority Can Be Distributed
No single source type necessarily dominates every stage of financial discovery.
211. Discovery May Favour Educational Sources
Early-stage customers may need explanations and definitions.
212. Comparison May Favour Structured Market Sources
Mid-stage customers may need comparative data.
213. Selection May Favour First-Party and Regulatory Sources
Late-stage decisions may depend on current product truth and provider legitimacy.
214. Financial GEO Should therefore Map Source Role by Journey Stage
A useful structure is:
Discovery Source → Education Source → Comparison Source → Validation Source → Selection Source
215. Source Role Mapping Can Improve Content Strategy
Providers can identify where they need stronger information assets.
216. Source Role Mapping Can Improve Digital PR
The organisation can target external authority where independent validation matters most.
217. Source Role Mapping Can Improve Research Strategy
Research can be developed around gaps where credible evidence is lacking.
218. Financial GEO Should Maintain a Source Inventory
The inventory can record:
- Source
- Source type
- Product relevance
- Authority role
- Freshness
- Risk
219. Source Inventories Help Identify Weakness
For example:
- No strong eligibility source
- No current fee source
- No independent trust source
- No strong research source
220. Source Inventories Also Help Identify Duplication
Multiple pages may provide inconsistent versions of the same product fact.
221. Duplicate Financial Facts Should Be Governed Carefully
Critical information should have clear canonical ownership.
222. Canonical Fact Management Can Include
- Primary owner
- Primary URL
- Effective date
- Review cadence
- Dependent pages
223. Canonical Fact Management Reduces Internal Source Conflict
This is particularly useful for high-change products.
224. Source Selection Should Be Tested Over Time
A source that appears today may not remain influential.
225. Longitudinal Source Monitoring Can Reveal
- Source persistence
- Source replacement
- New authority sources
- Competitor growth
226. Source Persistence Can Indicate Durable Authority
Repeated selection across time can be more meaningful than one isolated appearance.
227. Source Replacement Can Reveal Information Change
A previously dominant source may lose visibility because:
- It became outdated
- A stronger source emerged
- The product changed
- The AI environment changed
228. Financial GEO Should Distinguish Source Visibility from Source Dependence
A provider can be visible without being the principal source used to construct an answer.
229. Source Dependence Is Harder to Observe Directly
Not all generative systems expose their full retrieval process.
230. Financial GEO Should therefore Use Observable Evidence Carefully
Useful observations can include:
- Explicit citations
- Repeated factual alignment
- Recurring source inclusion
- Provider representation patterns
231. Source Analysis Should Avoid Overclaiming Causation
A source appearing near an answer does not always prove that every statement came from that source.
232. Financial GEO Should Focus on Source Eligibility and Authority
The practical objective is to make important financial information strong enough to be considered by generative systems.
233. Source Eligibility Can Be Strengthened Through
- Relevance
- Clarity
- Evidence
- Authority
- Freshness
234. Source Authority Can Be Strengthened Through
- Original research
- External citations
- Regulatory validation
- Expert contribution
- Consistent product truth
235. Source Convergence Can Be Strengthened Through Governance
Provider, regulatory and independent information should materially align.
236. Financial GEO Teams Should Review High-Value Source Areas First
Priority source areas can include:
- Regulation
- Eligibility
- Pricing
- Risk
- Product availability
237. Financial Source Risk Should Be Prioritised
A useful model is:
Source Importance + Error Severity + Persistence + Customer Impact
238. High-Risk Source Problems Should Trigger Escalation
These can require involvement from:
- Compliance
- Product
- Legal
- SEO
- Marketing
239. Financial Source Selection Should Be Treated as a Strategic Capability
It connects content, regulation, product truth, research and external authority.
240. The Fifth Financial GEO Principle
Financial generative source selection should be evaluated according to customer context and claim type, recognising that provider-owned sources are strongest for product truth, regulators for authorisation, independent sources for comparison and research sources for broader evidence.
241. The Sixth Financial GEO Principle
Financial source authority should be claim-specific rather than generic, with the strongest source being the one most authoritative, relevant, current and evidentially appropriate for the particular financial fact being presented.
242. The Seventh Financial GEO Principle
Financial GEO should strengthen source convergence by aligning provider information, regulatory validation, independent comparison and research evidence while actively identifying outdated, conflicting or ambiguous information that can reduce recommendation confidence.
243. The Eighth Financial GEO Principle
Financial organisations should treat source selection as an ongoing source-ecosystem discipline, monitoring which provider, regulatory, comparison, research and media sources recur across customer journeys and strengthening the source assets most important to qualified financial discovery.
244. The Financial Generative Source Selection Model
The complete model can be summarised as:
Customer Context → Candidate Sources → Product Relevance → Regulatory Evidence → Authority → Source Convergence → Source Selection
245. The Strategic Implication
Financial organisations should build a governed source environment in which product facts are precise, regulatory status is externally verifiable, high-change information remains current, research is methodologically transparent and independent sources materially reinforce provider claims, increasing the likelihood that trustworthy financial information can be selected and used across generative search and AI-assisted financial discovery.
246. Financial Citation Eligibility
A financial source can be visible within generative search without being explicitly cited.
247. Citation Visibility Is a Distinct Financial GEO Outcome
Citation occurs when a generative system explicitly references a source as supporting evidence for part of an answer.
248. Citation Eligibility Describes the Conditions That Make a Source More Suitable for Reference
A useful model is:
Relevance + Clarity + Evidence + Authority + Freshness → Citation Eligibility
249. Citation Eligibility Is Not Guaranteed Citation
A source can meet strong quality standards without being selected in every answer.
250. Citation Selection Is Contextual
The same source may be useful for one financial question and irrelevant for another.
251. Financial Citation Relevance
The source should address the exact customer or financial question.
252. Relevance Should Be Product-Specific Where Necessary
A broad banking page may be less useful than a specific current-account or mortgage page.
253. Relevance Should Also Reflect Customer Type
A source written for consumers may be unsuitable for:
- SMEs
- Enterprise customers
- Institutional investors
- Professional intermediaries
254. Financial Citation Clarity
Important facts should be explicit enough to extract and interpret confidently.
255. Clarity Can Include
- Clear definitions
- Explicit rates
- Explicit fees
- Eligibility statements
- Risk explanations
256. Ambiguous Financial Language Reduces Citation Utility
A source should not force the reader or system to infer important conditions.
257. Financial Citation Evidence
Claims should be supported by appropriate evidence.
258. Evidence Can Include
- Regulatory records
- Primary data
- Research methodology
- Audited information
- Independent validation
259. Evidence Should Match the Claim
Different claims require different forms of proof.
260. Regulatory Claims Require Regulatory Evidence
Provider statements alone are not always sufficient.
261. Market Claims Require Market Evidence
Statements about:
- Market share
- Consumer behaviour
- Payment trends
- Investment activity
should be supported by suitable data.
262. Product Claims Require Product Evidence
Claims about:
- Rates
- Fees
- Features
- Eligibility
- Terms
should be connected to current product information.
263. Financial Citation Authority
Authority reflects whether the source has credible expertise or institutional legitimacy.
264. Authority Can Be Institutional
Examples include:
- Regulators
- Government bodies
- Established financial institutions
- Professional associations
265. Authority Can Be Editorial
Financial publications can develop authority through:
- Specialist expertise
- Editorial standards
- Fact checking
- Consistent financial coverage
266. Authority Can Be Research-Based
A financial organisation can become authoritative by publishing useful original evidence.
267. Financial Citation Freshness
Freshness is particularly important where financial facts change quickly.
268. High-Freshness Citation Areas Can Include
- Interest rates
- Fees
- Promotional terms
- Product availability
- Eligibility thresholds
269. Lower-Freshness Citation Areas Can Include
- Foundational definitions
- Long-term research
- Historical analysis
- Established regulatory concepts
270. Citation Freshness Should Be Proportionate to Volatility
A useful principle is:
Information Volatility + Customer Impact + Financial Risk → Freshness Requirement
271. Financial Citation Eligibility Should Be Evaluated at Page Level
Some pages can be highly citable even if the organisation as a whole has limited citation authority.
272. Page-Level Citation Eligibility Can Depend on
- Topic relevance
- Evidence depth
- Clarity
- Methodology
- Freshness
273. Organisation-Level Citation Authority Is Broader
It can reflect repeated use of the provider as a source across multiple financial topics.
274. Page-Level Eligibility and Organisation-Level Authority Should Be Distinguished
A useful relationship is:
Citable Page → Repeated Citation → Wider Source Recognition → Citation Authority
275. First-Party Financial Sources Have Important Citation Roles
Providers are normally authoritative for their own:
- Products
- Pricing
- Eligibility
- Terms
- Processes
276. First-Party Sources Also Have Limitations
They should not be treated as independent proof of every comparative or trust claim.
277. Independent Financial Sources Can Provide External Validation
These can include:
- Regulators
- Government agencies
- Financial media
- Professional bodies
- Research organisations
278. The Strongest Citation Environment Can Combine First-Party and Independent Evidence
A useful model is:
First-Party Product Truth + Independent Regulatory & Market Validation
279. Original Financial Research Can Create Citation Opportunity
Research gives other organisations something specific to reference.
280. Useful Financial Research Topics Can Include
- Consumer financial behaviour
- SME payment trends
- Banking adoption
- Insurance behaviour
- Investment behaviour
- Payment technology
281. Financial Research Should Answer Questions That Matter Externally
Research created only to promote a product may have limited citation utility.
282. Citation-Oriented Research Should Provide New Evidence
Useful outputs can include:
- New statistics
- Trend analysis
- Benchmark data
- Customer behaviour findings
- Industry comparisons
283. Financial Research Methodology Should Be Transparent
A strong methodology can state:
- Research objective
- Sample size
- Sample definition
- Market
- Collection period
- Limitations
284. Methodological Transparency Supports Citation Confidence
Journalists, analysts, researchers and AI systems can evaluate the evidence more easily.
285. Findings Should Be Distinct from Interpretation
The research should distinguish:
- What the data shows
- What the organisation believes it means
286. Financial Statistics Should Include Definitions
Terms such as:
- Digital payment
- Active customer
- Default
- Investment account
- Business user
should be defined where ambiguity is possible.
287. Financial Data Should Include Time Context
A figure without a measurement period can quickly become misleading.
288. Financial Data Should Include Geographic Scope
Findings from one market should not automatically be generalised internationally.
289. Financial Data Should Include Population Scope
Research should distinguish between:
- Consumers
- Businesses
- Investors
- Merchants
- Financial professionals
290. Clear Scope Improves Citation Precision
It reduces the risk that evidence is reused outside its intended context.
291. Financial Research Assets Should Use Stable URLs
Persistent locations make long-term citation more reliable.
292. Research URLs Should Avoid Unnecessary Replacement
Replacing a cited URL can weaken historical references.
293. Versioning Can Be Useful for Updated Financial Research
Organisations can distinguish between:
- Original publication
- Updated edition
- New annual dataset
- Revised methodology
294. Versioning Should Preserve Historical Context
Old research should not silently become new research without explanation.
295. Financial Citation Assets Can Include More Than Research Papers
Useful assets can include:
- Statistics pages
- Glossaries
- Definitions
- Market trackers
- Frameworks
- Methodology pages
296. Financial Definitions Can Become Citation Assets
Clear explanations of complex financial concepts can be useful sources.
297. Definition Pages Should Be Precise
They should distinguish related concepts where confusion is common.
298. Financial Frameworks Can Also Become Citation Assets
Original models can help researchers and practitioners structure complex financial problems.
299. Frameworks Should Explain Their Purpose and Limitations
Conceptual models should not be presented as proven causal systems unless evidence supports that claim.
300. Expert Authority Can Strengthen Financial Citation Eligibility
Named authors can increase transparency and subject confidence.
301. Financial Expert Profiles Can Include
- Role
- Experience
- Specialism
- Professional credentials
- Research interests
302. Author Expertise Should Match the Topic
A payments specialist may be more relevant to payment infrastructure than to pension advice.
303. Financial Expert Authority Should Be Verifiable
Relevant evidence can include:
- Professional profiles
- Published work
- Conference participation
- External citations
- Professional registrations
304. Financial Citation Authority Can Be Strengthened Through Digital PR
Useful financial evidence should be distributed to relevant external audiences.
305. Digital PR Should Focus on Evidence, Not Only Brand Exposure
The strongest outreach can provide:
- Original data
- Expert commentary
- Market analysis
- Useful statistics
- Research findings
306. Financial Journalists Need Citable Material
Useful press assets should make it easy to identify:
- The finding
- The supporting number
- The methodology
- The expert
- The source URL
307. Research Press Pages Can Improve Distribution
A dedicated press environment can help journalists find:
- Research
- Statistics
- Expert contacts
- Figures
- Methodologies
308. Financial Digital PR Should Be Subject-Specific
Coverage should reinforce the financial areas where the organisation has genuine expertise.
309. Subject-Relevant References Can Strengthen Topical Association
Repeated references around payments, insurance, banking or lending can reinforce specific authority.
310. Generic Publicity Has Different Value
A high-profile mention may improve awareness without substantially strengthening financial citation authority.
311. Financial Citation Monitoring Should Be Structured
Organisations should record where their sources are referenced.
312. Citation Monitoring Can Include
- AI citations
- Media citations
- Research citations
- Professional references
- Government references
313. Citation Monitoring Should Record Source Quality
Not every reference carries equal authority.
314. Citation Quality Can Be Evaluated Through
- Relevance
- Credibility
- Context
- Independence
- Persistence
315. Citation Context Matters
A positive reference, neutral reference and critical reference should not automatically be treated as equivalent.
316. Financial GEO Should Monitor Citation Accuracy
A source can be cited while being misrepresented.
317. Citation Accuracy Can Include
- Correct statistic
- Correct date
- Correct product
- Correct market
- Correct conclusion
318. Citation Misrepresentation Should Be Investigated
The issue may originate from:
- Ambiguous source wording
- Outdated information
- Third-party reinterpretation
- Generative error
319. Citation Diversity Is Another Useful Measure
An organisation can examine whether citations come from:
- Multiple publications
- Multiple professional sources
- Multiple AI environments
- Multiple markets
320. Citation Diversity Can Reduce Dependence on One Source Environment
Broader reference patterns can create more resilient authority.
321. Citation Recency Should Also Be Monitored
An organisation may have historical citations but little current reference activity.
322. Citation Persistence Can Indicate Durable Authority
Repeated reference over time may be more meaningful than short-lived citation spikes.
323. Financial Citation Authority Can Be Product-Specific
A provider may have strong authority in one financial category and little in another.
324. Citation Monitoring Should therefore Be Segmented
Useful segments can include:
- Banking
- Insurance
- Lending
- Payments
- Investments
- Fintech
325. Citation Monitoring Can Also Be Segmented by Audience
For example:
- Consumer
- SME
- Enterprise
- Investor
- Professional
326. Financial Citation Authority Should Not Be Confused with Backlink Volume
A backlink can exist without meaningfully validating a financial claim.
327. Citation Authority Is More Contextual
It concerns whether the organisation is used as evidence within relevant financial information environments.
328. Links Can Support Citation Authority
But the strategic objective should be broader than link acquisition.
329. Financial GEO Should Track Which Assets Earn References
This can reveal what external audiences find useful.
330. High-Reference Assets Can Inform Future Research
Recurring citation patterns can identify:
- High-interest topics
- Data gaps
- Useful formats
- Authority opportunities
331. Low-Reference Assets Should Be Reviewed
The issue may concern:
- Weak evidence
- Poor distribution
- Low relevance
- Limited originality
332. Financial GEO Should Distinguish Owned Citation Assets from External Reinforcement
Owned citation assets create information worth referencing.
333. External Reinforcement Validates the Wider Authority Environment
A strong system combines both.
334. A Financial Citation Authority System Can Be Represented as
Owned Evidence → External Reference → Repeated Citation → Greater Financial Authority
335. Negative Evidence Can Also Influence Financial Authority
External sources may highlight:
- Regulatory action
- Customer complaints
- Product failures
- Security incidents
336. Negative Evidence Should Not Be Ignored
Financial GEO should account for the complete public evidence environment.
337. Trust Recovery Can Become Necessary
An organisation may need to rebuild confidence after a material issue.
338. A Financial Trust Recovery Cycle Can Be Represented as
Issue → Correction → Evidence → Communication → External Reassessment
339. Correction Comes First
Communications cannot substitute for resolving the underlying problem.
340. Evidence Should Demonstrate the Correction
Useful evidence can include:
- Regulatory confirmation
- Independent audit
- Updated policy
- Published remediation
341. Communication Should Be Clear and Proportionate
The organisation should explain what changed without overstating recovery.
342. External Reassessment May Take Time
Trust and citation authority may recover gradually.
343. Financial Citation Eligibility Should Be Designed into Content
Citable content should not be created as an afterthought.
344. Citation-Ready Financial Pages Can Include
- Clear title
- Named author
- Publication date
- Updated date
- Evidence
- References
345. Research Pages Can Also Include
- Methodology
- Definitions
- Limitations
- Downloadable figures
- Citation guidance
346. Citation Guidance Can Reduce Friction
Researchers and journalists can more easily reference the work correctly.
347. Financial Citation Assets Should Remain Accessible
Important research should not disappear behind unnecessary technical barriers.
348. Persistent Access Supports Long-Term Reference
Stable resources can continue earning citations over time.
349. Financial GEO Should Develop a Citation Asset Inventory
The inventory can include:
- Research papers
- Statistics
- Definitions
- Frameworks
- Datasets
- Expert pages
350. Citation Asset Inventories Help Identify Gaps
The organisation can determine where it lacks useful evidence.
351. Citation Asset Inventories Help Prioritise Distribution
High-value resources can receive stronger PR and outreach support.
352. Financial GEO Should Monitor Citation Competitors
The organisation should identify which external sources are repeatedly cited instead.
353. Citation Competitors Can Include
- Financial institutions
- Regulators
- Comparison platforms
- Publishers
- Research organisations
354. Citation Competitor Analysis Can Reveal Missing Evidence
Competitors may be earning citations because they provide:
- Better data
- Clearer methodology
- Stronger definitions
- More current research
355. Citation Competitor Analysis Can Reveal Format Advantage
Some sources may dominate because information is easier to extract and reuse.
356. Financial Citation Authority Should Be Built Deliberately
It can become a strategic complement to traditional SEO and Digital PR.
357. Citation Authority Can Strengthen Brand Association
Repeated reference around a financial topic can reinforce a provider’s connection with that subject.
358. Citation Authority Can Strengthen AI Source Visibility
A source with strong external recognition may have greater practical eligibility across generative environments.
359. Citation Authority Can Strengthen Recommendation Confidence Indirectly
A well-evidenced provider may be easier to validate during comparison and recommendation.
360. Citation Authority Is therefore Part of a Wider Financial GEO System
It should connect with:
- Entity clarity
- Product clarity
- Regulatory evidence
- External authority
- Recommendation visibility
361. The Ninth Financial GEO Principle
Financial citation eligibility should be built around relevance, clarity, evidence, authority and freshness, with citation readiness evaluated at page level while broader citation authority develops through repeated use of the organisation as a credible financial source.
362. The Tenth Financial GEO Principle
Financial organisations should combine first-party product truth with independent regulatory, market and professional validation, recognising that owned information is strongest for current product facts while external sources are essential for independent trust and comparative authority.
363. The Eleventh Financial GEO Principle
Original financial research should be designed as a durable citation asset, with transparent methodology, clear population and geographic scope, stable URLs, defined limitations and evidence that journalists, researchers, professionals and generative systems can interpret accurately.
364. The Twelfth Financial GEO Principle
Financial citation authority should be monitored as a quality and context signal rather than a simple backlink count, with attention to source credibility, citation accuracy, diversity, persistence, subject relevance and the wider positive or negative evidence environment around the provider.
365. The Financial Citation Eligibility Model
The complete model can be summarised as:
Relevance + Clarity + Evidence + Authority + Freshness → Citation Eligibility → Citation Visibility → Citation Authority
366. The Strategic Implication
Financial services organisations should build a portfolio of clear, evidence-rich and persistent citation assets supported by transparent methodology, named expertise, external validation and active distribution, increasing the probability that their research, product information and financial expertise can become trusted references across search, media, professional and generative information environments.
367. Financial AI Provider Recommendation
Financial provider recommendation is one of the most commercially important outcomes within generative discovery.
368. Recommendation Is More Selective Than Visibility
A provider may be visible, cited or compared without being recommended.
369. Recommendation Requires Contextual Fit
A useful model is:
Customer Scenario → Product Fit → Eligibility Fit → Regulatory & Trust Evidence → Commercial Fit → External Validation → Recommendation Confidence → Qualified Provider Recommendation
370. Customer Scenario Is the Starting Point
Financial recommendations should reflect who the customer is and what they are trying to achieve.
371. Customer Scenario Can Include
- Personal or business use
- Financial objective
- Location
- Income or turnover
- Risk profile
- Preferred service model
372. Financial Recommendation Should Not Be Provider-First
The correct starting question is not:
Which provider is most visible?
It is:
Which provider best fits this financial scenario?
373. Product Fit Is the First Recommendation Filter
The provider must offer a product capable of meeting the customer’s underlying need.
374. Product Fit Can Include
- Product category
- Product features
- Risk characteristics
- Service capability
- Use case
375. Product Category Fit Is Fundamental
A strong provider in one category may be irrelevant in another.
376. Banking Product Fit Can Include
- Current accounts
- Savings accounts
- Business banking
- International banking
377. Lending Product Fit Can Include
- Personal loans
- Business finance
- Mortgages
- Asset finance
378. Insurance Product Fit Can Include
- Life insurance
- Health insurance
- Business insurance
- Travel insurance
379. Investment Product Fit Can Include
- Investment platforms
- Managed portfolios
- Pensions
- Wealth management
380. Payments Product Fit Can Include
- Merchant acquiring
- Payment gateways
- Point-of-sale payments
- Cross-border payments
381. Product Fit Should Consider Product Variant
The existence of a broad product category does not prove that every variant fits the customer.
382. Product Features Can Create or Remove Fit
Examples include:
- Credit limit
- Transaction support
- Insurance coverage
- Investment options
- Payment methods
383. Eligibility Fit Is the Second Recommendation Filter
A financially suitable product may still be inaccessible to the customer.
384. Eligibility Can Include
- Age
- Residence
- Income
- Turnover
- Credit profile
- Business type
385. Eligibility Should Be Explicit Where Possible
Recommendation systems should not need to infer basic application requirements from incomplete information.
386. Eligibility Can Be Conditional
A provider may require:
- Credit assessment
- Affordability assessment
- Identity verification
- Business verification
- Additional documentation
387. Conditional Eligibility Should Not Be Presented as Guaranteed Acceptance
Financial GEO should preserve the distinction between eligibility and approval.
388. Geographic Eligibility Is Also Important
Products may be limited by:
- Country
- Region
- Residence
- Business registration
- Regulatory permissions
389. Regulatory Fit Is the Third Recommendation Filter
The provider must be able to serve the customer legally within the relevant jurisdiction.
390. Regulatory Fit Can Include
- Authorised entity
- Jurisdiction
- Permitted product
- Customer type
- Distribution model
391. Regulatory Fit Is Particularly Important for Cross-Border Finance
International availability should not be assumed from global brand presence.
392. Brand Presence and Regulatory Availability Are Different
A provider may market internationally while offering specific regulated services only in selected jurisdictions.
393. Recommendation Systems Need Clear Jurisdictional Evidence
The provider should make applicable market limitations explicit.
394. Trust Evidence Is the Fourth Recommendation Filter
Financial suitability involves more than functional product fit.
395. Trust Evidence Can Include
- Regulatory status
- Consumer protection
- Security standards
- Operational history
- Independent reputation
396. Trust Requirements Can Vary by Product Risk
A high-value investment decision may require stronger confidence than a low-value payment service decision.
397. High-Risk Products Need Stronger Evidence
Relevant categories can include:
- Investments
- Mortgages
- Credit
- Pensions
- Insurance
398. Financial Recommendation Confidence Should Be Risk-Sensitive
A useful principle is:
Financial Risk + Decision Consequence → Required Evidence Strength
399. Commercial Fit Is the Fifth Recommendation Filter
The product should be practically suitable as well as technically available.
400. Commercial Fit Can Include
- Price
- Fees
- Interest rate
- Contract length
- Minimum balance
- Service model
401. Price Is Not the Only Commercial Factor
A cheaper product may be less suitable if:
- Features are limited
- Service is unsuitable
- Risk is higher
- Support is weaker
402. Financial Recommendation Should Balance Cost and Suitability
Lowest price should not automatically equal best recommendation.
403. Service Model Can Influence Commercial Fit
Customers may prefer:
- Branch service
- Digital-only service
- Relationship management
- Self-service
- Broker or adviser support
404. Recommendation Should Reflect Service Expectations
A technically strong product can be a poor fit if delivery does not match customer needs.
405. External Validation Is the Sixth Recommendation Filter
Independent sources can strengthen confidence that provider claims are credible.
406. External Validation Can Include
- Regulatory records
- Professional recognition
- Independent research
- Financial media
- Consumer organisations
407. External Validation Should Be Relevant to the Decision
Different validation sources may matter for:
- Safety
- Pricing
- Performance
- Service quality
- Market standing
408. Independent Comparison Can Support Recommendation Confidence
Comparison sources can help establish:
- Relative pricing
- Feature differences
- Provider alternatives
- Market context
409. Comparison Sources Should Be Interpreted Carefully
Their commercial incentives, methodology and market coverage can affect conclusions.
410. Provider Recommendation Confidence Is Multi-Dimensional
A useful relationship is:
Customer Relevance + Product Fit + Eligibility Fit + Regulatory Confidence + Trust Evidence + Commercial Fit + External Validation
411. Recommendation Confidence Should Be Higher When Evidence Converges
Confidence increases when:
- Product information is clear
- Eligibility is explicit
- Regulation is verifiable
- Independent sources agree
412. Recommendation Confidence Should Fall When Evidence Conflicts
Conflicts can involve:
- Different fees
- Different rates
- Unclear eligibility
- Regulatory ambiguity
- Product availability
413. Recommendation Confidence Should Also Fall When Important Information Is Missing
Absence of evidence is different from negative evidence, but both can affect confidence.
414. Missing Product Information Can Cause Recommendation Exclusion
A suitable provider may not be recommended if its public information is insufficiently clear.
415. This Creates a Financial GEO Visibility Gap
The provider may be competitive in reality but poorly represented in the information environment.
416. Financial GEO Should Therefore Measure Relevant Exclusion
Relevant exclusion occurs when:
A Provider Fits the Customer Scenario but Is Not Included or Recommended
417. Relevant Exclusion Can Reveal
- Weak product clarity
- Weak external authority
- Entity ambiguity
- Insufficient trust evidence
- Source-selection weakness
418. Irrelevant Inclusion Should Also Be Monitored
A provider may be recommended where genuine fit is weak.
419. Irrelevant Inclusion Can Create Customer Risk
It can lead to:
- Wasted applications
- Unsuitable products
- Customer dissatisfaction
- Trust erosion
420. Appropriate Exclusion Is a Positive Outcome
A provider should be omitted where:
- The customer is ineligible
- The product is unavailable
- The jurisdiction is unsuitable
- The product does not match the need
421. Financial GEO Should Measure Four Recommendation Outcomes
- Relevant Inclusion
- Irrelevant Inclusion
- Relevant Exclusion
- Appropriate Exclusion
422. Relevant Inclusion Represents Qualified Recommendation Visibility
The provider appears where customer and product fit are genuine.
423. Irrelevant Inclusion Represents Recommendation Noise
Visibility exists without suitable customer fit.
424. Relevant Exclusion Represents Lost Opportunity
A suitable provider is missing from the decision set.
425. Appropriate Exclusion Represents Correct Filtering
The system avoids recommending an unsuitable provider.
426. Financial GEO Should Track Provider Comparison Sets
Recommendation normally emerges from a wider set of providers.
427. Comparison Sets Can Reveal Effective Competitors
The providers appearing together in generative answers may differ from conventional market competitors.
428. Effective Competitor Sets Can Be Product-Specific
A financial group may compete with different organisations across:
- Banking
- Lending
- Insurance
- Payments
- Investments
429. Effective Competitor Sets Can Also Be Customer-Specific
SME comparison sets may differ from consumer comparison sets.
430. Financial GEO Should Monitor Provider Co-Occurrence
Repeated co-occurrence can reveal who is being evaluated together.
431. Provider Co-Occurrence Can Reveal Market Reclassification
AI systems may group providers according to customer need rather than traditional industry categories.
432. Banks Can Be Compared with Fintech Providers
This can occur where the underlying customer need is similar.
433. Traditional Insurers Can Be Compared with Insurtech Providers
Recommendation environments can blur established market categories.
434. Traditional Payment Providers Can Be Compared with Software Platforms
Embedded finance can further blur provider boundaries.
435. Financial GEO Should Therefore Monitor Category Convergence
This helps organisations understand changing competitive context.
436. Comparison Visibility Can Also Reveal Positioning
Providers may repeatedly be framed as:
- Low-cost
- Premium
- Digital-first
- Specialist
- Flexible
- Enterprise-focused
437. Repeated Comparative Framing Can Reinforce Brand Association
Strong alignment can help clarify market position.
438. Misaligned Comparative Framing Should Be Investigated
It may indicate:
- Outdated content
- Weak positioning
- Third-party information problems
- Category confusion
439. Financial GEO Should Monitor Strength Attribution
AI systems may repeatedly associate providers with particular advantages.
440. Strength Attribution Can Include
- Price
- Service
- Product breadth
- Technology
- Specialisation
- Trust
441. Financial GEO Should Also Monitor Weakness Attribution
Repeated weaknesses can materially affect recommendation confidence.
442. Weakness Attribution Can Include
- High fees
- Limited eligibility
- Weak support
- Limited product range
- Complex terms
443. Strength and Weakness Attribution Should Be Validated Against Reality
The objective is not to remove legitimate criticism.
444. Legitimate Weaknesses Can Improve Customer Matching
Accurate limitations help unsuitable customers self-select away.
445. Financial Recommendation Quality Depends on Honest Constraint Representation
A provider should clearly communicate where its products do not fit.
446. This Can Improve Recommendation Precision
A more accurate public information environment can reduce irrelevant inclusion.
447. Financial GEO Should Segment Recommendation Monitoring by Product
A provider should not rely on one overall AI visibility score.
448. Product-Level Segmentation Can Include
- Accounts
- Loans
- Insurance
- Investment products
- Payment services
449. Recommendation Monitoring Should Also Be Segmented by Customer Type
Useful categories can include:
- Consumer
- SME
- Enterprise
- Institutional
- Professional intermediary
450. Recommendation Monitoring Should Be Segmented by Geography
Provider fit can vary across markets.
451. Recommendation Monitoring Should Be Segmented by Journey Stage
Early-stage and late-stage questions can produce different provider sets.
452. Early-Stage Questions May Produce Broad Provider Lists
These can focus on:
- Education
- Categories
- General alternatives
453. Mid-Stage Questions May Produce Comparison Sets
These can focus on:
- Fees
- Features
- Eligibility
- Provider differences
454. Late-Stage Questions May Produce Stronger Recommendations
These can focus on:
- Customer fit
- Specific use case
- Application readiness
- Final provider choice
455. Financial GEO Should Monitor Recommendation Stability
A provider appearing once may not indicate durable visibility.
456. Recommendation Stability Can Include
- Appearance frequency
- Position consistency
- Reason consistency
- Customer-fit consistency
457. Stable Recommendation Can Indicate Stronger Association
Repeated appropriate inclusion may reflect durable provider relevance.
458. Unstable Recommendation Can Indicate Weak Confidence
The provider may appear inconsistently across similar scenarios.
459. Financial GEO Should Compare Recommendation Across AI Environments
Different systems may produce different provider sets.
460. Cross-Environment Comparison Can Reveal Visibility Dependence
A provider may be strong in one platform and weak in another.
461. Financial GEO Should Avoid Treating One AI Platform as the Entire Market
Generative discovery is increasingly multi-platform.
462. Recommendation Monitoring Should therefore Be Portfolio-Based
The organisation can monitor a representative group of AI and generative search environments.
463. Recommendation Measurement Should Be Longitudinal
Repeated observations are more useful than isolated checks.
464. Longitudinal Monitoring Can Reveal
- Provider emergence
- Provider decline
- Competitor movement
- Positioning change
- Recommendation stability
465. Financial GEO Should Track Recommendation Reasons
Understanding why a provider is recommended can be as valuable as knowing whether it appears.
466. Recommendation Reasons Can Include
- Low fees
- Strong digital experience
- Specialist product
- High trust
- Broad coverage
- Customer support
467. Recommendation Reasons Can Reveal Authority Strengths
Repeated positive reasoning may show where the market recognises genuine provider advantages.
468. Recommendation Reasons Can Reveal Information Gaps
Important strengths may be absent because they are poorly evidenced publicly.
469. Financial GEO Should Compare Observed Recommendation with Strategic Positioning
The organisation can ask:
Are AI systems recommending us for the reasons we actually want to compete?
470. Misalignment Can Reveal Brand or Evidence Problems
The organisation may be known for the wrong:
- Product
- Customer segment
- Market position
- Competitive advantage
471. Financial GEO Should Connect Recommendation Intelligence to Product Strategy
Repeated customer questions can reveal unmet needs.
472. Recommendation Intelligence Can Reveal Product Demand
AI-assisted queries may highlight interest in:
- New features
- Lower fees
- Different service models
- New customer segments
473. Recommendation Intelligence Can Reveal Customer Friction
Recurring questions can expose uncertainty around:
- Eligibility
- Pricing
- Risk
- Application process
- Product differences
474. Financial GEO Can Therefore Contribute to Customer Intelligence
Its value extends beyond search visibility.
475. Financial Recommendation Monitoring Should Connect to Conversion Data
Where possible, organisations can compare visibility patterns with:
- Qualified enquiries
- Applications
- Approval rates
- Customer acquisition
476. Direct Causation Should Not Be Assumed
Financial customer journeys can involve multiple channels.
477. AI Influence Can Occur Before the Website Visit
The customer may use generative tools to narrow options before clicking any provider site.
478. This Makes Traditional Attribution Incomplete
AI influence may not always generate a directly attributable referral.
479. Financial GEO Should therefore Use Assisted Attribution Carefully
Useful supporting evidence can include:
- Customer surveys
- CRM notes
- Application questionnaires
- Search data
- AI visibility data
480. Recommendation Quality Should Ultimately Connect to Customer Outcome
A good financial recommendation should increase the probability of appropriate product fit.
481. Better Product Fit Can Reduce
- Failed applications
- Unsuitable purchases
- Customer dissatisfaction
- Service friction
482. Better Product Fit Can Improve
- Customer satisfaction
- Retention
- Product suitability
- Long-term trust
483. Positive Customer Outcomes Can Strengthen Future Authority
They may generate:
- Reviews
- Case studies
- Research evidence
- External references
484. This Can Create a Financial GEO Reinforcement Loop
A useful relationship is:
Qualified Recommendation → Better Customer Fit → Better Outcome → Stronger Evidence → Greater Authority → Better Future Recommendation Confidence
485. Financial Recommendation Governance Is Essential
Provider recommendation touches product, legal, regulatory and commercial information.
486. Recommendation Governance Can Include
- SEO
- Product
- Compliance
- Legal
- Marketing
- Customer insight
487. Product Teams Should Validate Fit Criteria
They can confirm:
- Features
- Eligibility
- Pricing
- Availability
488. Compliance Should Validate Regulatory Representation
High-risk regulatory claims require careful review.
489. Legal Should Support Material Claim Governance
Particularly where recommendation language could imply inappropriate certainty.
490. Customer Insight Teams Can Validate Real Decision Behaviour
They can contribute:
- Frequently asked questions
- Application barriers
- Customer objections
- Decision criteria
491. Financial GEO Recommendation Monitoring Should Include Escalation
Material errors should not remain within ordinary SEO reporting.
492. High-Risk Recommendation Errors Can Include
- Recommending unavailable products
- Incorrect regulatory claims
- Incorrect eligibility
- Materially wrong pricing
- Misstated risk
493. Recommendation Risk Can Be Prioritised
A useful model is:
Severity + Persistence + Customer Impact + Regulatory Importance
494. The Thirteenth Financial GEO Principle
Financial provider recommendation should begin with customer context and product fit rather than provider visibility, because qualified recommendation depends on whether the product, eligibility, regulatory environment, commercial terms and service model genuinely match the customer’s financial needs.
495. The Fourteenth Financial GEO Principle
Financial GEO should measure recommendation quality through relevant inclusion, irrelevant inclusion, relevant exclusion and appropriate exclusion, recognising that omission can be correct where customer fit is weak and that maximum recommendation frequency is not the strategic objective.
496. The Fifteenth Financial GEO Principle
Financial provider comparison and recommendation should be monitored by product, customer type, geography, journey stage and AI environment because competitive sets, eligibility, regulation and provider suitability can differ substantially across financial scenarios.
497. The Sixteenth Financial GEO Principle
The strongest financial recommendation visibility should create a reinforcing cycle in which accurate provider representation supports better customer fit, better customer outcomes produce stronger evidence and external authority, and that stronger evidence improves future recommendation confidence.
498. The Financial AI Provider Recommendation Model
The complete model can be summarised as:
Customer Scenario → Product Fit → Eligibility Fit → Regulatory & Trust Evidence → Commercial Fit → External Validation → Recommendation Confidence → Qualified Provider Recommendation
499. The Strategic Implication
Financial organisations should optimise for qualified provider recommendation rather than maximum AI inclusion, ensuring product information, eligibility, jurisdiction, regulatory status, commercial terms, limitations and external evidence are clear enough for generative systems to distinguish where the provider genuinely fits, where alternatives may be stronger and where exclusion is appropriate.
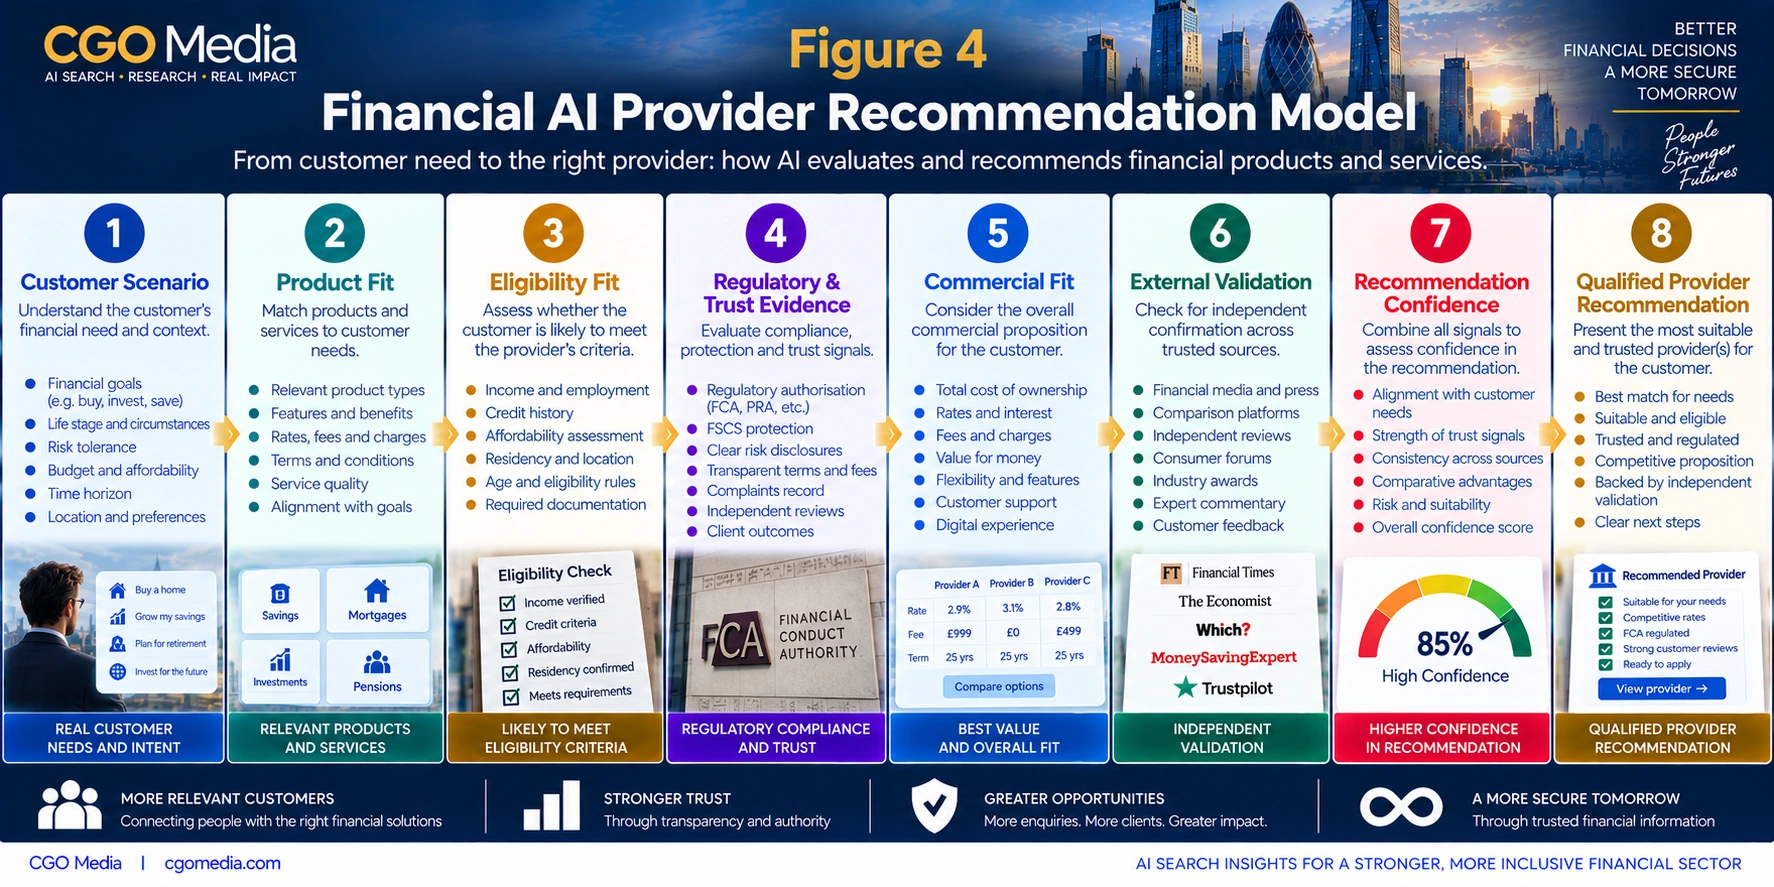
500. Financial GEO Requires a Distinct Measurement Framework
Traditional SEO metrics remain important, but they do not fully capture generative visibility.
501. Financial GEO Measurement Should Separate Visibility Layers
A useful model includes:
- Source Visibility
- Citation Visibility
- Entity & Product Accuracy
- Comparison Visibility
- Recommendation Visibility
502. Qualified Financial GEO Performance Connects These Layers
A useful relationship is:
Source Visibility → Citation Visibility → Entity & Product Accuracy → Comparison Visibility → Recommendation Visibility → Qualified Financial GEO Performance
503. Source Visibility Measures Information Presence
It evaluates whether the provider’s information appears to contribute to generated financial answers.
504. Source Visibility Can Be Explicit or Indirect
A source may be:
- Explicitly cited
- Linked
- Named
- Reflected indirectly in the answer
505. Explicit Source Visibility Is Easier to Observe
The provider can directly record when a system shows a source or link.
506. Indirect Source Influence Is Harder to Prove
Generated factual alignment does not always reveal the underlying retrieval path.
507. Financial GEO Should Avoid Overstating Source Causation
Observable patterns should be recorded without claiming proprietary system knowledge.
508. Source Visibility Should Be Measured by Scenario
A provider may have strong source presence for one product and little for another.
509. Source Visibility Segments Can Include
- Banking
- Lending
- Insurance
- Payments
- Investments
- Fintech
510. Source Visibility Should Also Be Measured by Customer Type
Relevant segments can include:
- Consumer
- SME
- Enterprise
- Institutional
- Professional intermediary
511. Citation Visibility Is a Separate Measure
It evaluates whether provider-owned or provider-associated sources are explicitly referenced.
512. Citation Visibility Should Be Measured by Citation Type
Possible categories include:
- Product citation
- Research citation
- Definition citation
- Expert citation
- Corporate citation
513. Citation Share Can Be Calculated
A simple measure is:
Citation Share = Relevant Citation Appearances ÷ Relevant Scenarios Tested
514. Citation Share Should Be Interpreted Carefully
A high citation rate does not automatically indicate strong recommendation visibility.
515. Citation Quality Should Be Recorded Alongside Citation Frequency
Useful dimensions include:
- Source relevance
- Source credibility
- Context
- Accuracy
- Freshness
516. Citation Context Can Be Positive, Neutral or Critical
These contexts should not automatically be treated as equivalent.
517. Financial GEO Should Monitor Citation Accuracy
A provider can be cited while the underlying fact is incorrect or outdated.
518. Entity Accuracy Is a Core Financial GEO Measure
It evaluates whether the organisation itself is represented correctly.
519. Entity Accuracy Can Include
- Correct company name
- Correct legal entity
- Correct brand relationship
- Correct jurisdiction
- Correct regulatory entity
520. Product Accuracy Is Equally Important
It evaluates whether the product is described correctly.
521. Product Accuracy Can Include
- Correct product name
- Correct features
- Correct fees
- Correct eligibility
- Correct availability
522. Regulatory Accuracy Should Be Assessed Separately
Material errors can include:
- Wrong regulator
- Wrong licence status
- Wrong regulated entity
- Wrong jurisdiction
523. Commercial Accuracy Should Also Be Assessed
Material errors can include:
- Wrong interest rate
- Wrong fee
- Wrong promotional term
- Wrong contract condition
524. Eligibility Accuracy Is a High-Value Measure
Incorrect eligibility can directly affect customer decision-making.
525. A Financial GEO Accuracy Score Can Include
Entity Accuracy + Product Accuracy + Regulatory Accuracy + Commercial Accuracy + Eligibility Accuracy
526. Accuracy Should Be Risk-Weighted
Not every error has the same consequence.
527. A Minor Brand Description Error May Be Low Risk
It may have limited effect on the customer’s financial decision.
528. Incorrect Regulatory Status Can Be High Risk
It can materially affect trust and compliance interpretation.
529. Incorrect Pricing Can Also Be High Risk
It can distort provider comparison and product choice.
530. Financial GEO Risk Can Be Represented as
Severity + Persistence + Customer Impact + Regulatory Importance
531. Severity Measures Potential Harm
The organisation should assess how serious the error is.
532. Persistence Measures Recurrence
A recurring error may indicate a deeper source problem.
533. Customer Impact Measures Decision Consequence
The error may affect:
- Application
- Purchase
- Investment
- Borrowing
- Insurance selection
534. Regulatory Importance Measures Compliance Sensitivity
Some information should receive immediate escalation.
535. Comparison Visibility Is Another Core Financial GEO Measure
It evaluates whether the provider enters relevant financial consideration sets.
536. Comparison Visibility Should Be Scenario-Specific
A provider may be visible in some customer scenarios but absent in others.
537. Comparison Share Can Be Calculated
A simple measure is:
Comparison Share = Relevant Comparison Appearances ÷ Relevant Comparison Scenarios Tested
538. Comparison Share Should Be Segmented
Useful segmentation can include:
- Product
- Customer type
- Market
- Risk profile
- Journey stage
539. Comparison Positioning Should Also Be Recorded
The provider may appear as:
- Primary option
- Alternative
- Specialist option
- Low-cost option
- Premium option
540. Comparison Framing Can Reveal Brand Association
Repeated language can indicate how the provider is being positioned.
541. Comparison Omission Can Be as Important as Inclusion
A relevant provider may repeatedly fail to enter the consideration set.
542. Relevant Comparison Exclusion Can Reveal
- Weak authority
- Weak product clarity
- Weak external validation
- Entity ambiguity
- Source gaps
543. Recommendation Visibility Is the Most Selective Layer
It evaluates whether the provider is appropriately recommended.
544. Recommendation Share Can Be Calculated
A simple measure is:
Recommendation Share = Relevant Recommendation Appearances ÷ Relevant Customer Scenarios Tested
545. Recommendation Share Should Not Be Maximised Blindly
A provider should not be recommended where fit is weak.
546. Recommendation Measurement Should Use Four Outcome Categories
- Relevant Inclusion
- Irrelevant Inclusion
- Relevant Exclusion
- Appropriate Exclusion
547. Relevant Inclusion Is the Preferred Outcome
The provider appears where customer fit is genuine.
548. Irrelevant Inclusion Can Represent Risk
The provider appears where:
- Eligibility is weak
- Product fit is poor
- Jurisdiction is unsuitable
- Commercial fit is weak
549. Relevant Exclusion Can Represent Lost Opportunity
The provider fits the scenario but is omitted.
550. Appropriate Exclusion Represents Correct Filtering
The provider is absent because customer fit is genuinely weak.
551. Qualified Recommendation Visibility Should therefore Be the Main Measure
A useful definition is:
Relevant Customer Scenario + Accurate Provider Representation + Strong Trust Evidence + Appropriate Inclusion
552. Financial GEO Measurement Should Begin with a Scenario Library
The quality of measurement depends heavily on the quality of tested scenarios.
553. Scenario Libraries Should Reflect Real Customer Questions
Useful sources can include:
- Search data
- Customer service questions
- Application queries
- Sales conversations
- Product research
554. Scenario Libraries Should Include Discovery Questions
These can identify whether the organisation enters broad financial research.
555. Scenario Libraries Should Include Comparison Questions
These can identify provider co-occurrence and competitive sets.
556. Scenario Libraries Should Include Selection Questions
These can test recommendation quality.
557. Scenario Libraries Should Include Eligibility Questions
These can test practical customer fit.
558. Scenario Libraries Should Include Regulatory Questions
These can test provider legitimacy and regulatory representation.
559. Scenario Libraries Should Be Segmented by Product
For example:
- Banking
- Lending
- Insurance
- Payments
- Investments
- Fintech
560. Scenario Libraries Should Be Segmented by Customer Type
Useful categories can include:
- Consumer
- SME
- Enterprise
- Institutional
- Professional
561. Scenario Libraries Should Be Segmented by Geography
Financial product availability and regulation can differ materially by market.
562. Scenario Libraries Should Be Segmented by Risk Profile
Different risk profiles can change provider suitability.
563. Scenario Libraries Should Be Segmented by Journey Stage
A useful sequence is:
Discovery → Education → Comparison → Selection → Application
564. Financial GEO Measurement Should Be Longitudinal
One isolated test is rarely sufficient.
565. Longitudinal Monitoring Can Reveal Stability
A useful concept is:
Presence Frequency + Representation Consistency + Recommendation Consistency
566. Presence Frequency Measures How Often the Provider Appears
This should be assessed within relevant scenarios.
567. Representation Consistency Measures Whether the Provider Is Described Reliably
Repeated factual variation can indicate information instability.
568. Recommendation Consistency Measures Whether Similar Scenarios Produce Similar Fit Assessments
Large variation may indicate weak recommendation confidence.
569. Stability Should Not Be Confused with Accuracy
A consistently wrong answer remains a problem.
570. Financial GEO Monitoring Should Therefore Track Both Stability and Accuracy
A useful matrix includes:
- Stable and accurate
- Stable and inaccurate
- Unstable and accurate
- Unstable and inaccurate
571. Stable and Accurate Is the Strongest Outcome
The provider is represented reliably and correctly.
572. Stable and Inaccurate Is a High-Priority Risk
Persistent misinformation may influence many customer decisions.
573. Unstable but Accurate Requires Monitoring
Representation may be correct but inconsistent.
574. Unstable and Inaccurate Requires Immediate Investigation
This indicates both factual and consistency weakness.
575. Financial GEO Should Maintain an Error Taxonomy
A structured error taxonomy can speed diagnosis.
576. Entity Errors Can Include
- Wrong legal entity
- Wrong brand relationship
- Wrong parent organisation
- Wrong jurisdiction
577. Product Errors Can Include
- Wrong product
- Wrong feature
- Wrong availability
- Wrong eligibility
578. Regulatory Errors Can Include
- Wrong regulator
- Wrong licence status
- Wrong authorised entity
- Wrong market
579. Commercial Errors Can Include
- Wrong rate
- Wrong fee
- Wrong promotion
- Wrong contract term
580. Recommendation Errors Can Include
- Irrelevant inclusion
- Relevant exclusion
- Wrong customer fit
- Wrong comparative reason
581. Error Taxonomies Support Root-Cause Analysis
Different error types often require different corrective actions.
582. Financial GEO Should Diagnose the Likely Source of Error
A useful process is:
Observe → Classify → Compare → Diagnose → Prioritise → Improve → Re-Test
583. Observe
Record the generated financial representation.
584. Classify
Identify whether the issue concerns:
- Entity
- Product
- Regulation
- Commercial information
- Recommendation
585. Compare
Compare the output against authoritative sources.
586. Diagnose
Identify likely information, evidence or authority gaps.
587. Prioritise
Use risk and customer impact.
588. Improve
Strengthen the underlying source environment.
589. Re-Test
Determine whether the observed pattern changes.
590. Financial GEO Should Track Source Support
For each important generated claim, the organisation can ask:
What public evidence supports this representation?
591. Strong Source Support Can Include
- Current product pages
- Regulatory records
- Independent comparisons
- Research
- Professional references
592. Weak Source Support Can Explain Inaccuracy
Where authoritative evidence is absent, outdated or contradictory, generated representation may become less reliable.
593. Source Support Should Be Measured by Type
Useful categories can include:
- First-party
- Regulatory
- Independent commercial
- Research
- Professional
594. Financial GEO Should Track Citation Share Separately from Comparison Share
A provider may be cited frequently without appearing in provider comparisons.
595. Comparison Share Should Be Tracked Separately from Recommendation Share
A provider may enter the consideration set without becoming a recommended option.
596. Keeping These Measures Separate Improves Diagnosis
For example:
- Strong citations + weak comparison may indicate product positioning weakness
- Strong comparison + weak recommendation may indicate fit or trust weakness
- Strong recommendation + weak citation may indicate reliance on external sources
597. Financial GEO Should Monitor Competitive Movement
Provider sets can change over time.
598. Competitive Movement Can Include
- New provider emergence
- Provider decline
- Category convergence
- Positioning changes
599. Provider Co-Occurrence Should Be Recorded
Repeated co-occurrence can reveal effective competitors.
600. Provider Co-Occurrence Can Be Measured by Scenario Type
For example:
- SME banking
- Consumer lending
- Merchant acquiring
- Investment platforms
601. Financial GEO Should Track Strength Attribution
The organisation should record which strengths are repeatedly associated with each provider.
602. Financial GEO Should Track Weakness Attribution
Repeated negative framing can materially affect comparison and recommendation.
603. Strength and Weakness Attribution Can Inform Positioning
It can show whether public perception aligns with strategic intent.
604. Financial GEO Measurement Should Connect to Traditional SEO Data
Useful data can include:
- Search visibility
- Organic traffic
- Ranking movement
- Click-through rate
- Landing-page engagement
605. SEO Data and GEO Data Should Not Be Combined Carelessly
They measure different parts of the discovery environment.
606. Financial GEO Measurement Should Connect to Customer Data
Relevant signals can include:
- Qualified enquiries
- Applications
- Approval rates
- Conversions
- Customer retention
607. Financial GEO Measurement Should Connect to Product Data
Relevant measures can include:
- Product demand
- Eligibility failure
- Application abandonment
- Customer objections
608. Financial GEO Measurement Should Connect to Compliance Data
Relevant information can include:
- Regulatory issues
- Disclosure updates
- Complaint patterns
- High-risk information changes
609. Attribution Should Remain Cautious
AI-assisted discovery can influence customer decisions without producing a visible referral.
610. Financial GEO Should therefore Use Multiple Attribution Signals
These can include:
- Customer surveys
- CRM notes
- Application questionnaires
- Search data
- AI visibility observations
611. Leading Indicators Can Support Financial GEO Measurement
Leading indicators can reveal authority development before customer outcomes change.
612. Financial GEO Leading Indicators Can Include
- Source visibility
- Citation share
- Entity accuracy
- Comparison share
- Recommendation share
613. Lagging Indicators Can Include
- Qualified applications
- Customer acquisition
- Approval quality
- Customer retention
- Product fit
614. Leading and Lagging Indicators Should Be Interpreted Together
Visibility improvement without customer fit may not represent strong performance.
615. Financial GEO Should Include an Executive Scorecard
A practical scorecard can include:
- Source Visibility
- Citation Share
- Entity & Product Accuracy
- Comparison Share
- Recommendation Share
- Critical GEO Risk
616. Executive Scorecards Should Show Direction
Each measure can be classified as:
- Improving
- Stable
- At risk
- Deteriorating
617. Executive Scorecards Should Highlight the Primary Constraint
The most important question is:
Which GEO weakness is currently limiting qualified financial discovery?
618. The Primary Constraint May Be Source Visibility
The provider may lack sufficiently authoritative source presence.
619. The Primary Constraint May Be Citation Authority
The provider may be visible but not trusted as a reference.
620. The Primary Constraint May Be Product Accuracy
The provider may be represented incorrectly.
621. The Primary Constraint May Be Comparison Visibility
The provider may not enter relevant consideration sets.
622. The Primary Constraint May Be Recommendation Fit
The provider may be compared but not recommended appropriately.
623. Financial GEO Reporting Should Avoid Vanity Metrics
Raw mention counts alone can be misleading.
624. High Mention Volume Can Coexist with Poor Performance
For example:
- Wrong product representation
- Irrelevant inclusion
- Negative citation context
- Weak customer fit
625. Qualified Financial GEO Performance Is therefore a Better Objective
A useful relationship is:
Relevant Customer Scenario + Accurate Provider Representation + Strong Trust Evidence + Appropriate Recommendation
626. Financial GEO Measurement Should Be Repeatable
The same core methodology should be usable across reporting periods.
627. Repeatability Requires Consistent Scenario Design
Major changes to the scenario set can make longitudinal comparison difficult.
628. Scenario Libraries Should Still Evolve
New customer behaviour, products and markets may require new scenarios.
629. The Best Approach Is Controlled Evolution
Core benchmark scenarios can remain stable while new scenarios are added separately.
630. Financial GEO Should Document Measurement Changes
Changes to:
- Scenario design
- AI platforms
- Scoring methods
- Risk weighting
should be recorded.
631. Measurement Transparency Improves Interpretation
Stakeholders can understand why results may change.
632. Financial GEO Measurement Should Be Decision-Oriented
The goal is not simply to collect data.
633. Each Measure Should Connect to a Potential Action
For example:
- Weak source visibility → strengthen source assets
- Weak citation share → improve citation authority
- Accuracy problems → improve fact governance
- Weak comparison share → improve product and authority positioning
- Weak recommendation share → investigate customer fit and trust
634. The Seventeenth Financial GEO Principle
Financial GEO measurement should separate source visibility, citation visibility, entity and product accuracy, comparison visibility and recommendation visibility because each represents a different stage of financial discovery and requires different diagnostic and improvement actions.
635. The Eighteenth Financial GEO Principle
Financial GEO accuracy should be risk-weighted, with regulatory status, product availability, eligibility, pricing and other high-impact financial facts prioritised according to severity, persistence, customer impact and regulatory importance.
636. The Nineteenth Financial GEO Principle
Financial GEO monitoring should be longitudinal and scenario-based, using stable benchmark scenarios segmented by product, customer type, geography, risk profile and journey stage so durable visibility patterns can be distinguished from temporary generative variation.
637. The Twentieth Financial GEO Principle
Financial GEO reporting should prioritise qualified performance and strategic constraints rather than raw mention volume, connecting visibility, accuracy, trust and recommendation quality to the customer scenarios and financial outcomes that matter most to the organisation.
638. The Financial GEO Measurement Framework
The complete measurement relationship can be summarised as:
Source Visibility → Citation Visibility → Entity & Product Accuracy → Comparison Visibility → Recommendation Visibility → Qualified Financial GEO Performance
639. The Strategic Implication
Financial services organisations should measure Generative Engine Optimisation through a layered and risk-sensitive framework that distinguishes source presence, citations, factual accuracy, provider comparisons and qualified recommendations, using longitudinal scenario libraries and executive scorecards to identify where the financial information, trust or authority system is currently constraining appropriate customer discovery.
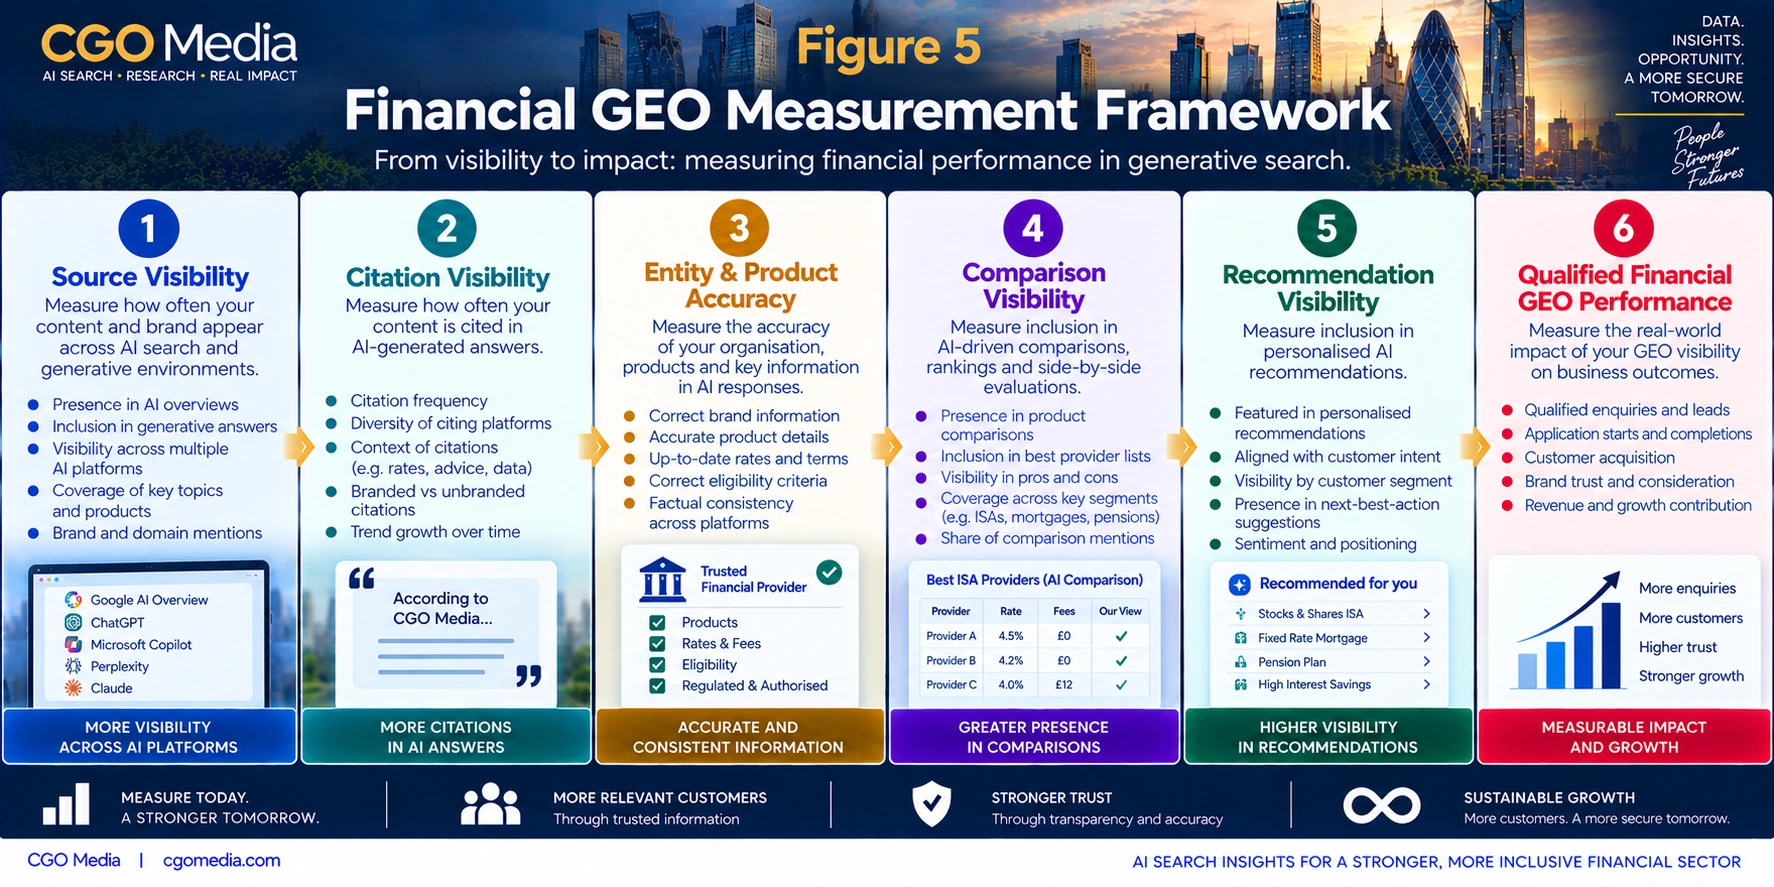
640. Financial GEO Should Operate as a Continuous Improvement System
Financial Generative Engine Optimisation should not be treated as a one-time visibility project.
641. Financial Information Changes Continuously
Providers should expect change across:
- Products
- Rates
- Fees
- Eligibility
- Regulation
- Customer behaviour
642. Continuous Financial GEO Should Begin with Observation
Teams should repeatedly observe:
- Source visibility
- Citation visibility
- Entity accuracy
- Product accuracy
- Recommendation fit
643. Observation Should Be Structured
Scenario libraries and recording methods should remain sufficiently consistent to support meaningful longitudinal comparison.
644. Continuous GEO Should Diagnose Change
A material visibility shift should trigger investigation rather than immediate tactical reaction.
645. Diagnosis Should Distinguish Noise from Structural Change
One unusual generative output may represent temporary variation.
646. Persistent Change Can Indicate a Structural Financial GEO Problem
Examples can include:
- Product ambiguity
- Regulatory inconsistency
- Trust-evidence decay
- Competitive displacement
- Category drift
647. Continuous GEO Should Prioritise by Customer Impact
Not every visibility change has equal commercial or regulatory significance.
648. A Financial GEO Priority Model Can Use
Customer Impact + Commercial Importance + Persistence + Regulatory Risk
649. Customer Impact
Measures whether the issue can affect:
- Discovery
- Comparison
- Application
- Product selection
650. Commercial Importance
Measures whether the issue affects strategic:
- Products
- Markets
- Customer segments
- Revenue
651. Persistence
Measures whether the issue repeats across time and customer scenarios.
652. Regulatory Risk
Measures the consequence of leaving the problem unresolved.
653. Continuous GEO Should Improve the Underlying Financial Information System
The intervention may involve:
- Product content
- Regulatory information
- Trust evidence
- Research
- External authority
654. GEO Improvement Should Target Root Causes
The organisation should avoid trying to manipulate individual outputs directly.
655. Root Causes Can Exist in Owned Information
Examples include:
- Outdated product pages
- Missing eligibility information
- Weak regulatory evidence
- Ambiguous product relationships
656. Root Causes Can Exist in External Information
Examples include:
- Old comparison pages
- Outdated directories
- Incorrect third-party product descriptions
- Weak independent authority
657. Financial GEO Improvement Should Be Followed by Re-Testing
The organisation should determine whether the intervention changed the observed discovery pattern.
658. Re-Testing Should Preserve Scenario Consistency
Otherwise comparison becomes difficult.
659. Continuous Financial GEO Can Be Summarised as
Observe → Diagnose → Prioritise → Strengthen → Validate → Learn → Adapt
660. Governance Is Essential to Financial GEO
Financial GEO crosses multiple organisational functions.
661. A Financial GEO Governance Model Can Include
SEO + Product + Compliance + Legal + Marketing + Research + Customer Insight
662. SEO Can Coordinate Visibility Monitoring
SEO can connect:
- Search demand
- AI visibility
- Information architecture
- Source analysis
663. Product Teams Can Validate Product Truth
They can confirm:
- Features
- Rates
- Fees
- Eligibility
- Availability
664. Compliance Can Validate Regulatory Truth
Compliance teams can confirm:
- Authorisation
- Regulatory status
- Jurisdiction
- Required disclosures
665. Legal Can Support High-Risk Claims
Legal review can be particularly important where product, risk or regulatory language has material implications.
666. Marketing Can Improve Information Clarity
Marketing can strengthen:
- Product explanations
- Customer comparison content
- Research distribution
- External communications
667. Research Teams Can Strengthen Citation Authority
Research can create:
- Market studies
- Customer surveys
- Financial statistics
- Industry benchmarks
668. Customer Insight Can Validate Real Decision Behaviour
It can contribute:
- Customer objections
- Common questions
- Application barriers
- Decision criteria
669. Financial GEO Governance Should Include Ownership
The organisation should know who owns:
- Monitoring
- Product accuracy
- Regulatory accuracy
- Trust evidence
- Escalation
670. GEO Governance Should Include Review Cadence
Different information types require different review frequencies.
671. High-Risk Financial Information May Require Frequent Review
Examples include:
- Rates
- Fees
- Eligibility
- Product availability
- Regulatory status
672. Review Frequency Should Reflect Risk and Volatility
A useful principle is:
Rate of Change + Customer Impact + Regulatory Risk → Review Frequency
673. GEO Governance Should Include Escalation
Critical financial misinformation should not remain within ordinary reporting queues.
674. Critical Financial GEO Escalation Can Involve
- Compliance
- Legal
- Product
- Marketing
- Leadership
675. Financial GEO Should Include Recovery Capability
Not every misinformation event can be prevented.
676. A Financial GEO Recovery Cycle Can Be Used
Detect → Verify → Diagnose → Correct → Re-Test → Learn
677. Detect
Identifies material product, regulatory, pricing or provider-representation errors.
678. Verify
Confirms whether the observation is genuine and persistent.
679. Diagnose
Identifies the likely source, trust, product or regulatory problem.
680. Correct
Improves the underlying information environment.
681. Re-Test
Checks whether the observed pattern changes.
682. Learn
Improves future monitoring, governance and content standards.
683. Recovery Speed Can Be Measured
Useful measures can include:
- Time to detect
- Time to verify
- Time to correct
- Time to validate
684. Financial GEO Should Also Include Experimentation
Some interventions should be tested rather than assumed to work.
685. Financial GEO Experiments Should Begin with a Hypothesis
For example:
Publishing clearer product eligibility, current pricing, regulatory evidence and comparison guidance should improve qualified recommendation visibility for relevant SME banking scenarios.
686. Experiments Should Establish a Baseline
The organisation should record the starting visibility position.
687. Experiments Should Define the Intervention
Examples can include:
- New product pages
- Updated eligibility guidance
- Improved regulatory evidence
- Original financial research
688. Experiments Should Define Success Criteria
Success can include:
- Improved source visibility
- Improved citation visibility
- Improved product accuracy
- Improved recommendation fit
689. Experiments Should Have Observation Windows
Generative visibility may not change immediately after an intervention.
690. Confounding Factors Should Be Recorded
Examples can include:
- AI model changes
- Product launches
- Competitor activity
- Regulatory changes
691. Negative Results Should Be Preserved
They help prevent repeated ineffective work.
692. Successful Experiments Should Become Standards
Validated approaches can be added to:
- Product templates
- Regulatory standards
- Evidence standards
- Monitoring playbooks
693. Financial GEO Should Integrate with Traditional SEO
The two disciplines overlap substantially.
694. SEO Supports GEO Through Technical Accessibility
Search engines and generative systems both benefit from accessible, well-structured financial information.
695. SEO Supports GEO Through Information Architecture
Clear relationships between:
- Providers
- Products
- Customer segments
- Markets
- Regulated entities
can improve understanding.
696. SEO Supports GEO Through Topical Coverage
Strong financial content ecosystems can strengthen category relevance.
697. GEO Extends SEO Through Representation and Recommendation Analysis
Financial GEO adds explicit focus on:
- Citation
- Product accuracy
- Comparison
- Provider recommendation
698. SEO and GEO Should Share Infrastructure
But they should not be treated as identical disciplines.
699. Financial GEO Should Integrate with Digital PR
External financial authority is central to the public trust and source environment.
700. Digital PR Can Strengthen Financial GEO Through
- Research coverage
- Expert commentary
- Financial statistics
- Industry references
701. Financial GEO Should Integrate with Research Strategy
Original financial research can create high-value citation assets.
702. Research Can Support GEO Through
- Customer data
- Market studies
- Payment trends
- Search-behaviour studies
703. Financial GEO Should Integrate with Customer Evidence
Successful customer outcomes provide real-world validation.
704. Customer Evidence Can Improve
- Product trust
- Use-case authority
- Recommendation confidence
- External credibility
705. Financial GEO Should Integrate with Product Strategy
Generated representation can expose gaps between how an organisation intends to position products and how they are understood externally.
706. Persistent Product Misunderstanding Can Be a Positioning Signal
The problem may not always be content alone.
707. GEO Intelligence Can Reveal Category Drift
A provider may increasingly be associated with products or customer segments it no longer prioritises.
708. Category Drift Can Be Strategic or Problematic
It should be assessed against current product and growth strategy.
709. GEO Intelligence Can Reveal Emerging Competitors
Repeated provider co-occurrence can identify new competitive relationships.
710. GEO Intelligence Can Reveal New Customer Language
AI prompts may expose terminology different from internal product language.
711. Financial GEO Can Therefore Contribute to Market Intelligence
Its value extends beyond marketing visibility.
712. Financial GEO Should Be Scaled Carefully
Large scenario libraries can create noise without strategic value.
713. Scaling Should Follow Strategic Priority
Scenario expansion can follow:
- New products
- New customer segments
- New markets
- New regulatory environments
714. Financial GEO Scaling Should Include International Markets
Provider recommendation can vary significantly by geography.
715. International GEO Should Reflect Local Financial Context
Direct translation of prompts may not capture local product, regulatory or customer behaviour.
716. Local Financial Source Ecosystems Can Differ
Different countries may have different:
- Regulators
- Government bodies
- Comparison platforms
- Professional organisations
- Financial media
717. International Financial GEO Should Preserve Entity Consistency
Group, brand, legal entity and product relationships should remain coherent across markets.
718. Localisation Should Preserve Product Truth
Core financial facts should remain consistent where the underlying product is the same.
719. Localisation Should Adapt Regulatory and Commercial Evidence
Different markets may require different:
- Licence information
- Eligibility
- Pricing
- Risk disclosures
- Customer protection
720. Financial GEO Scaling Should Include Business Units and Product Portfolios
Large financial groups may need product-level and market-level monitoring.
721. Product-Level GEO Can Reveal Internal Portfolio Confusion
AI systems may:
- Merge products
- Misstate availability
- Confuse customer segments
- Misattribute regulated entities
722. Product-Level Entity Governance Is Therefore Important
Each major financial product should have clear public information.
723. GEO Scaling Should Include Customer Segments
Large providers may need separate monitoring for:
- Consumers
- SMEs
- Enterprise clients
- Institutional customers
724. Segment-Level GEO Can Reveal Customer-Fit Confusion
Generative systems may recommend products to unsuitable audiences.
725. Financial GEO Scaling Should Include Institutional Learning
Repeated observations should improve:
- Standards
- Training
- Research
- Governance
726. Organisational Memory Reduces Repeated GEO Failure
The organisation should not repeatedly rediscover the same product, regulatory or trust problems.
727. Financial GEO Learning Can Be Preserved Through
- Scenario libraries
- Issue logs
- Experiment records
- Product maps
- Source maps
- Playbooks
728. Adaptive Financial GEO Is the Long-Term Goal
The organisation should be able to respond as:
- AI systems change
- Products change
- Markets change
- Regulation changes
- Customer behaviour changes
729. Adaptive GEO Does Not Mean Constant Tactical Reaction
Stable principles should remain.
730. Stable Financial GEO Principles Can Include
- Clear entities
- Clear product information
- Current regulatory evidence
- Strong trust evidence
- Relevant external authority
- Customer fit
731. Tactics Can Change Around Stable Principles
This creates resilience without strategic confusion.
732. Adaptive Financial GEO Should Be Evidence-Led
Changes should respond to observed customer-visibility patterns rather than speculation.
733. Adaptive Financial GEO Should Be Risk-Aware
Critical regulatory, pricing, product or eligibility misinformation should receive priority over low-value mention changes.
734. Adaptive Financial GEO Should Be Strategically Relevant
The programme should focus on customer scenarios that matter to the organisation.
735. Adaptive Financial GEO Should Be Integrated
It should connect:
Search Intelligence + AI Intelligence + Product Intelligence + Compliance Intelligence + Customer Evidence + Research Intelligence
736. Combined Intelligence Improves GEO Decisions
Teams can better determine:
- What to improve
- What to monitor
- What to research
- What to communicate
737. Strategic Recommendation One — Build a Defined Customer Scenario Library
Focus monitoring on realistic financial decisions and commercially relevant customer questions.
738. Strategic Recommendation Two — Map Financial Source Visibility
Identify which owned and external sources appear around priority products and customer scenarios.
739. Strategic Recommendation Three — Strengthen Financial Citation Assets
Create useful:
- Research
- Financial statistics
- Definitions
- Market studies
- Frameworks
740. Strategic Recommendation Four — Improve Entity and Product Clarity
Reduce ambiguity around groups, brands, regulated entities, products and customer segments.
741. Strategic Recommendation Five — Improve Eligibility Clarity
Make application requirements, customer criteria and product limitations explicit.
742. Strategic Recommendation Six — Strengthen Regulatory and Trust Evidence
Maintain clear and current regulatory, security, customer-protection and independent evidence.
743. Strategic Recommendation Seven — Strengthen Source Convergence
Ensure critical product and provider information materially agrees across public sources.
744. Strategic Recommendation Eight — Monitor Provider Recommendation Fit
Track whether inclusion is appropriate to customer context.
745. Strategic Recommendation Nine — Monitor Exclusion Quality
Investigate repeated omission where provider fit is genuine.
746. Strategic Recommendation Ten — Track Critical Financial Misinformation
Escalate high-risk regulatory, pricing, eligibility and product errors quickly.
747. Strategic Recommendation Eleven — Build GEO Recovery Processes
Create clear detection, diagnosis, correction and re-testing procedures.
748. Strategic Recommendation Twelve — Integrate GEO with Financial Research and Digital PR
Build external authority around useful financial evidence.
749. Strategic Recommendation Thirteen — Connect GEO to Product Intelligence
Use real customer questions and product data to improve scenario design.
750. Strategic Recommendation Fourteen — Connect GEO to Customer Outcomes
Use successful customer outcomes to strengthen future recommendation confidence.
751. Strategic Recommendation Fifteen — Expand International GEO Carefully
Use market-specific customer scenarios, regulation, products and source ecosystems.
752. Strategic Recommendation Sixteen — Experiment Systematically
Test interventions using baselines and defined success criteria.
753. Strategic Recommendation Seventeen — Preserve Organisational Learning
Convert repeated findings into standards, training and playbooks.
754. Strategic Recommendation Eighteen — Build Adaptive Financial GEO
Treat Generative Engine Optimisation as a permanent financial-discovery capability rather than a short-term marketing campaign.
755. The Twenty-First Financial GEO Principle
Financial GEO should operate as a continuous improvement system because product information, regulation, fees, eligibility, competitive sets, citations and AI recommendation patterns can all change over time.
756. The Twenty-Second Financial GEO Principle
Financial GEO governance should connect SEO, product, compliance, legal, marketing, research and customer insight so generated provider representation is grounded in current product truth, reliable regulatory evidence and real customer needs.
757. The Twenty-Third Financial GEO Principle
Financial organisations should build recovery and experimentation capability so recurring product errors, regulatory misinformation, citation weaknesses and recommendation gaps can be diagnosed, corrected, re-tested and converted into organisational learning.
758. The Twenty-Fourth Financial GEO Principle
The highest Financial GEO capability is adaptive GEO, where stable principles around entity clarity, product truth, regulatory evidence, source quality and customer fit are preserved while tactics evolve in response to changing generative search environments.
759. The Continuous Financial GEO Cycle
The complete operational cycle can be summarised as:
Observe → Diagnose → Prioritise → Strengthen → Validate → Learn → Adapt
760. The Long-Term Financial GEO System
The wider relationship can be summarised as:
Clear Entity → Clear Product → Strong Regulatory & Trust Evidence → Source Authority → Citation Visibility → Provider Comparison Visibility → Recommendation Confidence → Qualified Financial GEO Visibility → Organisational Learning
761. The Strategic Implication
Financial services organisations should operate Generative Engine Optimisation as a continuous, cross-functional and evidence-led discipline, repeatedly monitoring how providers, products, regulated entities, sources, comparisons and recommendations are represented, strengthening the underlying financial information and authority system, validating change and adapting as AI discovery environments, markets, regulation and customer expectations evolve.
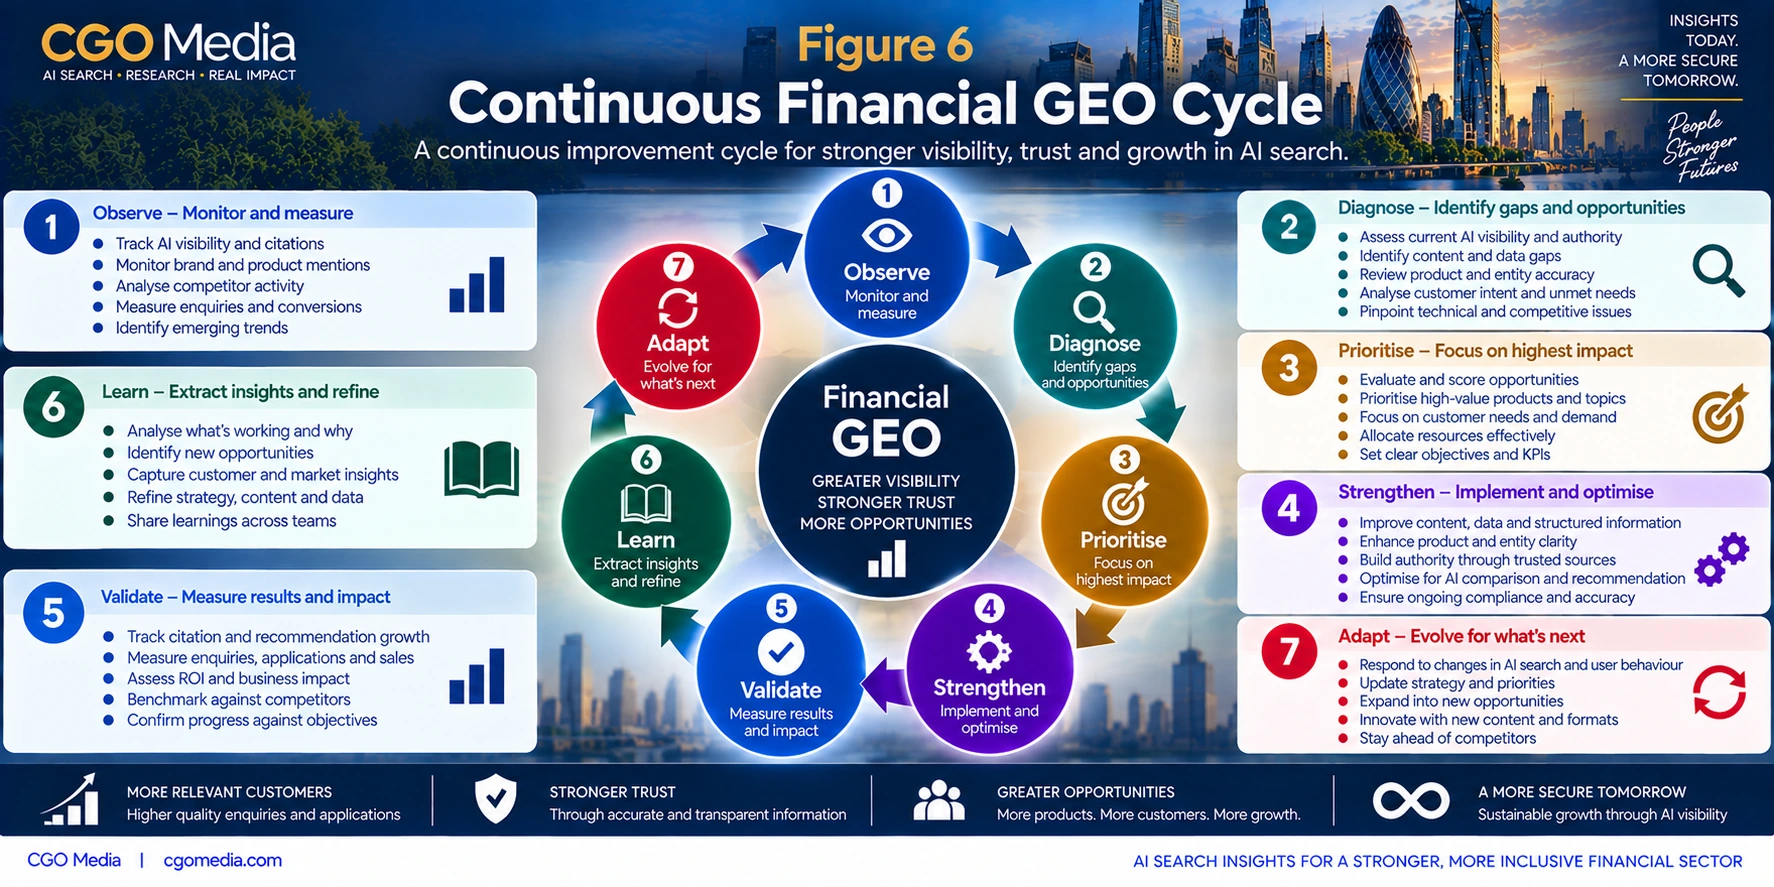
762. Methodology
Financial GEO: Generative Engine Optimisation for AI Search and Financial Provider Recommendation Systems is a conceptual research framework developed by CGO Media to examine how financial organisations, products, institutional evidence and external information are represented within generative search and AI-assisted financial discovery environments.
The framework considers banks, insurers, lenders, investment firms, wealth managers, payment providers, fintech companies, business finance organisations and financial technology vendors.
Its central research question is:
How can financial services organisations improve the quality, authority, trust and customer relevance of their visibility within generative answer, comparison and provider recommendation systems?
The framework treats Financial GEO as an extension of financial information governance, technical SEO, entity management, regulatory clarity and external authority development.
It does not treat GEO as a collection of isolated prompt techniques or claim to reproduce the proprietary processes used by AI systems.
762.1. The Core Financial GEO Framework
The research organises Financial GEO into eight connected dimensions:
- Entity Clarity: Accurate identification of financial organisations, brands, regulated entities and operating jurisdictions.
- Product Clarity: Understandable information about financial products, features, eligibility, costs and restrictions.
- Regulatory and Trust Evidence: Appropriate documentation supporting material institutional and financial claims.
- Source Authority: Relevant, credible information available across provider, official and independent sources.
- Citation Eligibility: The potential usefulness of information as a relevant and supportable reference.
- Customer Fit: Alignment between the user's financial requirement and the provider's actual products and eligibility conditions.
- Recommendation Confidence: A conceptual assessment of whether available evidence supports consideration of a provider for a particular scenario.
- GEO Visibility: Observable representation across AI-generated information, citations, comparisons and provider recommendations.
The conceptual progression is:
Entity Clarity → Product Clarity → Regulatory & Trust Evidence → Source Authority → Citation Eligibility → Customer Fit → Recommendation Confidence → GEO Visibility
This sequence describes relationships within the CGO Media framework. It is not presented as the internal ranking, retrieval or recommendation sequence of any AI provider.
The broader technical and informational foundations are examined in Financial Services SEO in an AI Search Environment.
762.2. Financial Entity Identification and Relationship Mapping
Financial entity analysis examines whether public information accurately identifies the organisation providing a service and the legal or regulatory relationships associated with that service.
Relevant relationships include financial groups, operating entities, trading brands, regulated entities, products and jurisdictions.
The framework uses the following conceptual relationship:
Financial Group → Operating Entity → Brand → Product → Customer Segment → Jurisdiction
For example, a multinational financial group may offer banking, insurance and investment products through separate subsidiaries. A fintech brand may distribute services provided by a regulated partner. A payment technology business may operate alongside a distinct licensed payment institution.
These distinctions can materially affect customer understanding.
Entity information should therefore identify the organisation responsible for the relevant product rather than assuming that brand recognition alone establishes the legal provider.
Relevant website architecture, institutional documentation, regulatory disclosures and appropriate structured data may help communicate these relationships.
The CGO Entity Authority Framework provides additional research context for entity identification, relationships and digital representation.
762.3. Financial Product Clarity and Customer Requirements
Financial products should be described through information relevant to the decisions customers are attempting to make.
The methodology considers:
- Product category and intended purpose.
- Features and service characteristics.
- Customer eligibility.
- Fees and other charges.
- Interest rates or relevant pricing arrangements.
- Contractual restrictions and limitations.
- Material financial risks.
- Geographic availability.
The conceptual customer-product relationship is:
Customer Need → Product Type → Eligibility → Terms → Risk → Provider Fit
A financial provider may offer an appropriate product category while remaining unsuitable for a particular customer because of eligibility, jurisdiction, risk tolerance or commercial conditions.
For example, a business loan may be unavailable to newly incorporated companies. An insurance product may exclude a particular activity. An investment service may have minimum asset requirements or investor eligibility restrictions.
Financial GEO assessment should therefore distinguish general product relevance from genuine customer fit.
This relationship is developed further in the Financial Provider Selection Model.
762.4. Regulatory and Trust Evidence
Financial organisations frequently make claims concerning authorisation, licensing, customer protection, professional competence, security and institutional reliability.
These claims should be supported by evidence appropriate to the specific entity, product and jurisdiction.
The framework uses the relationship:
Financial Claim → Appropriate Evidence → Independent Validation → Customer Confidence
Relevant evidence may include:
- Regulatory authorisation or licensing information.
- Official registration records.
- Applicable customer protection arrangements.
- Relevant security documentation.
- Professional qualifications and responsibilities.
- Independent institutional recognition.
Regulatory information should not be presented as a universal endorsement of every product offered by a financial group.
An organisation may be authorised for particular activities while offering other services through partners or separate entities.
The methodology therefore evaluates whether regulatory claims are connected to the correct organisation, service, market and customer category.
The Financial Services AI Trust Framework examines these trust and verification relationships in greater depth.
762.5. Information Accessibility and Technical Foundations
Financial information must be accessible before it can reliably support conventional search discovery or potential retrieval by systems using web-accessible sources.
The assessment considers crawlability, indexability, internal linking, product-page accessibility and clarity of eligibility information.
Technical accessibility should be evaluated alongside content accuracy.
A highly accessible product page containing outdated charges or incorrect eligibility information may increase the availability of misleading information rather than improve customer understanding.
Similarly, structured data can describe an organisation or service but cannot independently verify regulatory status, product suitability or financial claims.
Financial GEO should therefore build on established technical SEO while maintaining appropriate product and compliance review.
762.6. Financial Source Estate Mapping
The framework considers the wider information environment through which financial organisations and products may be encountered.
Relevant source categories include:
- Official provider websites.
- Financial product pages and documentation.
- Regulatory registers and guidance.
- Comparison platforms.
- Financial and business media.
- Professional publications.
- Independent research and datasets.
These sources may provide different forms of evidence.
Provider documentation can explain current product terms. Official regulatory records can support verification of authorisation. Independent research may provide market context. Comparison platforms can organise selected products according to their own inclusion and evaluation criteria.
No single source category should automatically be treated as sufficient for every financial question.
762.7. Conceptual Financial Source-Selection Method
The research conceptualises source selection through the following sequence:
Customer Context → Candidate Sources → Product Relevance → Regulatory Evidence → Authority → Source Convergence → Source Selection
This model describes considerations that may be useful when evaluating financial evidence.
It does not establish that generative systems apply these stages in the stated order.
Different customer questions may require different source combinations.
Product discovery questions may require product pages, category resources, customer guides and financial explainers.
Eligibility questions may require application guidance, income or turnover criteria, geographic restrictions and product-specific conditions.
Regulatory questions may require official registers, authorisation information and jurisdiction-specific guidance.
Provider comparisons may require current pricing, product features, eligibility conditions and appropriately interpreted independent comparisons.
Financial research questions may require primary studies, published datasets, transparent methodologies and clear research limitations.
The framework therefore treats source relevance as contextual rather than universal.
762.8. Source Convergence and Conflict Analysis
Financial claims may appear across several information environments.
The framework uses the conceptual relationship:
Provider Truth + Regulatory Validation + Independent Comparison + Research Evidence
Convergence occurs when relevant sources support a materially consistent understanding of the organisation or product.
However, agreement between sources does not necessarily establish independent verification. Several websites may reproduce the same original information or outdated description.
The methodology therefore considers source independence, publication dates and the evidence supporting important claims.
Material conflicts may involve:
- Interest rates.
- Transaction or service fees.
- Customer eligibility.
- Regulatory status.
- Product availability.
- Contractual terms.
Where conflicting information is identified, the organisation should investigate the discrepancy and determine which sources require correction or clarification.
Source convergence is treated as an analytical consideration rather than proof of how a particular AI answer was constructed.
762.9. Citation Eligibility and Citation Authority
Financial GEO includes the question of whether published information is sufficiently useful, clear and credible to serve as a potential source in relevant information environments.
The framework conceptualises citation readiness through:
Relevance + Clarity + Evidence + Authority + Freshness
These dimensions may be applied to financial explainers, product documentation, original research and institutional resources.
Citation Authority considers relevant references from financial media, research publications, government bodies, professional organisations and AI-generated answers.
However, citation frequency should not be equated with financial credibility.
A frequently cited source may be outdated, commercially biased or unsuitable for a particular question.
The methodology therefore distinguishes citation volume from citation relevance and supporting evidence.
The CGO AI Citation Framework provides additional research context for citation assessment and observable source references.
762.10. Original Financial Research as a Citation Resource
Financial organisations may publish original research that contributes useful information to their wider markets.
Potential research assets include:
- Financial market studies.
- Customer research.
- Financial datasets.
- Payment industry studies.
- Search-behaviour research.
- Original analytical frameworks.
Research should clearly explain its question, sample, market scope, geographic coverage, measurement period, definitions and limitations.
For example, a payment provider publishing transaction trends should explain the population represented by its data and avoid implying that its customer base necessarily reflects the entire market.
An insurer publishing customer research should distinguish survey findings from verified claims about all insurance customers.
Original research can create useful reference material, but publication alone does not guarantee independent citation or AI inclusion.
762.11. Financial Provider Recommendation Method
The framework conceptualises provider recommendation through:
Customer Scenario → Product Fit → Eligibility Fit → Regulatory & Trust Evidence → Commercial Fit → External Validation → Recommendation Confidence → Qualified Provider Recommendation
The sequence separates several questions that are often combined in general financial comparisons.
Product fit concerns whether the financial product addresses the customer's requirement, including relevant features, risks and service characteristics.
Eligibility fit concerns whether the customer may qualify under relevant conditions such as residence, income, turnover, credit profile, age or business type.
Commercial fit concerns rates, fees, contract terms, minimum balances and the service model.
Regulatory and trust evidence concerns the appropriate verification of institutional claims.
External validation concerns relevant independent information, interpreted according to its actual evidential value.
The framework defines Recommendation Confidence conceptually through:
Customer Relevance + Product Fit + Eligibility Fit + Regulatory Confidence + Trust Evidence + Commercial Fit + External Validation
Recommendation Confidence is a CGO Media analytical construct, not a published confidence score assigned by AI providers.
Financial suitability may also require information that cannot be determined from a general search question.
Accordingly, an AI-generated provider suggestion should not be treated as personalised financial advice or a definitive suitability assessment.
762.12. Five-Layer Financial GEO Measurement
The framework distinguishes five observable dimensions of financial visibility:
- Source Visibility.
- Citation Visibility.
- Entity & Product Accuracy.
- Comparison Visibility.
- Recommendation Visibility.
Source Visibility examines observable indications that financial information is present or used within an AI-assisted answer. Where source use cannot be established, observations should be labelled accordingly.
Citation Visibility records explicit references to provider, product or research sources.
Entity & Product Accuracy evaluates whether organisations, regulated entities, products, rates, eligibility conditions and jurisdictions are described correctly.
Comparison Visibility examines whether a provider appears within relevant financial comparison sets.
Recommendation Visibility examines whether the provider is suggested within a customer scenario and whether that suggestion appears contextually appropriate.
These dimensions should be measured separately.
A financial provider may receive citations without appearing in recommendations. It may appear in comparisons while being described inaccurately. It may be mentioned frequently despite being unsuitable for the stated customer scenario.
The framework therefore defines qualified Financial GEO performance through:
Relevant Customer Presence + Accurate Provider Representation + Strong Trust Evidence + Appropriate Recommendation
The objective is meaningful representation rather than maximum mention volume.
762.13. Customer Scenario Libraries
Financial GEO monitoring should use realistic customer scenarios rather than relying exclusively on broad prompts containing provider or category names.
Scenario libraries may be segmented by:
- Financial product.
- Customer type.
- Geographic market.
- Relevant risk profile.
- Customer journey stage.
- Financial objective.
For example, a payment provider might test scenarios involving a small retailer, an online merchant and a multinational business with different transaction requirements.
A lender might examine consumer borrowing, commercial finance and refinancing scenarios separately.
An insurer might distinguish personal, commercial and specialist insurance requirements.
Scenarios should identify the assumptions needed to interpret results and avoid presenting incomplete customer information as sufficient for personalised recommendations.
762.14. Longitudinal Observation and Trend Analysis
Repeated monitoring can help identify patterns that are not apparent in a single AI-generated answer.
The original framework identifies:
- Persistent provider inclusion.
- Persistent provider exclusion.
- Recurring product misinformation.
- Provider co-occurrence.
- Competitive displacement.
Observations should record the system, date, language, market, prompt and relevant response context.
Where possible, repeated tests should use consistent scenario definitions while documenting material changes in the testing environment.
Longitudinal analysis can reveal observable trends, but it does not establish the proprietary mechanisms responsible for them.
762.15. Financial GEO Risk Prioritisation
The framework prioritises material representation errors through:
Severity + Persistence + Customer Impact + Regulatory Importance
Important errors may include incorrect regulatory status, eligibility conditions, interest rates, fees or product availability.
A minor wording difference should not necessarily receive the same priority as a recurring statement that a financial provider is authorised for an activity it does not perform.
Likewise, inaccurate insurance exclusions or borrowing costs may materially affect customer understanding.
Risk assessment should consider both the nature of the error and the circumstances in which users may encounter it.
Material issues should be escalated through appropriate product, compliance or legal review where necessary.
762.16. Continuous Improvement and Error Recovery
The Financial GEO operating cycle is:
Observe → Diagnose → Prioritise → Strengthen → Validate → Learn → Adapt
For material representation errors, the framework proposes:
Detect → Verify → Diagnose → Correct → Re-Test → Learn
These processes should begin by establishing whether the observed information is genuinely incorrect.
Where an error is confirmed, the organisation should examine relevant owned information and identify any appropriate correction opportunities.
Changes should then be monitored over a reasonable period.
However, organisations cannot assume that correcting a webpage will immediately alter AI-generated responses or remove information held by independent third parties.
762.17. Financial GEO Experimentation
Structured experimentation can help financial organisations evaluate whether particular information improvements correspond with observable changes.
The framework recommends documenting:
- Hypothesis.
- Baseline.
- Intervention.
- Observation period.
- Success criteria.
- Result.
For example, a financial organisation may clarify product eligibility information and subsequently monitor whether recurring eligibility errors become less frequent.
Such observations may support operational learning.
They should not be presented as proof of causation where changes in AI systems, source availability or other external factors cannot be excluded.
762.18. Cross-Functional Financial GEO Governance
Financial GEO requires coordination across functions responsible for different aspects of institutional and product information.
The original framework identifies:
SEO + Product + Compliance + Legal + Marketing + Research + Customer Insight
These functions may contribute technical expertise, current product information, regulatory review, institutional communication, original evidence and customer understanding.
Responsibilities should be proportionate to organisational size and regulatory complexity.
The Financial SEO & AI Implementation Roadmap provides a companion structure for translating these research principles into operational priorities.
762.19. International and Multi-Market Financial GEO
Financial organisations operating across several markets should preserve accurate institutional information while accounting for local differences.
Relevant considerations include:
- Customer language.
- Applicable regulation.
- Product availability.
- Eligibility requirements.
- Local source environments.
- Market-specific pricing.
- Customer behaviour.
A product available in one jurisdiction should not be represented as universally available.
Similarly, a regulatory authorisation applying to one entity or territory should not be extended inaccurately to another.
Large financial organisations may therefore require separate analysis by product category, product variant, customer segment, market and regulated entity.
The objective is coherent provider information combined with accurate local representation.
762.20. Financial GEO Maturity and Organisational Development
Financial GEO capability is unlikely to develop uniformly across every function or product.
An organisation may maintain strong technical foundations but have weak entity documentation. Another may publish valuable research while lacking systematic monitoring of AI-generated product information.
Capability assessment should therefore distinguish isolated strengths from coordinated organisational processes.
The Financial Search Authority Maturity Model examines the development of more integrated financial search and authority capabilities.
The CGO AI Search Readiness Framework provides additional context for assessing organisational preparedness for AI-assisted discovery.
763. Strategic Implications
The Financial GEO framework suggests that financial organisations should treat generative discovery as a continuing information and governance challenge rather than a short-term channel for increasing AI mentions.
Financial customers may use AI-assisted systems to investigate products, identify providers, compare costs, understand eligibility and explore institutional credibility.
These activities create opportunities for relevant discovery but also introduce risks where complex financial information is simplified or represented incorrectly.
763.1. Financial GEO Extends Rather Than Replaces SEO
Traditional SEO remains important for making financial information accessible through search engines.
Generative discovery adds questions about source references, entity interpretation, product accuracy, comparison inclusion and recommendation context.
Financial organisations should therefore maintain established SEO capabilities while developing appropriate monitoring and information governance for AI-assisted environments.
The relationship between these disciplines is examined in Financial Services SEO in an AI Search Environment.
763.2. Provider Identity Must Be Consistent and Verifiable
Financial brands may operate through several legal entities or regulated partners.
Inconsistent descriptions can create confusion about who provides a product, which permissions apply and where services are available.
Organisations should maintain accurate institutional relationships across relevant owned information and investigate material external discrepancies.
763.3. Product Information Is a Critical GEO Resource
Financial product pages should communicate the information needed for appropriate evaluation.
Rates, fees, eligibility, exclusions, contractual conditions and relevant risks should be understandable and current.
Greater information accessibility is not inherently beneficial where material product details are inaccurate.
763.4. Regulatory Trust Requires Specific Evidence
Claims about authorisation, licensing and customer protection should be connected to the correct entity and jurisdiction.
Regulatory status should not be used as a general marketing assertion detached from the activities to which it applies.
Verification and compliance responsibilities remain with the relevant organisation and competent professionals.
763.5. Source Authority Depends on Relevance and Reliability
Financial providers may be described by regulators, comparison services, professional bodies, media and independent researchers.
These sources contribute different forms of evidence.
Financial GEO strategies should prioritise accurate information and credible external relationships rather than treating every mention or link as equivalent.
763.6. Citation Visibility and Recommendation Visibility Are Different
An AI-generated answer may cite a financial organisation without recommending its products.
A provider may also appear in a comparison without being suitable for the user's circumstances.
Measurement should distinguish these outcomes to avoid overstating commercial or reputational significance.
763.7. Customer Fit Should Guide Recommendation Analysis
Financial recommendations are meaningful only within the relevant customer context.
A provider may be appropriate for one customer segment and unsuitable for another because of eligibility, pricing, risk or jurisdiction.
The Financial Provider Selection Model provides a companion structure for examining the wider customer decision process.
763.8. AI Monitoring Should Prioritise Material Accuracy
Monitoring programmes should examine whether generated answers contain material errors concerning financial products or regulated identities.
Recurring inaccuracies may warrant investigation even when overall mention volume is high.
Accuracy and contextual relevance should therefore be reported alongside visibility.
763.9. Original Research Can Support Financial Source Utility
Transparent, well-documented research can provide useful evidence for financial audiences, journalists and analysts.
However, publication should not be equated with guaranteed citation or AI recommendation.
Research quality, methodological transparency and relevance remain important considerations.
763.10. Digital PR Should Reinforce Genuine Evidence
Relevant financial media coverage and independent references may strengthen the information available about a provider.
Digital PR should focus on useful research, accurate institutional information and legitimate expertise.
It should not rely on unsupported claims about AI ranking benefits or artificial citation creation.
763.11. International GEO Requires Local Accuracy
Financial organisations operating internationally should ensure that product information, eligibility and regulatory descriptions correspond to the relevant market.
Consistent branding should not obscure material differences between jurisdictions.
763.12. Governance Is Essential for Sustainable Financial GEO
Products, regulations, customer expectations and AI systems change over time.
Financial GEO therefore requires continuing review, defined ownership, appropriate escalation and repeated observation.
The long-term capability is not control over generative systems, but a reliable process for maintaining and improving financial information across a changing discovery environment.
764. Framework Limitations
Financial GEO: Generative Engine Optimisation for AI Search and Financial Provider Recommendation Systems is a conceptual research framework. It does not reproduce or disclose the proprietary retrieval, ranking, source-selection or recommendation systems used by AI providers.
The framework is not a regulatory audit, compliance certification, legal opinion, investment recommendation or substitute for professional financial advice.
764.1. Generative Systems Are Only Partially Observable
External researchers cannot observe every internal retrieval, ranking, source-selection or recommendation process.
764.2. Source Influence May Be Difficult to Verify
AI systems may not disclose every source contributing to a generated answer.
764.3. Citation Visibility Varies Between Platforms
Different systems provide different levels of source attribution and citation detail.
764.4. AI Outputs Can Vary
Responses may differ according to model, prompt, conversation context, date, language and market.
764.5. Single Outputs Are Insufficient Evidence of Persistent Visibility
One generated response should not be interpreted as a durable provider-selection pattern.
764.6. Longitudinal Testing Does Not Reveal Proprietary Mechanisms
Repeated observations can identify patterns without proving the internal processes responsible for them.
764.7. Recommendation Visibility Depends on Context
A provider may be relevant to one customer scenario and inappropriate for another.
764.8. Mention Volume Does Not Establish Financial GEO Quality
High visibility may coexist with inaccurate products, weak eligibility fit or incorrect regulatory information.
764.9. Citation Frequency Does Not Equal Financial Authority
Citations must be interpreted according to relevance, source quality, context and supporting evidence.
764.10. Product Information Changes
Rates, fees, features, eligibility and availability may change, making historical descriptions unreliable.
764.11. Regulatory Information Changes
Authorisation, licensing and permitted activities may change across jurisdictions.
764.12. Financial GEO Attribution Is Incomplete
AI-assisted discovery may influence users before a website visit, without a click or across several research sessions.
764.13. Customer Acquisition Causation Requires Evidence
Changes in enquiries or applications should not automatically be attributed to GEO interventions.
764.14. Financial GEO Overlaps with Established SEO
Many GEO capabilities depend on technical SEO, information architecture, content quality, entity clarity and external authority.
764.15. GEO Does Not Replace Conventional Search
Traditional search remains relevant throughout financial information gathering, comparison and provider evaluation.
764.16. GEO Adds Distinct Observation Requirements
Generative discovery introduces additional questions about sources, citations, product representation, comparisons and recommendations.
764.17. GEO Terminology Continues to Evolve
Industry definitions and measurement practices may change as generative systems develop.
764.18. Framework Methods Must Remain Adaptive
Stable principles may remain useful even when particular platforms or measurement approaches change.
764.19. Financial Source Coverage Is Incomplete
No monitoring programme can guarantee observation of every source or financial information environment.
764.20. Source Convergence Does Not Guarantee Independence
Several sources may reproduce the same underlying claim, including an outdated or incorrect claim.
764.21. Financial Suitability May Require Personal Information
General search scenarios cannot reliably establish individual product suitability where important customer circumstances are unknown.
764.22. Regulatory Evidence Is Not a Universal Endorsement
Authorisation for a particular activity does not establish suitability or approval of every product associated with a brand.
764.23. AI Recommendation Confidence Is Conceptual
The framework's Recommendation Confidence construct is not a disclosed score used by AI providers.
764.24. Financial GEO Outcomes Cannot Be Guaranteed
No methodology can guarantee citations, comparison inclusion, provider recommendations, customer acquisition or financial outcomes.
Research boundary: The framework provides a structured approach to financial information assessment and observable AI representation. It does not establish proprietary AI decision criteria or guarantee commercial, regulatory or customer outcomes.
765. Frequently Asked Questions
1. What is Financial GEO?
Financial GEO, or Generative Engine Optimisation for Financial Services, examines how financial organisations, products and supporting evidence are represented in AI-generated answers, financial comparisons and provider recommendations.
2. How does Financial GEO differ from traditional Financial SEO?
Traditional Financial SEO focuses substantially on discoverability and performance in conventional search environments. Financial GEO adds explicit assessment of AI-generated source references, citations, product accuracy, provider comparisons and recommendation context. The two disciplines overlap significantly. See Financial Services SEO in an AI Search Environment.
3. What is the core Financial GEO progression?
The framework uses: Entity Clarity → Product Clarity → Regulatory & Trust Evidence → Source Authority → Citation Eligibility → Customer Fit → Recommendation Confidence → GEO Visibility. This is a conceptual model, not a disclosed AI ranking process.
4. Why is financial entity clarity important?
Financial brands may operate through several legal or regulated entities. Accurate descriptions help distinguish the organisation providing a product, the responsible entity and the relevant jurisdiction.
5. What information should financial product pages contain?
Relevant information may include product features, intended customers, eligibility, fees, rates, restrictions, risks and geographic availability. Material details should be current and appropriately reviewed.
6. How does regulatory information affect Financial GEO?
Regulatory information can help users verify material claims about an organisation's status and responsibilities. Such information must be linked accurately to the relevant entity, activity and jurisdiction. The Financial Services AI Trust Framework examines these relationships.
7. What is financial source authority?
Financial source authority concerns the relevance and credibility of information available through provider websites, official records, research, professional publications and independent sources. It should not be reduced to citation or link counts.
8. What is citation eligibility in Financial GEO?
Citation eligibility is the conceptual potential for information to serve as a useful reference. The framework considers relevance, clarity, evidence, authority and freshness. These qualities do not guarantee that an AI system will cite a source.
9. Can financial organisations guarantee AI citations?
No. AI citations depend on systems and processes outside the organisation's direct control. Improving information quality and accessibility does not guarantee inclusion.
10. What is source convergence?
Source convergence occurs when relevant provider, official and independent information supports a materially consistent understanding of a financial claim. Agreement should still be examined for source independence and accuracy.
11. How should conflicting financial information be handled?
Material discrepancies involving rates, fees, eligibility, regulatory status or product availability should be investigated. Confirmed inaccuracies should be corrected through appropriate owned or external channels, followed by monitoring.
12. What is Financial GEO recommendation confidence?
Recommendation Confidence is a CGO Media conceptual construct examining customer relevance, product fit, eligibility, regulatory evidence, trust, commercial terms and external validation. It is not a published AI provider score.
13. Why does customer eligibility matter for AI financial recommendations?
A financial product may appear relevant but be unavailable because of residence, income, turnover, credit profile, business type or other conditions. Eligibility information is therefore essential when evaluating whether a provider suggestion is appropriate.
14. How does Financial GEO apply to banks?
Banks may need to manage product information, regulated entities, geographic availability, pricing, eligibility and institutional descriptions across complex websites and multiple markets.
15. How does Financial GEO apply to insurers?
Insurers should consider accurate descriptions of coverage, exclusions, eligibility, policy conditions and the organisation responsible for providing the insurance. General AI-generated comparisons should not be treated as definitive suitability assessments.
16. How does Financial GEO apply to lenders and mortgage providers?
Lenders should communicate relevant borrowing conditions, rates, fees, eligibility and assumptions. Monitoring should investigate whether AI-generated answers confuse indicative examples with guaranteed terms.
17. How does Financial GEO apply to investment providers?
Investment organisations should maintain accurate descriptions of services, intended customers, fees, risks, professional responsibilities and eligibility. AI-generated recommendations should not be interpreted as personalised investment advice.
18. How does Financial GEO apply to payment providers and fintech companies?
Payment providers and fintech companies should clarify product functionality, charges, settlement arrangements, supported markets, customer eligibility and relationships with relevant regulated partners.
19. What are the five Financial GEO measurement layers?
The five layers are Source Visibility, Citation Visibility, Entity & Product Accuracy, Comparison Visibility and Recommendation Visibility. They distinguish different observable outcomes rather than combining all mentions into one metric.
20. What is qualified Financial GEO visibility?
Qualified visibility occurs when a financial provider is represented accurately and appears in a relevant customer context with appropriate supporting evidence. The objective is meaningful provider discovery rather than maximum AI mention frequency.
21. How should financial organisations monitor AI-generated answers?
They should use realistic scenario libraries segmented by product, customer type, market and decision stage. Observations should record relevant system conditions and investigate recurring material errors.
22. How can original financial research support GEO?
Transparent research, useful datasets and documented methodologies can provide relevant reference material for financial audiences and independent publications. The CGO AI Citation Framework provides additional context for citation assessment.
23. How should a financial organisation implement GEO?
Implementation should begin with technical accessibility, entity accuracy, product information, regulatory evidence, source mapping and structured monitoring. The Financial SEO & AI Implementation Roadmap provides a companion implementation structure.
24. Where can readers find the complete Financial Services research programme?
The Financial Services AI & GEO Search Research Library brings together six research papers covering Financial SEO, GEO, AI Trust, Provider Selection, Search Authority Maturity and implementation.
766. Conclusion
Financial GEO introduces a broader model of financial visibility in which banks, insurers, lenders, investment firms, payment providers and fintech organisations are not only competing for conventional search exposure, but are also being represented within AI-assisted information, comparison and provider-discovery environments.
The central challenge is not simply to increase the number of times an AI system mentions a financial organisation.
It is to support accurate provider identification, clear product understanding, verifiable institutional claims, relevant source references and appropriate customer consideration.
766.1. Entity Clarity Establishes the Foundation
Financial organisations should be identifiable through accurate relationships between groups, legal entities, regulated providers, brands, products and markets.
These relationships matter because the organisation recognised by a customer may not be the legal entity responsible for a particular financial service.
Consistent entity information supports understanding across financial websites, external references and AI-assisted discovery.
766.2. Product Clarity Supports Financial Evaluation
Customers require understandable information about product types, features, fees, rates, eligibility, limitations and relevant risks.
Generative summaries can omit important qualifications, making accurate source information and continued monitoring particularly important.
Product clarity should therefore be treated as an ongoing operational responsibility.
766.3. Regulatory and Trust Evidence Supports Verification
Important claims concerning authorisation, licensing, customer protection and professional responsibility should be supported by relevant evidence.
Such evidence must correspond to the correct entity, activity and jurisdiction.
Regulatory status is not a universal endorsement of every product, nor does it establish suitability for an individual customer.
766.4. Source Authority Requires Credible Information
Financial organisations are represented through provider information, official records, independent research, financial media and comparison services.
These sources can contribute different forms of evidence.
The strategic priority is to maintain reliable information and identify material inconsistencies rather than simply accumulate external references.
766.5. Citation Eligibility Depends on Source Utility
Useful financial sources combine relevance, clarity, evidence, authority and freshness.
Original research and well-maintained product resources may contribute valuable information to the wider financial ecosystem.
However, source quality does not guarantee AI citation or recommendation.
766.6. Customer Fit Determines Recommendation Relevance
Financial providers should be evaluated in relation to the actual customer scenario.
Product fit, eligibility, risk, pricing, service requirements and jurisdiction can materially affect whether a provider is appropriate.
A provider appearing in a generated comparison should not automatically be treated as suitable for the individual customer.
766.7. Comparison and Recommendation Visibility Must Be Distinguished
Being cited, appearing in a comparison and receiving a recommendation are different observable outcomes.
Financial GEO measurement should preserve these distinctions.
The framework therefore identifies five measurement dimensions:
- Source Visibility.
- Citation Visibility.
- Entity & Product Accuracy.
- Comparison Visibility.
- Recommendation Visibility.
These dimensions provide a more informative basis for assessment than mention volume alone.
766.8. Qualified Financial GEO Is the Strategic Objective
The research defines qualified Financial GEO performance conceptually through:
Relevant Customer Presence + Accurate Provider Representation + Strong Trust Evidence + Appropriate Recommendation
This approach prioritises accurate, contextually relevant financial discovery.
It does not imply that AI recommendations constitute regulated advice or independently establish product suitability.
766.9. Original Research and External References Can Reinforce Authority
Financial organisations may strengthen their wider information environment through transparent research, useful market data, professional contributions and credible independent references.
The potential long-term relationship is:
Useful Financial Information → Strong Evidence → External Reference → Greater Provider Authority → Better GEO Visibility → More Qualified Discovery → More Evidence
This is a conceptual improvement cycle rather than a guaranteed causal process.
Its practical value lies in connecting research quality, external information and ongoing provider representation.
766.10. Customer Outcomes May Contribute Further Evidence
Where appropriate and lawfully documented, customer experiences and service outcomes may contribute case studies, research or independent references.
Such evidence should be accurate, representative of its actual scope and respectful of financial confidentiality and privacy obligations.
Positive customer outcomes do not guarantee subsequent AI visibility.
However, useful evidence may contribute to a more informative public understanding of a financial organisation.
766.11. Financial GEO Requires Continuous Monitoring
AI systems, products, regulatory conditions and customer requirements evolve.
Financial organisations should therefore maintain the ability to detect change, investigate material errors, strengthen information and reassess results.
The continuing operational cycle is:
Observe → Diagnose → Prioritise → Strengthen → Validate → Learn → Adapt
For material errors, the recovery process is:
Detect → Verify → Diagnose → Correct → Re-Test → Learn
These processes support resilience without assuming direct control over external generative systems.
766.12. Adaptive Financial GEO Is the Long-Term Capability
Financial GEO practices should evolve as generative systems and information environments change.
Nevertheless, several principles remain relevant:
- Clear financial entities.
- Accurate product information.
- Current regulatory evidence.
- Appropriate trust documentation.
- Relevant external information.
- Customer fit.
- Continued monitoring and governance.
These principles connect GEO with the broader disciplines of Financial SEO, information quality and institutional authority.
766.13. Better Representation Can Support Better Financial Decisions
The strongest potential outcome of Financial GEO is not simply more frequent AI mentions.
It is more accurate information about products, eligibility, fees, rates, regulation and practical limitations.
Better information can support more informed comparisons and reduce avoidable misunderstanding.
However, improved representation does not guarantee appropriate financial decisions or successful customer outcomes.
766.14. The Complete Financial GEO Model
The strategic relationship can be summarised as:
Clear Entity → Clear Product → Strong Regulatory & Trust Evidence → Source Authority → Citation Visibility → Provider Comparison Visibility → Recommendation Confidence → Qualified Financial GEO Visibility
This conceptual model connects institutional identity, product information, evidence, citations, customer relevance and observable generative discovery.
It should not be interpreted as a disclosed sequence used by AI systems.
766.15. Final Strategic Position
Financial services organisations should treat Generative Engine Optimisation as a continuing extension of financial SEO, product information governance, regulatory trust, entity management, research and provider-authority strategy.
The strongest Financial GEO programmes build information environments that make providers easier to identify, understand, verify, reference and evaluate appropriately.
The long-term objective is not simply to appear more frequently in generated answers.
It is to improve the accuracy, relevance and evidential quality of financial-provider representation across changing search and AI-assisted discovery environments.
Financial GEO should be measured by the quality of financial representation and customer relevance, not by AI mention volume alone.
References
The following sources provide academic and technical context for search accessibility, structured information, Knowledge Graphs, credibility assessment and the limitations of generated information.
The Financial GEO models presented in this paper are CGO Media conceptual research constructs and should not be interpreted as externally validated descriptions of proprietary AI recommendation systems.
External Academic, Technical and Search Sources
- Google Search Central. SEO Starter Guide.
- Google Search Central. Crawling and indexing overview.
- Google Search Central. Understand how structured data works.
- Google Search Central. Tell Google about localised versions of your page.
- Schema.org. FinancialService.
- Schema.org. Organization.
- Schema.org. Service.
- Hogan, A., et al. (2021). Knowledge Graphs. ACM Computing Surveys, 54(4).
- Metzger, M. J. (2007). Making Sense of Credibility on the Web: Models for Evaluating Online Information and Recommendations for Future Research. Journal of the American Society for Information Science and Technology, 58(13), 2078–2091.
- Ji, Z., et al. (2023). Survey of Hallucination in Natural Language Generation. ACM Computing Surveys, 55(12).
CGO Media Financial Services Research and Frameworks
- Wilkinson, R. (2026). Financial Services SEO in an AI Search Environment. CGO Media.
- Wilkinson, R. (2026). Financial Services AI Trust Framework. CGO Media.
- Wilkinson, R. (2026). Financial Provider Selection Model. CGO Media.
- Wilkinson, R. (2026). Financial Search Authority Maturity Model. CGO Media.
- Wilkinson, R. (2026). Financial SEO & AI Implementation Roadmap. CGO Media.
- Wilkinson, R. (2026). CGO AI Search Readiness Framework. CGO Media.
- Wilkinson, R. (2026). CGO AI Citation Framework. CGO Media.
- Wilkinson, R. (2026). CGO Entity Authority Framework. CGO Media.
- Wilkinson, R. (2026). CGO Content Authority Framework. CGO Media.
CGO Media Research Ecosystem
Financial GEO forms part of CGO Media's wider research programme examining conventional search, AI-assisted discovery, citation authority, entity representation, digital trust and organisational visibility.
The Financial Services research family connects these disciplines with sector-specific questions involving regulated identities, financial products, customer eligibility and provider evaluation.
Explore the Research Ecosystem
- CGO Media Research Library
- CGO Media Framework Library
- CGO Media Research Architecture
- CGO Media Research Observations Library
- CGO Media Statistics Library
- CGO Media Knowledge Architecture Map
Financial Services Research Library
The Financial Services research programme comprises one sector research library and six substantive research papers covering Financial SEO, GEO, AI Trust, Provider Selection, Search Authority Maturity and implementation.
Explore the Financial Services AI & GEO Search Research Library →
About Roger Wilkinson
Roger Wilkinson is an independent researcher, SEO practitioner and founder of CGO Media with more than 25 years of experience in search, digital visibility and business growth.
His research focuses on how artificial intelligence is reshaping search engines, recommendation systems, entity representation, digital authority and organisational visibility.
Roger is the creator of the CGO Framework Series, a collection of research-led methodologies designed to help organisations measure, improve and govern Search Visibility, AI Visibility, GEO and Digital Authority.
His work examines relationships between Technical SEO, Generative Engine Optimisation, Entity Authority, Content Authority, Citation Authority, Brand Signals, Knowledge Architecture and AI Search Readiness.
Through CGO Media, he develops sector-specific research frameworks intended to help organisations understand and respond to changes in search and AI-assisted discovery.
View Roger Wilkinson's researcher profile →
Author: Roger Wilkinson
Published by: CGO Media
Related Financial Services Research and Frameworks
Financial GEO: Generative Engine Optimisation is the second substantive paper within CGO Media's six-paper Financial Services research family.
Financial Services Research Library
Financial Services AI & GEO Search Research Library →
1. Financial Services SEO in an AI Search Environment
Read Financial Services SEO in an AI Search Environment →
The foundational Financial Services paper examines technical accessibility, financial information quality, regulated identity, entity authority, external evidence and AI Search Authority.
2. Financial Services AI Trust Framework
Read Financial Services AI Trust Framework →
This framework examines financial institutional trust, regulatory evidence, information accuracy and the conditions relevant to credible provider representation.
3. Financial Provider Selection Model
Read Financial Provider Selection Model →
This model examines the customer journey from financial need recognition through product understanding, provider discovery, trust, comparison and action.
4. Financial Search Authority Maturity Model
Read Financial Search Authority Maturity Model →
This model examines how financial organisations develop coordinated capabilities across SEO, financial information, entity clarity, regulatory evidence, external authority and AI visibility.
5. Financial SEO & AI Implementation Roadmap
Read Financial SEO & AI Implementation Roadmap →
This roadmap translates Financial Services SEO and GEO research into structured operational priorities, governance responsibilities and continuing improvement activities.
How the Financial Services Research Family Connects
The foundational SEO paper examines the wider search environment. The GEO paper examines generative source, citation, comparison and recommendation visibility. The AI Trust Framework evaluates relevant credibility and evidence. The Provider Selection Model examines financial customer decision-making. The Maturity Model assesses organisational capabilities, while the Implementation Roadmap provides a structure for operational development.
Together, these six papers form an integrated research architecture for financial search visibility, AI-assisted discovery, provider trust, financial product representation and qualified customer consideration.
Research Usage & Citation
CGO Media encourages financial institutions, fintech companies, payment providers, researchers, journalists, analysts, consultants and digital teams to reference this research where it contributes to analysis of Generative Engine Optimisation, AI financial discovery, citation authority, provider recommendation systems or financial digital authority.
Reasonable quotations, summaries, figures and excerpts may be used in articles, reports, presentations, academic work and other publications, provided appropriate acknowledgement is given to Roger Wilkinson and CGO Media.
Cite This Research / Embed Citation
Financial GEO: Generative Engine Optimisation for AI Search and Financial Provider Recommendation Systems, by Roger Wilkinson at CGO Media, presents a conceptual framework examining how financial services organisations can improve entity clarity, product representation, regulatory trust evidence, citation eligibility, provider recommendation confidence and qualified visibility across generative financial discovery environments.
APA Citation
Wilkinson, R. (2026). Financial GEO: Generative Engine Optimisation for AI Search and Financial Provider Recommendation Systems. CGO Media. https://cgomedia.com/financial-geo-generative-engine-optimisation/
BibTeX Citation
@misc
Author: Roger Wilkinson
Published by: CGO Media
Research category: Financial Services · Generative Engine Optimisation · AI Search · Citation Authority · Financial Entity Authority · Financial Provider Selection · Regulatory Trust
Research type: Conceptual and Strategic Research Framework
Research disclaimer: This publication is educational research. It does not constitute financial, investment, legal or regulatory advice. The conceptual models do not reproduce proprietary AI recommendation processes and do not guarantee citations, rankings, provider recommendations or financial outcomes.
For permissions relating to substantial reproduction, commercial licensing or republication of significant portions of this research, please contact CGO Media directly.